
Instafill.ai
7 days free
AI form filling · 27 fields · 1 page · done in seconds

Yes! You can use AI to fill out Form 982, Reduction of Tax Attributes

Don't type 27 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
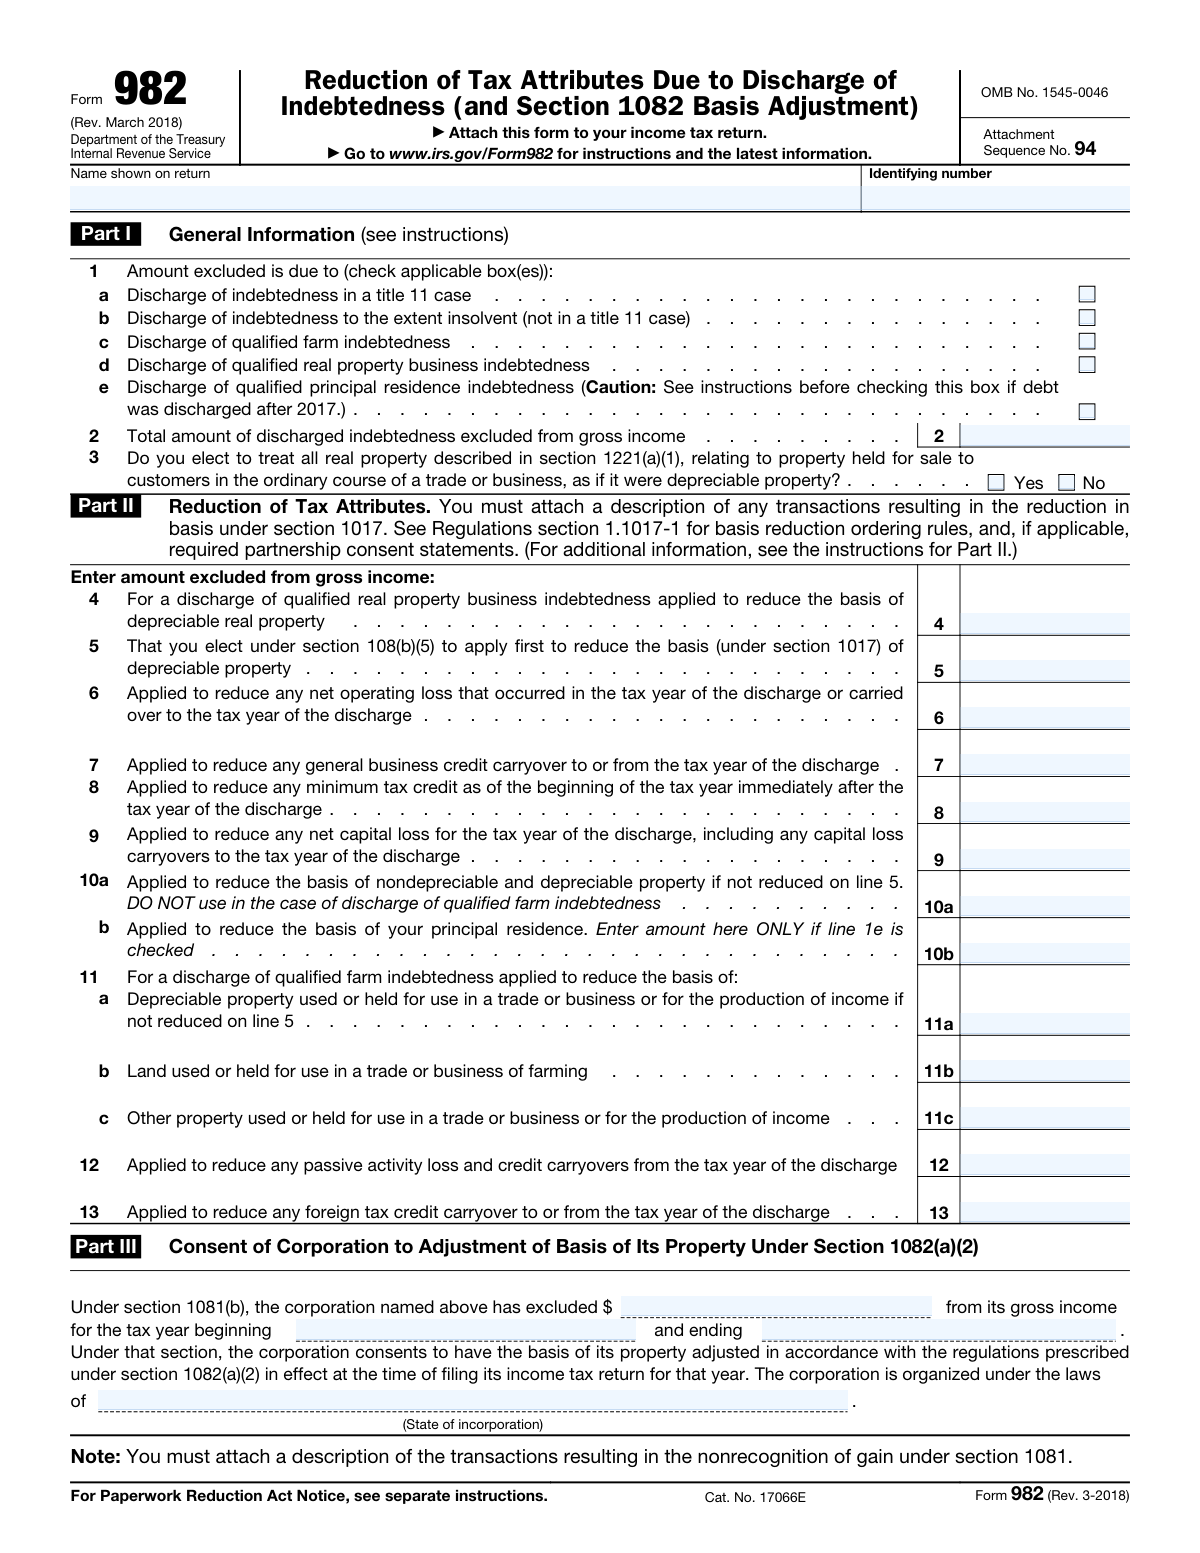
Form 982, Reduction of Tax Attributes, page 1
Basic · 35/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 982, Reduction of Tax Attributes, is used by taxpayers to report the exclusion of discharged indebtedness from gross income. This form is important for accurately reflecting tax attributes that may be affected by debt discharge, ensuring compliance with IRS regulations.
Fillable fields27
Pages1
Sections6
Form Complexity IndexBasic, 35/100

The AI checks your answers before you download

15 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Form Version Check

Ensures that the form being processed is the correct version, specifically 'Form 982 (Rev. March 2018)'. This check is crucial as it confirms that the form aligns with the December 2021 revision, ensuring that all subsequent validations are based on the most current and relevant information. It prevents the processing of outdated forms that may have different requirements or information fields.

Qualified Principal Residence Indebtedness

Confirms that the box on line 1e is checked if the qualified principal residence indebtedness was discharged before 2026 or under a pre-2026 arrangement. This validation is important to determine the eligibility for tax attribute reduction based on the timing of the discharge. It ensures compliance with the specific provisions related to discharges occurring before the stated year.

Excluded Indebtedness Amount Entry

Verifies that the excluded amount of discharged indebtedness is correctly entered on line 2. This check is essential for accurately calculating the reduction of tax attributes, as it directly impacts the amount of debt that can be excluded from taxable income. It ensures that the taxpayer is not underreporting or overreporting the amount of discharged indebtedness.

Indebtedness Amount for Principal Residence

Checks that for a qualified principal residence, the smaller of the indebtedness amount or the basis of the residence is entered on line 10b if the residence is still owned after discharge. This validation ensures that the correct amount is being used to reduce the tax attributes, which is particularly important for maintaining the integrity of the tax reporting process and avoiding errors that could result in penalties or adjustments.

Nonbusiness Debt Discharge Case Check

Confirms that the box on line 1a is checked if the nonbusiness debt discharge was in a title 11 case, or line 1b if the taxpayer was insolvent. This check is vital for determining the correct tax treatment of the discharged debt and ensuring that the taxpayer is taking advantage of the appropriate exclusions based on their specific circumstances.

Ensures that the excluded amount of nonbusiness debt is included on line 2

The AI ensures that the correct amount of nonbusiness debt that has been excluded from gross income is accurately reported on line 2 of the form. It checks for the presence of a numerical value and confirms that this value aligns with the documentation provided for the debt discharge. The AI also verifies that the exclusion is valid under the applicable sections of the tax code and that the amount entered does not exceed the limits set by law.

And 9 more checks
  • Verifies that on line 10a, the smallest of the basis of nondepreciable property, the amount on line 2, or the excess of aggregate bases over liabilities after the discharge is entered for nonbusiness debt
  • Checks that Part I is used correctly to indicate the reason for exclusion from gross income and the amount excluded for any other debt
  • Confirms that Part II is used to report the reduction of tax attributes in the specified order, unless the box on line 1d is checked or the election on line 5 is made
  • Verifies that Part III is used to exclude income under section 1081(b) if applicable
  • Ensures that specific line instructions for lines 1b, 1c, 1d, 1e, and 2 are followed correctly.
  • Checks for the attachment of any required statements or documentation as indicated in the instructions for the relevant lines.
  • Confirms that all records and worksheets used to complete Form 982 are retained for tax administration purposes.
  • Verifies that the completed Form 982 is filed with the federal income tax return for the year in which the discharge of indebtedness is excluded from income under section 108(a).
  • Ensures that the definition of qualified principal residence indebtedness on Line 1e is read and understood before checking the box.

Let AI fill out your Form 982

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 982 Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 982.
  2. Enter your name and identifying number.
  3. Check applicable boxes for discharge reasons.
  4. Fill in the total amount of discharged indebtedness.
  5. Complete Part II for tax attribute reductions.
  6. Sign and date the form electronically.
  7. Check for accuracy and submit the form.

Common Mistakes in Completing Form 982

The ones the AI is built to catch.

Incorrectly identifying the type of discharged debt
When completing Form Reduction of Tax Attributes Due to Discharge of Indebtedness, it is crucial to accurately identify the type of discharged debt on lines 1a and 1b. Failing to do so can result in incorrect reporting and potential penalties. Qualified Principal Residence Indebtedness, Nonbusiness Debt, and Any Other Debt each have unique rules and calculations. Carefully review the instructions and ensure the correct box is checked based on the specifics of the discharged debt. This will help avoid potential errors and ensure proper reporting of tax attributes.
Incorrectly entering the excluded amount of discharged indebtedness
Line 2 on Form Reduction of Tax Attributes Due to Discharge of Indebtedness requires the entry of the excluded amount of discharged indebtedness. Incorrectly entering this amount can lead to significant errors in the calculation of tax attributes. Double-check the instructions and ensure the correct amount is entered based on the specifics of the discharged debt. Properly reporting this amount will help ensure accurate calculations and avoid potential penalties.
Incorrectly reporting the basis of nondepreciable property for Nonbusiness Debt
For Nonbusiness Debt, line 10a requires the entry of the smallest of the basis of nondepreciable property, the amount on line 2, or the excess of aggregate bases over liabilities after the discharge. Incorrectly reporting this amount can lead to significant errors in the calculation of tax attributes. Carefully review the instructions and ensure the correct amount is entered based on the specifics of the discharged debt and the nondepreciable property involved. Properly reporting this amount will help ensure accurate calculations and avoid potential penalties.
Failure to attach required statements or documentation
Form Reduction of Tax Attributes Due to Discharge of Indebtedness may require the attachment of certain statements or documentation to support the information reported on the form. Failing to attach these documents can result in delays in processing and potential penalties. Carefully review the instructions and ensure all required documents are attached and properly identified. Properly attaching these documents will help ensure timely processing and accurate reporting of tax attributes.
Forgetting to enter the smaller of the indebtedness amount or basis of the residence for Qualified Principal Residence Indebtedness
For Qualified Principal Residence Indebtedness, line 2 requires the entry of the excluded amount of discharged indebtedness, which is either the smaller of the indebtedness amount or the basis of the residence. Forgetting to enter the smaller of these two amounts can result in incorrect reporting and potential penalties. Carefully review the instructions and ensure the correct amount is entered based on the specifics of the discharged debt and the residence involved. Properly reporting this amount will help ensure accurate calculations and avoid potential penalties.
Failure to retain all records and worksheets used to complete Form 982
One of the most critical mistakes when filling out Form 982: Reduction of Tax Attributes Due to Discharge of Indebtedness is not retaining all records and worksheets used to complete the form. These documents may be required for tax administration purposes, including future audits. To avoid this mistake, it is essential to keep a copy of the completed form and all supporting documentation in a safe and accessible place. Recommendation: Maintain a well-organized file containing all records and worksheets used to complete Form 982. This will ensure that the necessary documents are readily available if needed by the IRS.
Using the wrong version of Form 982 or not checking for the most current information on IRS.gov/Form982
Another common mistake is using an outdated version of Form 982 or not checking the IRS website for the most current information regarding the form. This can lead to incorrect calculations and potential discrepancies between the taxpayer's records and the IRS's records. To prevent this mistake, always ensure that the latest version of Form 982 is being used and consult the IRS website for any updates or changes to the form and instructions.
Misunderstanding the definition of qualified principal residence indebtedness or insolvency
Misunderstanding the definitions of qualified principal residence indebtedness (QPRD) and insolvency can lead to incorrect calculations and potential underreporting or overreporting of taxable income. QPRD refers to the mortgage debt secured by a taxpayer's principal residence. Insolvency is the state of being unable to pay debts as they become due. Properly understanding these definitions is crucial to accurately completing Form 982. Recommendation: Carefully review the instructions for Form 982 and consult the IRS website for definitions and examples of QPRD and insolvency. Seek professional tax advice if necessary to ensure a proper understanding of these concepts.
Not following the correct order for reporting the reduction of tax attributes and basis adjustments in Part II and Part III
Another common mistake is not following the correct order for reporting the reduction of tax attributes and basis adjustments in Part II and Part III of Form 982. This can lead to incorrect calculations and potential discrepancies between the taxpayer's records and the IRS's records. To prevent this mistake, it is essential to follow the instructions carefully and report the reductions and adjustments in the correct order. Recommendation: Carefully review the instructions for Form 982 and follow the correct order for reporting the reduction of tax attributes and basis adjustments in Part II and Part III.
Failing to check the box on line 1d for qualified real property business indebtedness or make the election on line 5 to reduce the basis of depreciable property first
Lastly, failing to check the box on line 1d for qualified real property business indebtedness or make the election on line 5 to reduce the basis of depreciable property first can result in missed opportunities to minimize taxable income. This mistake can lead to underreporting of taxable income and potential penalties. Recommendation: Carefully review the instructions for Form 982 and ensure that the correct elections are made on lines 1d and 5 to minimize taxable income.

Frequently Asked Questions About Form 982


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Oct 31 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 982.
Can I fill other forms too?
This plan is for your Form 982: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 982?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 982, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Form 982 to fill out?
Form 982 has a Form Complexity Index of 35 out of 100, in the basic tier: 27 fillable fields across 1 page. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is Form 982 and when is it used?
Form 982, Reduction of Tax Attributes Due to Discharge of Indebtedness, is used to report certain debts that have been discharged, cancelled, or forgiven. This form is required when a taxpayer has received forgiveness of debt that was previously included in their gross income due to a discharge of indebtedness. The discharge of indebtedness may be the result of a variety of circumstances, including bankruptcy, insolvency, or a non-recourse loan. Form 982 is used to determine the amount of taxable income to be reported as a result of the discharge of indebtedness.
What types of discharges of indebtedness can result in the exclusion of amount from gross income?
There are several types of discharges of indebtedness that can result in the exclusion of the amount from gross income. These include discharges of qualified real property business indebtedness, qualified farm indebtedness, and insolvency discharges. Discharges of qualified real property business indebtedness and qualified farm indebtedness are excluded from gross income if certain conditions are met. Insolvency discharges are excluded from gross income if the taxpayer was insolvent before the discharge of indebtedness. Insolvency is defined as having liabilities exceeding assets.
How do I determine which box to check in Part I of Form 982?
In Part I of Form 982, you will need to determine which box to check based on the reason for the discharge of indebtedness. Box a is for discharges of indebtedness that are excluded from gross income due to insolvency. Box b is for discharges of qualified real property business indebtedness. Box c is for discharges of qualified farm indebtedness. Box d is for discharges of indebtedness that are excluded from gross income due to bankruptcy. Box e is for discharges of indebtedness that are excluded from gross income for other reasons. It is important to carefully review the instructions for Form 982 and the applicable tax laws to determine which box to check.
What is the difference between a discharge of indebtedness in a title 11 case and one that is not?
A discharge of indebtedness in a Title 11 case refers to a discharge of indebtedness that occurs in bankruptcy proceedings. In a Title 11 case, the discharge of indebtedness is typically granted by the bankruptcy court and is binding on all creditors. A discharge of indebtedness that is not in a Title 11 case may be the result of a variety of circumstances, such as a settlement or a foreclosure. The tax treatment of a discharge of indebtedness may be different depending on whether it is in a Title 11 case or not.
What is the difference between qualified farm indebtedness and qualified real property business indebtedness?
Qualified farm indebtedness and qualified real property business indebtedness are both types of debt that may be excluded from gross income if certain conditions are met. Qualified farm indebtedness refers to debt incurred in the operation of a farm. To qualify for the exclusion, the farm must be used in a trade or business where at least 50% of the gross income is derived from farming. Qualified real property business indebtedness refers to debt incurred in the operation of a real property trade or business. To qualify for the exclusion, the real property must be used in a trade or business where at least 50% of the gross income is derived from the real property trade or business.
What is the purpose of Part II of Form 982?
Part II of Form 982, Reduction of Tax Attributes Due to Discharge of Indebtedness, is used to report the tax consequences of the discharge (forgiveness) of indebtedness. This part of the form is used to calculate the amount of debt forgiveness and the corresponding taxable income.
What is the difference between lines 4 and 10a in Part II of Form 982?
Line 4, 'Total amount realized', represents the total amount received or accrued in exchange for the discharge of indebtedness. Line 10a, 'Amount excluded from income', is the amount of indebtedness discharged that is excluded from income due to bankruptcy, insolvency, or certain other reasons.
What is the difference between lines 5 and 10b in Part II of Form 982?
Line 5, 'Mortgage indebtedness', refers to the mortgage debt on your principal residence that was discharged. Line 10b, 'Amount of nonbusiness indebtedness', is the total amount of nonbusiness indebtedness (debt other than mortgage debt) that was discharged.
What is the purpose of Part III of Form 982?
Part III of Form 982 is used to report the tax consequences of the discharge of indebtedness on property other than a personal residence. This part of the form is used to calculate the amount of debt forgiveness and the corresponding taxable income for nonresidential real property, business property, and other types of property.
What information must be provided in the description of transactions in Part II and Part III of Form 982?
The description of transactions in Part II and Part III of Form 982 should include the name and address of the lender, the date of the indebtedness was acquired, the amount of the indebtedness before it was discharged, and the reason for the discharge (such as foreclosure, short sale, or bankruptcy).
What are the basis reduction ordering rules under section 1017?
Under IRS Code Section 1017, the reduction of tax attributes due to discharge of indebtedness follows a specific ordering rule. The rules state that the debtor first applies the discharge to debt that is subject to recapture of prior losses, such as Section 1231 gains or losses. Next, the debtor applies the discharge to debt that is not subject to recapture, such as nonrecourse debt. Lastly, the debtor applies the discharge to debt that is not specifically identified, but this application is limited to the amount of the discharge that exceeds the total amount applied to recapture debt and nonrecourse debt.
What is the effect of applying the reduction of tax attributes to a net operating loss or a general business credit carryover?
When a taxpayer applies the reduction of tax attributes due to discharge of indebtedness to a net operating loss (NOL) or a general business credit carryover, the reduction can offset the NOL or carryover. The reduction is treated as a loss or deduction in the taxable year in which the discharge occurs. This can result in an immediate tax benefit if the taxpayer has taxable income in that year. If the taxpayer does not have sufficient taxable income, the reduction can be carried forward to future years to offset future taxable income.
What is the effect of applying the reduction of tax attributes to a minimum tax credit or a net capital loss?
The reduction of tax attributes due to discharge of indebtedness does not directly affect minimum tax credits or net capital losses. However, the reduction can indirectly impact these items by reducing the taxpayer's taxable income, which in turn can increase or decrease the amount of minimum tax credits or net capital losses. For example, if the reduction of tax attributes reduces the taxpayer's taxable income below the minimum taxable income threshold, the minimum tax credit may be reduced or eliminated. Conversely, if the reduction increases the taxpayer's taxable income above the threshold, the minimum tax credit may be increased.
What is the role of the corporation in Part III of Form 982?
Part III of Form 982, Reduction of Tax Attributes Due to Discharge of Indebtedness, is used by corporations to report the reduction of tax attributes due to the discharge of indebtedness. The corporation reports the amount of debt discharged, the amount of the reduction of tax attributes, and the type of debt that was discharged. The corporation also reports the amount of any gain recognized on the discharge of qualified real property business indebtedness. This information is used by the IRS to ensure that the corporation has properly reported the reduction of tax attributes and the related tax consequences.
What is the difference between a discharge of qualified farm indebtedness and a discharge of qualified real property business indebtedness in relation to the basis of nondepreciable and depreciable property?
A discharge of qualified farm indebtedness and a discharge of qualified real property business indebtedness can have different effects on the basis of nondepreciable and depreciable property. For qualified farm indebtedness, the discharge does not affect the basis of nondepreciable property, such as land. However, the discharge can reduce the basis of depreciable property, such as farm machinery, by the amount of the discharge that is attributable to the depreciable property. For qualified real property business indebtedness, the discharge can reduce the basis of both nondepreciable and depreciable property. The reduction of the basis of nondepreciable property is limited to the amount of the discharge that is attributable to the nondepreciable property. The reduction of the basis of depreciable property is the full amount of the discharge, subject to certain limitations.
What is the difference between a discharge of qualified farm indebtedness and a discharge of qualified real property business indebtedness in relation to passive activity loss and credit carryovers?
The Reduction of Tax Attributes Due to Discharge of Indebtedness form, also known as Form 982, deals with the tax consequences of the discharge of indebtedness on certain tax attributes, including passive activity losses and credits. For taxpayers with qualified farm indebtedness, the discharge of debt does not affect the loss or credit carryovers related to that activity. However, for taxpayers with qualified real property business indebtedness, the discharge of debt may result in the recapture of previously suspended losses and credits. This recapture is generally spread over a period of four years, starting with the year of discharge. It is essential to note that the rules for qualified farm indebtedness and qualified real property business indebtedness differ significantly, and taxpayers should consult the instructions for Form 982 or consult with a tax professional for more detailed information.
What is the difference between a discharge of qualified farm indebtedness and a discharge of qualified real property business indebtedness in relation to foreign tax credit carryovers?
The treatment of foreign tax credit carryovers in relation to the discharge of qualified farm indebtedness and qualified real property business indebtedness also differs. For taxpayers with qualified farm indebtedness, the discharge of debt does not affect their foreign tax credit carryovers. However, for taxpayers with qualified real property business indebtedness, the discharge of debt may result in the recapture of previously suspended foreign tax credits. This recapture is generally spread over a period of four years, starting with the year of discharge. It is essential to note that the rules for qualified farm indebtedness and qualified real property business indebtedness differ significantly, and taxpayers should consult the instructions for Form 982 or consult with a tax professional for more detailed information.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 982 filled out by AI

$0 today. Cancel before Oct 31 and you pay nothing.

7 days free, then $19.99/month · Cancel anytime