
Instafill.ai
7 days free
AI form filling · 54 fields · 2 pages · done in seconds

Yes! You can use AI to fill out Form 8288, U.S. Withholding Tax Return

Don't type 54 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
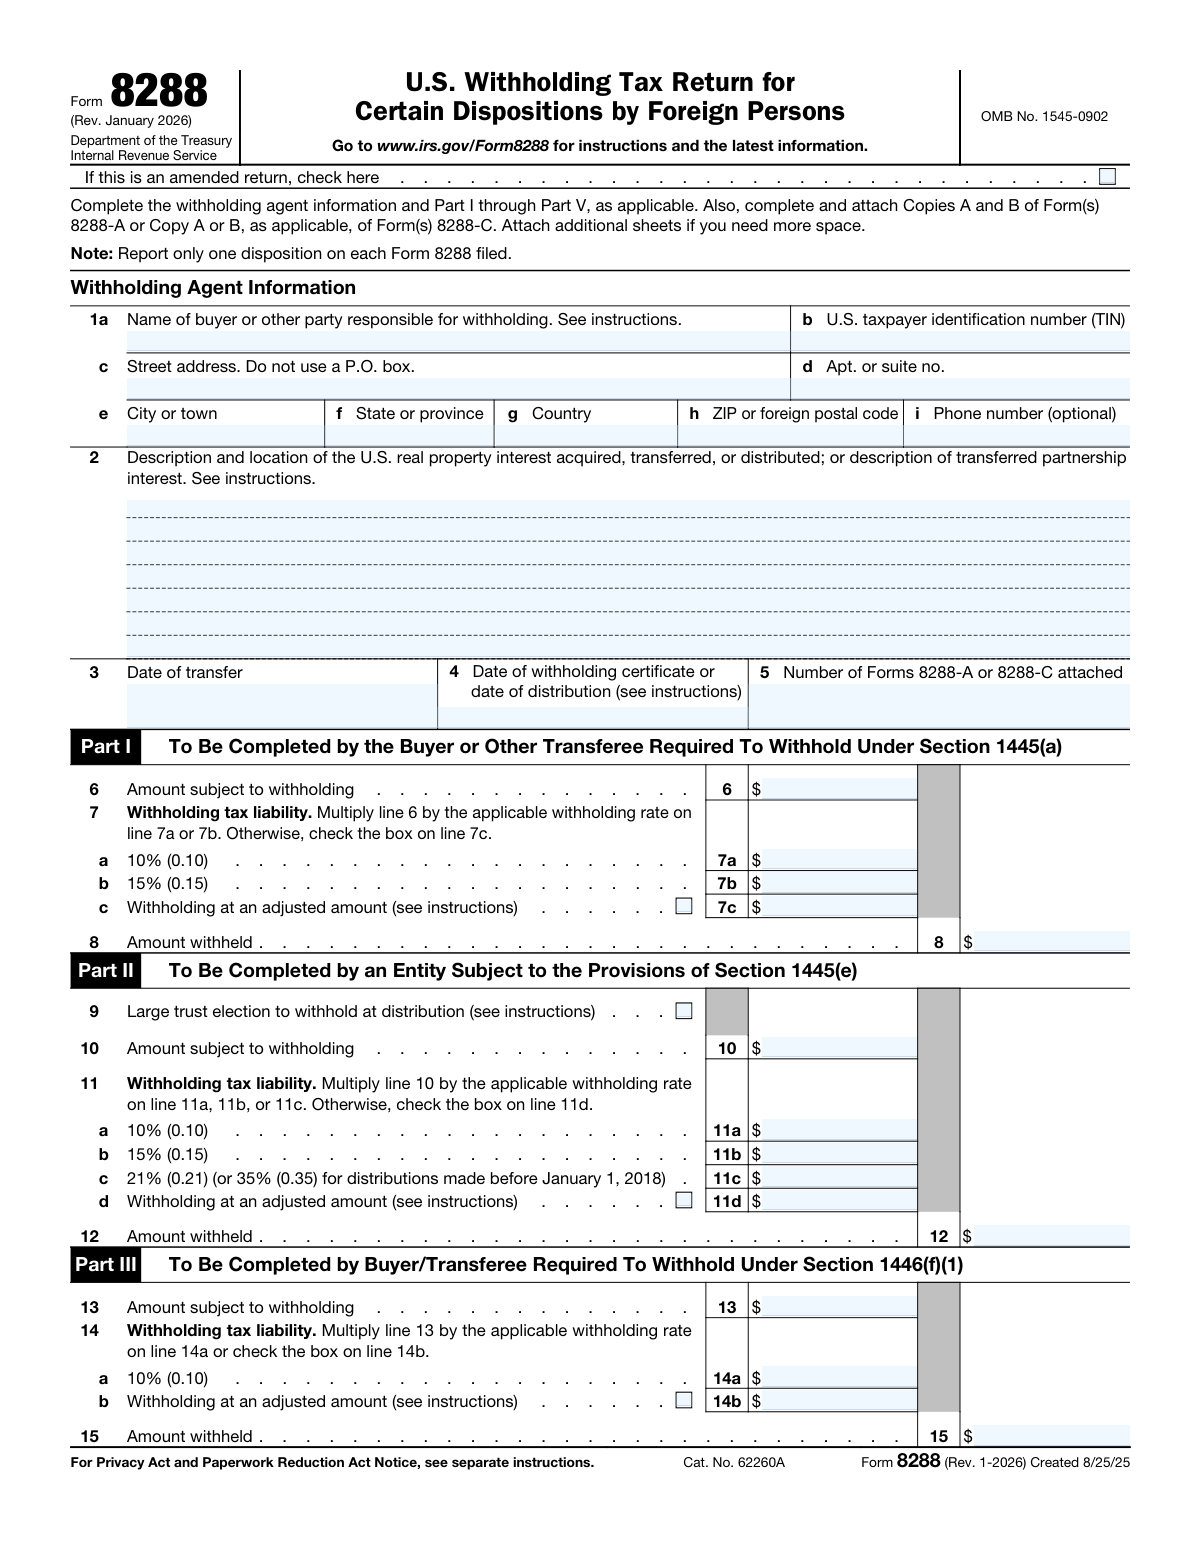
Form 8288, U.S. Withholding Tax Return, page 1
Basic · 44/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 8288, U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons, is used to report and pay withholding tax on the sale or transfer of U.S. real property interests by foreign individuals or entities. This form is crucial for ensuring that the appropriate taxes are withheld and reported to the IRS.
Fillable fields54
Pages2
Sections9
Form Complexity IndexBasic, 44/100

The AI checks your answers before you download

15 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Form Identification

Ensures that the U.S. Withholding Tax Return (Form 8288) and associated forms (Form 8288-A and Form 8288-C) are correctly identified and separated for processing. The system checks for the presence of each form and verifies that they are not mixed with unrelated documents. It also ensures that each form is the latest version required by the IRS and that they are properly labeled for easy identification during the tax processing workflow.

Completion of Form 8288

Confirms that all sections of Form 8288 are completed according to the transaction type requirements. This includes validating the completeness and accuracy of the name, address, and Taxpayer Identification Number (TIN) of the withholding agent. The system also checks for any mandatory fields that are left blank and prompts for the necessary information to ensure compliance with IRS regulations.

Property Description Accuracy

Verifies that the location and description of the property on Form 8288 are accurately provided. The system cross-references the property details with public records or other provided documents to ensure that the description matches the actual property involved in the transaction. It also checks for any discrepancies in the property identification and alerts for potential errors.

Transfer Date Verification

Checks that the date of the transfer is clearly stated and corresponds to the transaction requiring withholding. The system compares the transfer date with the dates on associated legal documents to ensure consistency. It also verifies that the date format follows IRS standards and that the date is within the tax year being reported.

Withholding Amount Calculation

Calculates the amount subject to withholding and confirms that the actual amount withheld is correctly entered on Form 8288. The system uses the provided information to compute the withholding tax based on current IRS rates and regulations. It then compares the calculated amount with the amount entered on the form to ensure that the withholding is accurate and complies with the tax obligations.

Validates that a copy of the withholding certificate for reduced rate withholding, if applicable, is attached to Form 8288.

The system ensures that if a reduced rate of withholding is applicable, a copy of the withholding certificate is attached to Form 8288. It checks for the presence of this document and alerts the user if it is missing. This validation is crucial to comply with tax regulations and to prevent any delays in processing the form. The system also assists in identifying the correct attachment based on the information provided within the form.

And 9 more checks
  • Ensures that Form 8288-A is completed separately for each person subject to withholding and that copies A and B are attached to Form 8288.
  • Verifies that the IRS will stamp Copy B of Form 8288-A and that it is forwarded to the foreign person subject to withholding.
  • Confirms that for Form 8288-C, only one form per distribution per transferee partner is attached and that Copy A is included with Form 8288.
  • Checks that Copy B of Form 8288-C is sent to the transferee(s) as required.
  • Filing Deadline Compliance
  • Submission to Ogden Service Center
  • Preparer Information Verification
  • Documentation Retention
  • Regulatory Compliance Update

Let AI fill out your Form 8288

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 8288 Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 8288.
  2. Complete withholding agent information.
  3. Fill out Parts I through V as needed.
  4. Sign and date the form electronically.
  5. Check for accuracy and submit the form.

Common Mistakes in Completing Form 8288

The ones the AI is built to catch.

Failure to file Form 8288 by the required deadline
The U.S. Withholding Tax Return (Form 8288) must be filed by the withholding agent within 20 days after the date of the transaction. Neglecting to meet this deadline can result in penalties and interest charges. To avoid this mistake, ensure that you are aware of the transaction date and mark your calendar to file Form 8288 promptly. Additionally, consider setting up automated reminders or using tax software to help manage your filing deadlines.
Incorrect reporting of the withholding agent's name, address, or TIN
It is crucial to provide accurate and complete information for the withholding agent on Form 8288. Incorrect reporting of the name, address, or Taxpayer Identification Number (TIN) can lead to processing delays and potential penalties. To prevent this mistake, double-check all information provided and consider using the IRS's Business Master File or the SSN validation tool to ensure the accuracy of the TIN. Additionally, maintain a record of the correct information for future filings.
Failure to provide a complete and accurate description of the property and its location
Providing incomplete or inaccurate information about the property and its location on Form 8288 can lead to processing delays and potential penalties. Ensure that you provide a detailed description of the property, including its type, location, and value. To avoid this mistake, gather all necessary information before filing and double-check all entries for accuracy. Consider using tax software or seeking professional advice to help ensure that you are providing complete and accurate information.
Incorrect calculation of the amount subject to withholding or the actual amount withheld
Calculating the amount subject to withholding or the actual amount withheld incorrectly can result in penalties and interest charges. Ensure that you are using the correct rates and methods to calculate these amounts. To prevent this mistake, double-check all calculations and consider using tax software or seeking professional advice to help ensure accuracy. Additionally, maintain a record of all calculations for future reference.
Failure to attach all necessary forms and attachments
Failing to attach all necessary forms and attachments, such as Forms 8288-A and 8288-C, and withholding certificates, can result in processing delays and potential penalties. To avoid this mistake, ensure that you have all required forms and attachments before filing and attach them to the return. Additionally, maintain a record of all forms and attachments for future filings.
Incomplete or inaccurate information on Form 8288-A
The U.S. Withholding Tax Return, also known as Form 8288, requires the completion of Form 8288-A for reporting withholding on payments to foreign persons. Neglecting to provide complete and accurate information on Form 8288-A, such as the name, address, and Taxpayer Identification Number (TIN) of the foreign person subject to withholding, can lead to processing delays or potential penalties. To avoid this mistake, ensure that all required information is provided accurately and completely on Form 8288-A.
Failure to sign the form or include PTIN of a paid preparer
Form 8288 must be signed by the person responsible for withholding, and if a paid preparer prepares and files the form on behalf of the withholder, their Preparer Tax Identification Number (PTIN) must be included. Neglecting to sign the form or provide the PTIN of a paid preparer can result in processing delays or potential penalties. To prevent this mistake, make sure to sign the form and, if applicable, include the PTIN of the paid preparer.
Neglecting to keep copies of all forms and documentation
Proper record-keeping is essential for withholding tax compliance. Failing to keep copies of all forms and documentation, including Forms 8288 and 8288-A, can make it difficult to provide evidence of withholding and potentially result in penalties. To avoid this mistake, maintain accurate and complete records of all withholding tax forms and related documentation.

Frequently Asked Questions About Form 8288


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Oct 31 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 8288.
Can I fill other forms too?
This plan is for your Form 8288: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 8288?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 8288, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Form 8288 to fill out?
Form 8288 has a Form Complexity Index of 44 out of 100, in the basic tier: 54 fillable fields across 2 pages. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is Form 8288 used for?
Form 8288, Withholding Tax Return, is used by U.S. persons or entities (withholding agents) to report and pay withholding tax on income paid to nonresident alien individuals or foreign entities. This form is also used to claim a reduction or exemption from withholding based on a tax treaty or other applicable law.
Who is required to complete Form 8288?
U.S. persons or entities (withholding agents) that are required to withhold taxes under the Internal Revenue Code (IRC) on income paid to nonresident alien individuals or foreign entities must complete Form 8288. This includes, but is not limited to, payments for services, rents, royalties, and interest.
What information is required in the Withholding Agent Information section?
The Withholding Agent Information section requires the name, address, and taxpayer identification number (TIN) of the withholding agent. It also asks for the withholding agent's contact information and the type of income being paid. This information is used to identify the withholding agent and ensure proper reporting and payment of withholding tax.
What is the difference between Part I, Part II, and Part III of Form 8288?
Part I of Form 8288 is used to report withholding tax on payments made to nonresident alien individuals. Part II is used to report withholding tax on payments made to foreign entities, including trusts and estates. Part III is used to report withholding tax on payments made to foreign persons under the backup withholding rules. Each part requires different information based on the type of payment and the payee.
What is the purpose of the Large trust election in Part II of Form 8288?
The Large trust election in Part II of Form 8288 allows a withholding agent to treat a foreign trust as a domestic trust for withholding tax purposes. This election can simplify the withholding process and reduce the reporting requirements for the withholding agent. However, it may also result in higher withholding tax rates for the trust. The election must be made by the withholding agent and must be based on the trust meeting certain requirements, including having a U.S. trustee or a U.S. agent.
How is the withholding tax liability calculated in Part I, Part II, and Part III of Form 8288?
Form 8288, U.S. Withholding Tax Return, is used to report withheld taxes on payments to nonresident alien individuals and foreign corporations. The tax liability is calculated differently in each part: Part I: Withholding tax on fixed and determinable income (FDI), such as interest, dividends, rents, and royalties. The tax is calculated at a flat rate based on the type of income and the payee's tax treaty status, if applicable. Part II: Withholding tax on wages paid to nonresident alien individuals. The tax is calculated based on the wages paid and the applicable tax treaty rate, if any. Part III: Withholding tax on other types of income, such as commissions, fees, and annuities. The tax is calculated based on the type of income and the payee's tax treaty status, if applicable. It is important to note that the tax rates and rules can change, so it is essential to refer to the current IRS instructions for Form 8288.
What is the difference between withholding at an adjusted amount and the regular withholding rate?
The regular withholding rate is the rate specified in the IRS tax tables or rates published in tax treaties. Withholding at an adjusted amount refers to withholding at a rate different from the regular rate due to a tax treaty provision or a request from the payee. For example, a tax treaty may provide for a reduced rate of withholding on certain types of income. In such cases, the payer must withhold at the adjusted rate and report it on Form 8288. Another situation where withholding at an adjusted amount may apply is when the payee requests a lower rate of withholding based on their income and tax filing status. The payer must obtain a valid withholding certificate, such as Form W-8BEN or W-8BEN-E, from the payee before withholding at the adjusted rate. The payer must then report the adjusted rate on Form 8288.
What is the deadline for filing Form 8288?
The deadline for filing Form 8288 depends on the payment type and the payment date. Generally, Form 8288 must be filed quarterly, by the 20th day of the month following the end of the quarter. For example, for payments made between January 1 and March 31, Form 8288 must be filed by April 20. However, there are some exceptions to this rule. For example, if the total withholding for the calendar year is less than $5,000, the form need not be filed. Additionally, if the payer is a U.S. government agency or a tax-exempt organization, they may have different filing requirements. It is important to note that failure to file Form 8288 on time can result in penalties, so it is essential to check the current IRS instructions for Form 8288 and any applicable tax laws.
What happens if a Form 8288 is not filed on time?
If a Form 8288 is not filed on time, the payer may be subject to penalties. The penalty for late filing is generally 5% of the unpaid tax for each month or part of a month that the form is late, up to a maximum of 25%. However, the IRS may waive the penalty if the payer can demonstrate reasonable cause for the late filing. It is important to note that failure to file Form 8288 on time can also result in the withheld taxes not being credited to the payee's account, which can delay their tax refund or result in additional taxes owed. Therefore, it is essential to ensure that Form 8288 is filed on time to avoid penalties and ensure that the withheld taxes are properly credited to the payee's account.
What is the process for requesting a refund of withheld taxes on Form 8288?
If a nonresident alien individual or foreign corporation has overpaid withheld taxes, they may be able to request a refund by filing Form 843, Claim for Refund and Request for Abatement. The form must be filed within three years from the due date of the return for the tax year in which the overpayment occurred. To request a refund of withheld taxes reported on Form 8288, the payee must provide the following information: - Their name, address, and taxpayer identification number (TIN) - The name and address of the payer - The tax year and quarter(s) involved - The amount of overpayment and the reason for the overpayment The payee should also attach a copy of Form 8288 to their Form 843. It is important to note that the IRS may deny a refund request if the payee fails to provide sufficient documentation or if the overpayment was due to a mathematical error or clerical mistake. Therefore, it is essential to ensure that all required information is provided and that the form is filed within the specified time frame to maximize the chances of receiving a refund.
What is the role of the preparer in completing Form 8288?
The preparer is responsible for completing and signing Form 8288, Withholding Tax Return, on behalf of the withholding agent. The preparer must ensure that all required information is accurately reported and that the form is submitted timely to the IRS. The preparer should have a valid Taxpayer Identification Number (TIN) and sign the form in the designated area. If the preparer is an entity, it must also provide its name and address.
What is the penalty for false or misleading statements on Form 8288?
The penalty for false or misleading statements on Form 8288 can be severe. The IRS may impose penalties on the withholding agent, the preparer, and any other responsible party for failing to collect, withhold, report, and pay over the required withholding tax. Penalties can include fines, interest, and even criminal charges. It is essential to ensure the accuracy of the information reported on Form 8288 to avoid potential penalties.
What is the difference between Forms 8288-A and 8288-C?
Forms 8288-A and 8288-C are both related to withholding tax reporting but serve different purposes. Form 8288-A, Statement for Agents, is used by withholding agents to report withheld taxes for the current quarter. Form 8288-C, Annual Withholding Statement for Individuals, is used by individuals to report their total withholding for the calendar year. Form 8288 is the primary form used by withholding agents to report and pay over withheld taxes to the IRS.
What is the purpose of the instructions and separate instructions sections in Form 8288?
The instructions and separate instructions sections in Form 8288 are essential for correctly completing and filing the form. The instructions provide guidance on how to fill out the form, what information is required, and when the form must be filed. The separate instructions sections contain detailed explanations of specific parts of the form, such as the calculation of withholding tax or the reporting of backup withholding. It is important to read and follow the instructions carefully to ensure the accuracy and completeness of the form.
What is the OMB No. for Form 8288?
The OMB No. (Office of Management and Budget) for Form 8288 is 1545-0047. This number is used to identify the form for statistical and reporting purposes. It is important to include this number on any correspondence or submissions related to Form 8288 to ensure proper processing by the IRS.
What is the U.S. taxpayer identification number (TIN) and where is it required on Form 8288?
The U.S. Taxpayer Identification Number (TIN) is a tax processing number issued by the Internal Revenue Service (IRS). It consists of nine digits: nine for individuals, institutions, and entities, and the last digit is a check digit. The TIN is required in Part I, Section A, Line 1 of Form 8288, 'Withholding Tax Return on Payment to a Foreign Person.' It is also required in Part II, Section A, Line 1 for each payment made to a foreign person.
What is the purpose of the description and location of the U.S. real property interest section in Part II of Form 8288?
The U.S. real property interest section in Part II of Form 8288 is used to report withholding tax on payments related to the disposition of U.S. real property interests. This includes sales, exchanges, and certain other transactions. The section requires the reporting person to provide the name and TIN of the foreign person, the description of the property, the date of the transaction, and the amount of the payment. This information is necessary for the IRS to ensure proper reporting and withholding of taxes on income derived from U.S. real property.
What is the difference between a corrected return and an original return on Form 8288?
A corrected return on Form 8288 is a submission of previously reported withholding tax information that has been amended due to errors or omissions. It is filed to correct any inaccuracies in the original return. The corrected return should be filed as soon as possible to minimize any potential penalties or interest charges. An original return, on the other hand, is the initial submission of withholding tax information for a given tax year. It should be filed accurately and timely to ensure compliance with U.S. tax laws and regulations.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 8288 filled out by AI

$0 today. Cancel before Oct 31 and you pay nothing.

Other forms like this one

tax forms: W-9, Request for Taxpayer Identification Number and Certification, Form W-2, Wage and Tax Statement, Form 1040-X, Amended U.S. Individual Income Tax Return, Form 130, Taxpayer's Notice to Initiate an Appeal, Form 1040-C, U.S. Departing Alien Income Tax Return, Form 940, Employer’s Annual FUTA Tax Return, Form 720, Quarterly Federal Excise Tax Return, Form 982, Reduction of Tax Attributes, Form 4137, Social Security and Medicare Tax on Unreported Tip Income, Form 911, Request for Taxpayer Advocate Service Assistance, Form 8960, Net Investment Income Tax, Form 8959, Additional Medicare Tax, Form 8919, Uncollected Social Security and Medicare Tax, Form 8801, Credit for Prior Year Minimum Tax, Form 990-T, Exempt Org Business Income Tax Return, Form 945, Annual Return of Withheld Federal Income Tax, Form 5330, Return of Excise Taxes, Form FTB 3514, California Earned Income Tax Credit, Form 100, CA Corp Tax Return, Form 540 2EZ, California Resident Tax Return

tax withholding forms: Form W-8BEN-E, Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities), Form W-8IMY (Rev. October 2021), Certificate of Foreign Intermediary, Foreign Flow-Through Entity, or Certain U.S. Branches for United States Tax Withholding and Reporting, Form W-4P (2026), Withholding Certificate for Periodic Pension or Annuity Payments, Form 8288, U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons, Arizona Form A1-QRT, Arizona Quarterly Withholding Tax Return, Form SS-8, Determination of Worker Status, Form W-8BEN-E, Certificate of Status of Beneficial Owner, Form 4506-W, Request for Copy of Withholding Tax Forms

withholding forms: Excess Withdrawal Request and Form W-4R, Withholding Certificate for Nonperiodic Payments and Eligible Rollover Distributions, Form W-4, Employee's Withholding Certificate, Form 593, Real Estate Withholding, Form I-589, Application for Asylum and for Withholding of Removal, Form W-4P, Withholding Certificate, Form W-8IMY (Rev. October 2021), Certificate of Foreign Intermediary, Foreign Flow-Through Entity, or Certain U.S. Branches for United States Tax Withholding and Reporting, Form W-8BEN-E, Certificate of Status of Beneficial Owner for United States Tax Withholding and Reporting (Entities), Form W-4P (2026), Withholding Certificate for Periodic Pension or Annuity Payments, Form 8288, U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons, Form W-4V, Voluntary Withholding Request, Arizona Form A1-QRT, Arizona Quarterly Withholding Tax Return, Form DE 4, Employee's Withholding Allowance Certificate, Form DE 4, Employee’s Withholding Allowance Certificate (Rev. 53), Form DE 4, Employee’s Withholding Allowance Certificate (Rev. 56), Form SS-8, Determination of Worker Status, Form W-8BEN-E, Certificate of Status of Beneficial Owner

7 days free, then $19.99/month · Cancel anytime