
Instafill.ai
7 days free
AI form filling · 188 fields · 2 pages · done in seconds

Yes! You can use AI to fill out Form 7203, S Corporation Shareholder Stock and Debt Basis Limitations

Don't type 188 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
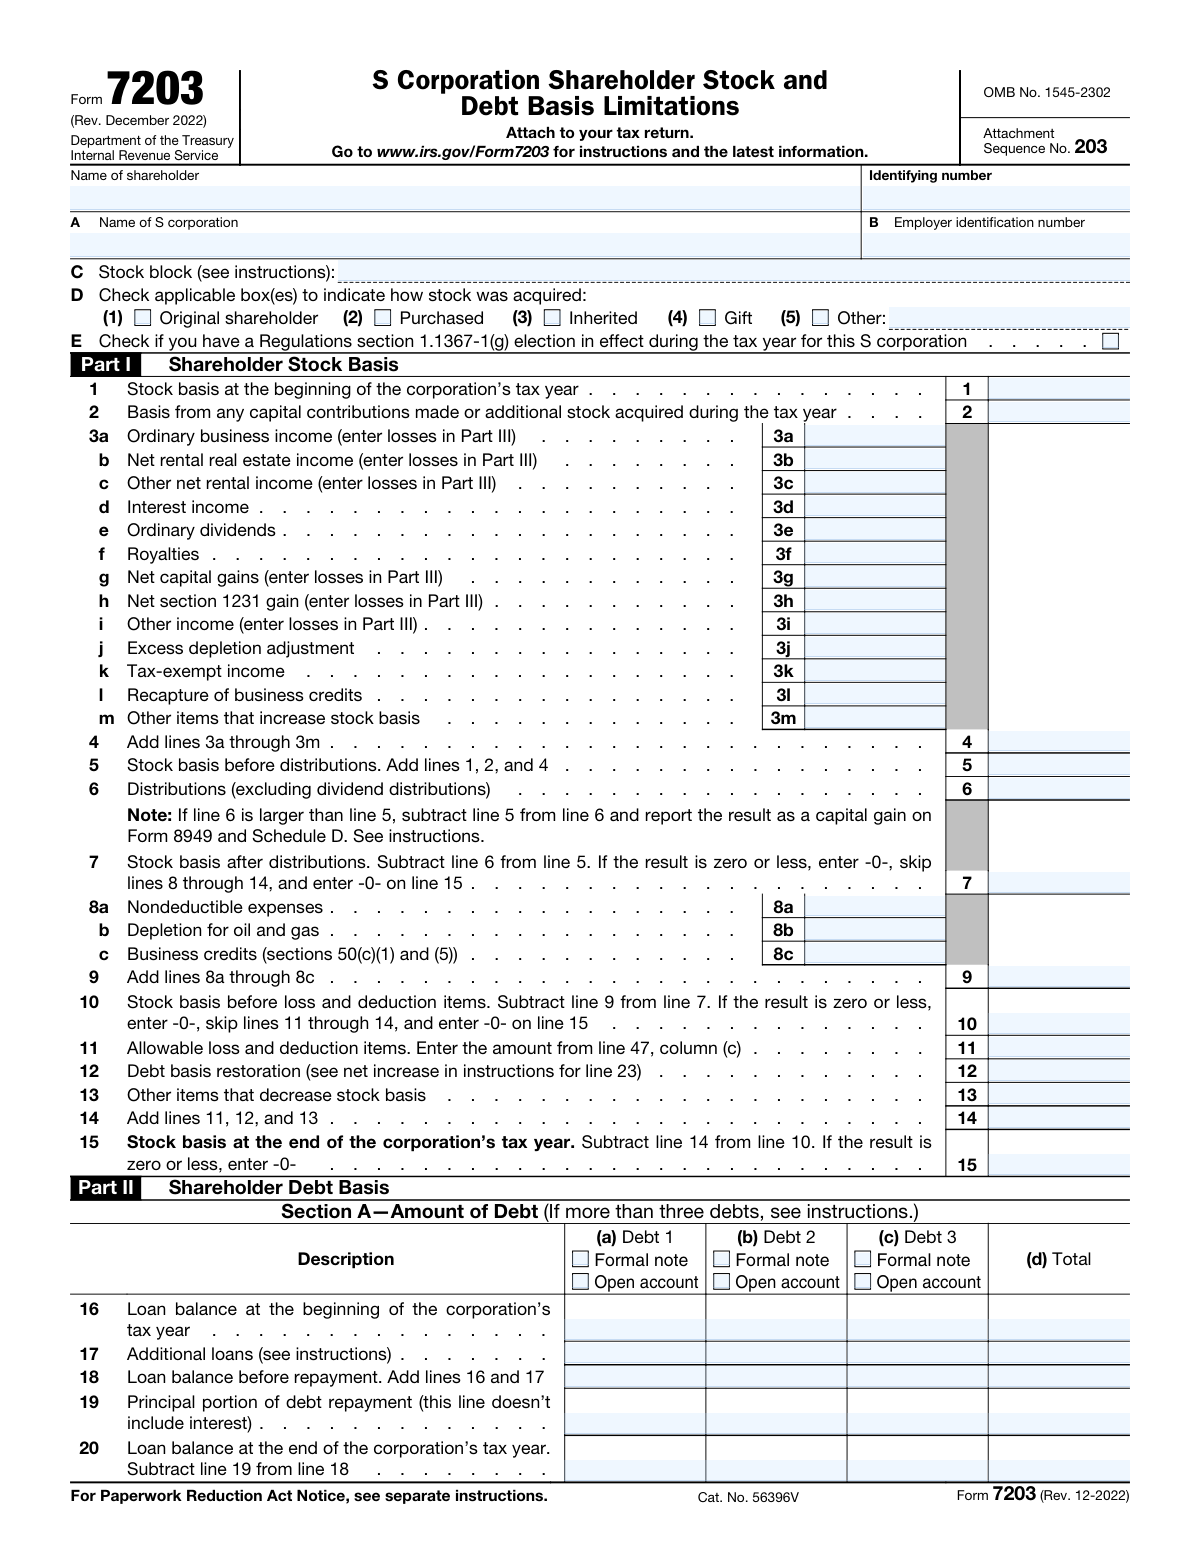
Form 7203, S Corporation Shareholder Stock and Debt Basis Limitations, page 1
Complex · 69/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 7203, S Corporation Shareholder Stock and Debt Basis Limitations, is used by shareholders of S corporations to report their stock and debt basis. This form is important for determining the tax implications of distributions and losses, ensuring accurate tax reporting.
Fillable fields188
Pages2
Sections14
Form Complexity IndexComplex, 69/100

The AI checks your answers before you download

15 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Ensures that the name of the shareholder entered matches the name shown on Schedule K-1 (Form 1120-S).

The system ensures that the shareholder's name provided on the S Corporation Shareholder Stock and Debt Basis Limitations form is consistent with the name listed on Schedule K-1 (Form 1120-S). It cross-references both documents to prevent discrepancies in shareholder identification. This validation is crucial for maintaining accurate tax records and ensuring that the correct shareholder's basis limitations are being calculated. Any mismatch in names could lead to potential errors in tax reporting and legal complications.

Confirms that all applicable sections for basis limitations are completed, including basis of stock and loans to the corporation.

The system confirms that all necessary sections relevant to the basis limitations on the form are thoroughly completed. This includes checking the accuracy of the basis of stock and any loans made to the corporation by the shareholder. It is essential that these sections are filled out to calculate the correct basis limitation, which affects the shareholder's taxable income and potential loss deductions. Incomplete sections could result in incorrect tax calculations and compliance issues.

Verifies that the beginning basis in stock on Line 1 is accurately reported.

The system verifies the accuracy of the beginning basis in stock as reported on Line 1 of the form. It ensures that the amount entered is carried over correctly from the previous tax year or the initial stock purchase documentation. This figure is foundational for subsequent calculations, and any errors here could compound throughout the form, leading to significant discrepancies in the shareholder's reported basis limitation.

Checks for proper entry of additional contributions or stock acquisitions on Line 2.

The system checks for the proper entry of any additional contributions or stock acquisitions made by the shareholder during the tax year on Line 2. It ensures that these amounts are accurately recorded and that they align with the shareholder's records. This step is vital for maintaining the integrity of the shareholder's stock basis, as it directly affects the calculation of the basis limitation for the year.

Validates the accuracy of income items that increase basis entered on Line 3.

The system validates the accuracy of income items reported on Line 3 that are supposed to increase the shareholder's stock basis. It cross-checks these entries against the corporation's financial statements and Schedule K-1 (Form 1120-S) to ensure that all income items are accounted for and correctly classified. This validation is essential for the accurate computation of the shareholder's stock basis, which impacts the allowable loss and deduction limits.

Ensures that non-dividend distributions are correctly entered on Line 6.

The AI ensures that non-dividend distributions are accurately reported on Line 6 of the S Corporation Shareholder Stock and Debt Basis Limitations form. It cross-references the amounts with the shareholder's records to confirm correctness. The AI also checks for common data entry errors and alerts the user if the figures do not align with expected values based on the shareholder's equity in the S Corporation. This validation is crucial for maintaining the integrity of the shareholder's stock basis calculation.

And 9 more checks
  • Confirms that decreases to basis for nondeductible expenses, oil and gas depletion, and certain credits are correctly entered on Lines 8a, 8b, and 8c.
  • Verifies that the total allowable loss and deduction items from stock basis on Line 11 are correctly calculated.
  • Checks for accurate entry of debt basis restoration on Line 12.
  • Validates other decreases to stock basis entered on Line 13.
  • Ensures that the beginning balance of loans is correctly entered on Line 16
  • Confirms that new loans made during the tax year are accurately reported on Line 17
  • Verifies the amount of principal repayment entered on Line 19
  • Checks for accurate calculation of debt basis restoration on Line 23
  • Validates that the gain on loan repayment is correctly reported on Line 34

Let AI fill out your Form 7203

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 7203 Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 7203.
  2. Enter your name and identifying number.
  3. Provide S corporation details and stock acquisition method.
  4. Fill in stock basis and debt basis information.
  5. Sign and date the form electronically.
  6. Check for accuracy and submit the form.

Common Mistakes in Completing Form 7203

The ones the AI is built to catch.

Failure to enter correct name as shown on Schedule K-1
When completing the S Corporation Shareholder Stock and Debt Basis Limitations form, it is crucial to ensure that the name entered in the 'Name of Shareholder' field matches the name exactly as it appears on the corresponding Schedule K-1. This inconsistency can lead to processing delays or potential rejections of the form. To avoid this mistake, double-check the name on the form against the name on the Schedule K-1 before submitting the form. Additionally, make sure to use the same format for the name, including any suffixes or titles. For instance, if the name on the Schedule K-1 includes a title like 'Mr.' or 'Dr.', ensure that the form also includes this title.
Incorrectly reporting basis for different blocks of stock
Another common mistake on the S Corporation Shareholder Stock and Debt Basis Limitations form is reporting the incorrect basis for different blocks of stock. Shareholders may have multiple blocks of stock with different acquisition dates and costs. It is essential to accurately report the basis for each block to ensure proper calculation of the total stock basis. To avoid this mistake, carefully review the records of each stock acquisition, including the purchase price, date, and any adjustments. Additionally, consider using a spreadsheet or other tool to help keep track of the different blocks of stock and their corresponding basis amounts.
Failure to indicate method of stock acquisition
The S Corporation Shareholder Stock and Debt Basis Limitations form requires shareholders to indicate the method of stock acquisition, such as a purchase from another shareholder or a gift from a family member. Failing to provide this information can lead to processing delays or potential rejections of the form. To avoid this mistake, carefully review the records of each stock acquisition and indicate the correct method in the appropriate field on the form. If unsure, consult with a tax professional or the IRS for guidance.
Failure to check box for Regulations section 1.1367-1(g) election
Another common mistake on the S Corporation Shareholder Stock and Debt Basis Limitations form is failing to check the box for the Regulations section 1.1367-1(g) election. This election allows shareholders to elect to use the adjusted basis of the stock instead of the cost basis for certain calculations. Failing to make this election can result in higher taxes. To avoid this mistake, carefully review the instructions for the form and check the box for the Regulations section 1.1367-1(g) election if applicable. Consult with a tax professional for guidance if unsure.
Incorrectly calculating basis adjustments
The S Corporation Shareholder Stock and Debt Basis Limitations form requires shareholders to calculate basis adjustments for various transactions, such as stock redemptions or stock sales. Incorrectly calculating these adjustments can lead to significant errors in the total stock basis. To avoid this mistake, carefully review the instructions for the form and consult with a tax professional or the IRS for guidance on calculating the basis adjustments. Additionally, consider using a spreadsheet or other tool to help keep track of the various transactions and their corresponding basis adjustments.
Failure to report non-dividend distributions
Shareholders of an S Corporation may receive distributions that are not considered dividends, such as return of capital or liquidating distributions. Failure to report these distributions correctly can result in incorrect tax reporting and potential penalties. To avoid this mistake, shareholders should carefully review the instructions for reporting non-dividend distributions and ensure that they are reported in the correct section of the form. It is also recommended to consult with a tax professional for guidance on the proper reporting of these distributions.
Failure to report nondeductible expenses and oil and gas depletion correctly
S Corporation shareholders may be entitled to deduct certain expenses related to the production of oil and gas, but only if they meet specific requirements. Failure to report these expenses correctly can result in underreported income and potential penalties. To avoid this mistake, shareholders should carefully review the instructions for reporting oil and gas expenses and ensure that they are reported in the correct section of the form. It is also recommended to consult with a tax professional for guidance on the proper reporting of these expenses and to maintain accurate records of all related expenses.
Failure to report loan repayments and debt basis restoration
S Corporation shareholders may repay loans they have made to the corporation, which can affect their stock and debt basis. Failure to report these repayments and the resulting debt basis restoration can result in incorrect tax reporting and potential penalties. To avoid this mistake, shareholders should carefully review the instructions for reporting loan repayments and debt basis restoration and ensure that they are reported in the correct section of the form. It is also recommended to maintain accurate records of all loan repayments and to consult with a tax professional for guidance on the proper reporting of these transactions.
Failure to complete Part III correctly
Part III of the S Corporation Shareholder Stock and Debt Basis Limitations form requires shareholders to report their stock and debt transactions, including adjustments to their basis. Failure to complete this section correctly can result in incorrect tax reporting and potential penalties. To avoid this mistake, shareholders should carefully review the instructions for reporting stock and debt transactions and ensure that they are reported in the correct section of the form. It is also recommended to maintain accurate records of all stock and debt transactions and to consult with a tax professional for guidance on the proper reporting of these transactions.
Failure to attach required statements or additional forms
The S Corporation Shareholder Stock and Debt Basis Limitations form may require the attachment of certain statements or additional forms, such as Form 8582 for reporting oil and gas expenses. Failure to attach these required documents can result in delayed processing of the form and potential penalties. To avoid this mistake, shareholders should carefully review the instructions for the form and ensure that all required statements and additional forms are attached before submitting the form to the IRS. It is also recommended to maintain accurate records of all related documents and to consult with a tax professional for guidance on the proper reporting of these transactions.

Frequently Asked Questions About Form 7203


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 1 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 7203.
Can I fill other forms too?
This plan is for your Form 7203: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 7203?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 7203, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Form 7203 to fill out?
Form 7203 has a Form Complexity Index of 69 out of 100, in the complex tier: 188 fillable fields across 2 pages. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is Form 7203 S Corporation Shareholder Stock and Debt Basis Limitations used for?
Form 7203 is used by S corporation shareholders to request consent from the IRS to make certain adjustments to their stock and debt basis in their S corporation. These adjustments may be necessary due to various transactions, such as the issuance of additional stock or the repayment of shareholder loans.
When should I file Form 7203?
Form 7203 should be filed with the IRS along with the shareholder's annual income tax return (Form 1040) for the year in which the adjustment is made. If the adjustment is made during the tax year, the form may be filed on a quarterly basis instead.
Who is required to file Form 7203?
Any S corporation shareholder who wishes to make an adjustment to their stock or debt basis must file Form 7203. This includes shareholders who have received additional stock or have repaid shareholder loans, among other transactions.
What information is required in Part I, Shareholder Stock Basis?
Part I of Form 7203 requires the shareholder to provide information about their original stock basis, any adjustments to their stock basis, and the current fair market value of their stock. This information is necessary to calculate the adjusted stock basis that will be reported to the IRS.
What is the purpose of Part II, Shareholder Debt Basis?
Part II of Form 7203 is used to report any adjustments to a shareholder's debt basis. Debt basis refers to the amount of debt that a shareholder has incurred in connection with their S corporation stock. Adjustments to debt basis may be necessary due to the repayment or cancellation of debt, among other transactions.
What is the difference between formal notes and open accounts in Part II?
Formal notes refer to written, signed, and dated evidence of indebtedness between the corporation and the shareholder. Open accounts, on the other hand, represent informal extensions of credit where no written evidence of indebtedness exists. In Part II of the S Corporation Shareholder Stock and Debt Basis Limitations form, formal notes are reported in Item 1, while open accounts are reported in Item 2.
How do I calculate the loan balance at the end of the corporation's tax year?
To calculate the loan balance at the end of the corporation's tax year, refer to the beginning balance of the loan, any principal repayments made during the tax year, and any accrued interest. The loan balance is typically reported on the balance sheet of the corporation. For the purpose of this form, the loan balance is the amount reported as of the last day of the corporation's tax year.
What is the purpose of Section B—Adjustments to Debt Basis?
Section B of the S Corporation Shareholder Stock and Debt Basis Limitations form is used to report adjustments to the debt basis of the shareholder. Debt basis refers to the shareholder's adjusted basis in the debt of the corporation. Adjustments may include changes due to loan repayments, loan forgiveness, or the issuance of additional debt. These adjustments are necessary to accurately calculate the shareholder's gain or loss on the repayment of the loan.
How do I calculate the debt basis at the end of the corporation's tax year?
To calculate the debt basis at the end of the corporation's tax year, start with the beginning balance of the debt basis from the previous year. Add any new debt issued during the tax year and subtract any repayments of debt or loan forgiveness. The resulting figure is the debt basis at the end of the tax year, which is reported on Line 11 of the form.
What is the purpose of Section C—Gain on Loan Repayment?
Section C of the S Corporation Shareholder Stock and Debt Basis Limitations form is used to calculate the gain or loss on the repayment of a shareholder loan. The gain or loss is determined by comparing the adjusted basis in the debt (reported in Section B) to the amount repaid by the corporation. This calculation is necessary to determine the shareholder's taxable income or loss from the loan repayment.
How do I report nontaxable repayments in Section C?
Nontaxable repayments, such as return of capital or redemption of stock, are reported in Section C of the S Corporation Shareholder Stock and Debt Basis Limitations form. Enter the amount of the nontaxable repayment in the appropriate box, usually Box 1 or Box 2, depending on the type of repayment. These amounts will reduce your stock basis and may affect your taxable income in future years.
What is the difference between current year losses and carryover amounts in Part III?
Part III of the S Corporation Shareholder Stock and Debt Basis Limitations form is used to report both current year losses and carryover amounts. Current year losses are the losses that can be deducted in the current tax year. Carryover amounts are the losses, deductions, or credits that cannot be used in the current year but can be carried forward to future years. It is important to distinguish between the two and report them correctly in the appropriate columns.
What types of losses can be reported in Part III?
Part III of the S Corporation Shareholder Stock and Debt Basis Limitations form allows you to report various types of losses, including: (1) Passive activity losses, (2) At-risk losses, (3) Personal casualty losses, (4) Theft losses, (5) Losses from worthless securities, and (6) Other losses. Be sure to read the instructions carefully and report the correct type and amount of loss in the appropriate column.
What are Section 179 deductions and how are they reported?
Section 179 deductions are tax deductions that allow businesses to deduct the full cost of certain types of property and equipment in the year they are purchased and placed in service. These deductions are reported on the S Corporation Shareholder Stock and Debt Basis Limitations form in Part II, Section D. Enter the total amount of Section 179 deductions for the tax year in the appropriate box.
What are charitable contributions and how are they reported?
Charitable contributions are donations made to qualified organizations, such as religious, educational, or charitable institutions. Charitable contributions are generally tax-deductible and must be reported on the S Corporation Shareholder Stock and Debt Basis Limitations form in Part II, Section E. Enter the name and address of the organization, the date of the contribution, and the amount of the contribution.
What are investment interest expenses and how are they reported in the S Corporation Shareholder Stock and Debt Basis Limitations form?
Investment interest expenses refer to the interest paid or accrued on borrowed funds that are used for the production or collection of income from investments. These expenses are reported on Schedule E (Form 1120S) of the S Corporation tax return, specifically on Line 13. Shareholders report their share of investment interest expenses on their personal income tax return, Schedule A (Form 1040), Line 8a.
What are Section 59(e)(2) expenditures and how are they reported in the S Corporation Shareholder Stock and Debt Basis Limitations form?
Section 59(e)(2) expenditures refer to expenses that are paid or incurred in connection with the production or collection of income from passive activities. These expenses are generally not deductible in the current tax year but can be added to the shareholder's basis in their S Corporation stock. Shareholders report these expenditures on Line 11 of Form 6251 (Alternative Minimum Tax—Individuals) or Line 15 of Form 6251-A (Alternative Minimum Tax—Corporations).
What are other deductions and how are they reported in the S Corporation Shareholder Stock and Debt Basis Limitations form?
Other deductions, such as losses from the sale or exchange of S Corporation stock, losses from the sale or exchange of real property used in the S Corporation trade or business, and losses from the sale or exchange of other property used in the S Corporation trade or business, are reported on Form 4797 (Sales of Business Property) and Schedule D (Form 1040) of the shareholder's personal income tax return. Shareholders should consult their tax advisor for specific guidance on reporting these deductions.
What are foreign taxes paid or accrued and how are they reported in the S Corporation Shareholder Stock and Debt Basis Limitations form?
Foreign taxes paid or accrued refer to taxes imposed by a foreign country on the S Corporation or its shareholders. These taxes may be eligible for a foreign tax credit or deduction on the S Corporation's tax return (Form 1120S) or the shareholder's personal income tax return (Form 1040). Shareholders should consult their tax advisor for specific guidance on reporting foreign taxes and claiming any available credits or deductions.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 7203 filled out by AI

$0 today. Cancel before Nov 1 and you pay nothing.

7 days free, then $19.99/month · Cancel anytime