Instafill.ai
7 days free
AI form filling · 23 fields · 2 pages · done in seconds

Yes! You can use AI to fill out Form 8855, Election To Treat a Qualified Revocable Trust

Don't type 23 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
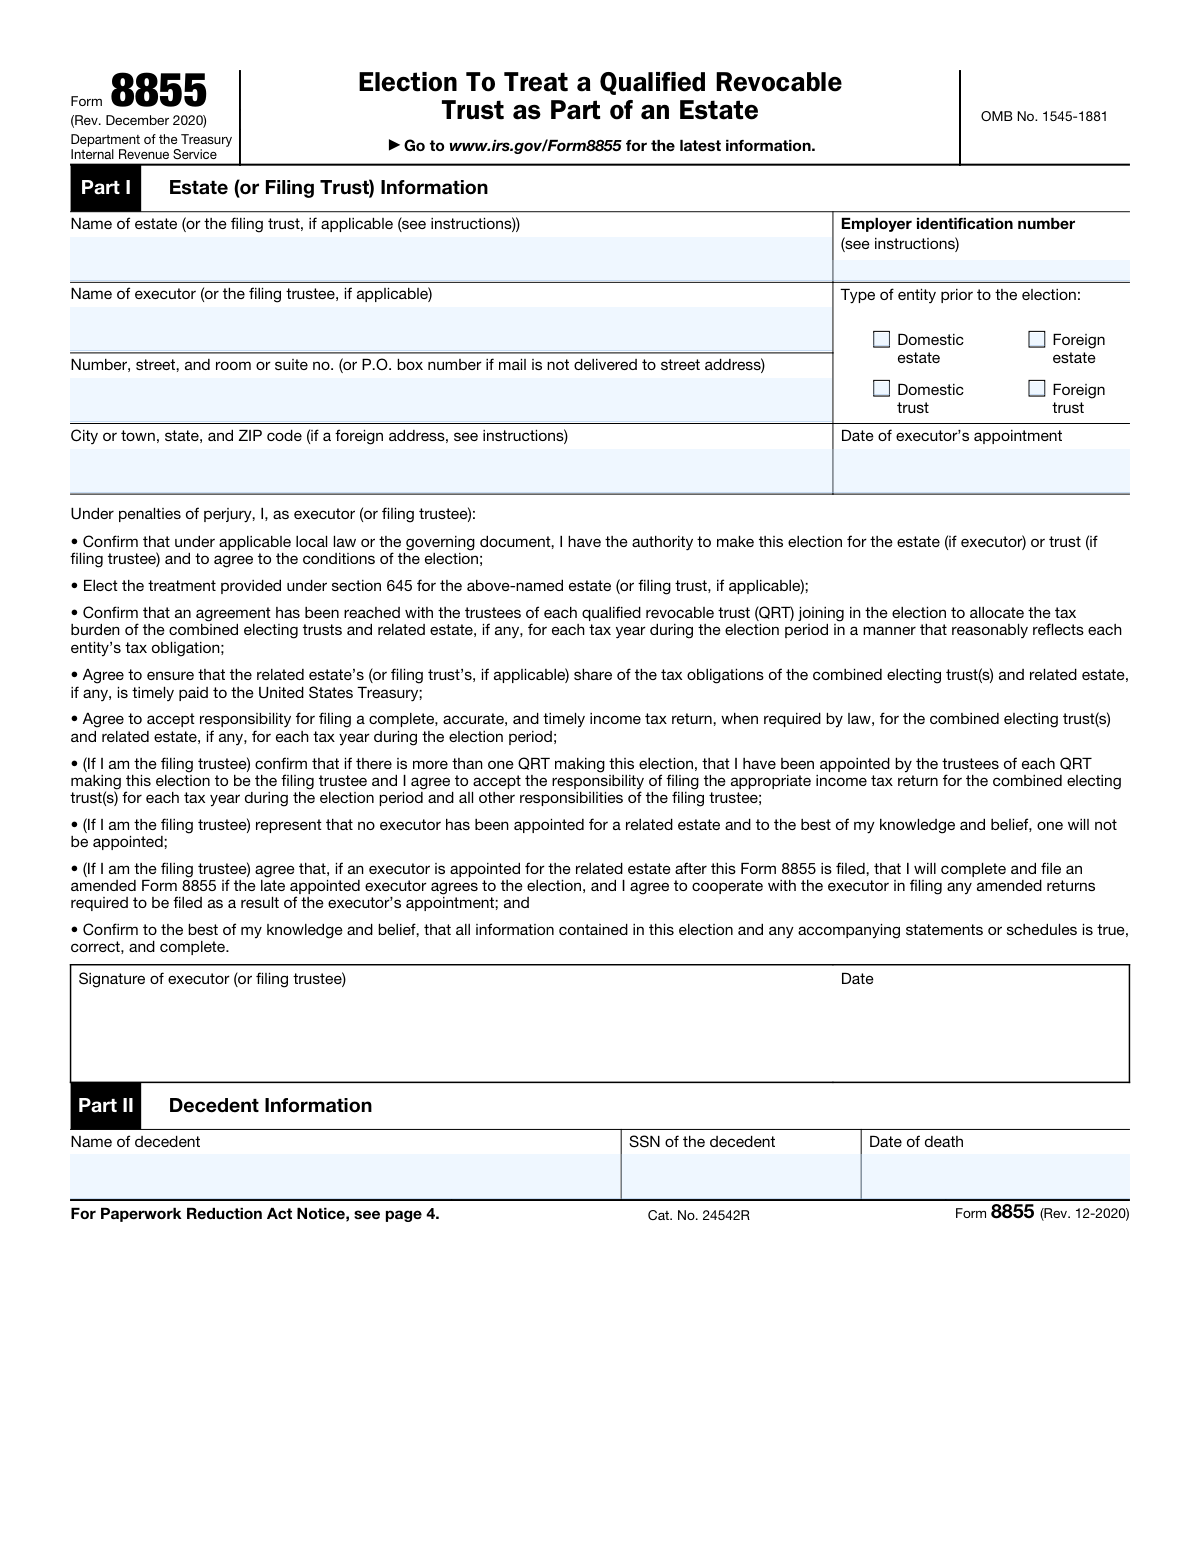
Form 8855, Election To Treat a Qualified Revocable Trust, page 1
Basic · 41/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, tables and checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 8855, Election to Treat a Qualified Revocable Trust, allows the trustees of a qualified revocable trust and the executor of the related estate to elect for the trust to be treated as part of the estate for tax purposes. This is important for ensuring proper tax treatment and compliance during the election period.
Fillable fields23
Pages2
Sections10
Tables and lists1
Form Complexity IndexBasic, 41/100

The AI checks your answers before you download

15 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Ensures that the name of the estate or the filing trust is correctly entered in Part I.

The software ensures that the name of the estate or the trust making the election is accurately captured in Part I of the form. It checks for any typographical errors, ensures consistency with official documents, and confirms that the name matches the legal designation of the entity. This validation is crucial for the proper identification of the estate or trust in question.

Confirms that the Employer Identification Number (EIN) for the estate or trust is provided in Part I.

The software confirms that the Employer Identification Number (EIN) for the estate or trust is correctly provided in Part I. It verifies that the EIN is in the proper format, consisting of nine digits with a hyphen (e.g., 12-3456789), and checks against a database to ensure that the number is valid and registered with the IRS. This step is essential for tax identification purposes.

Verifies that the name of the executor or the filing trustee is listed in Part I.

The software verifies that the name of the executor or the trustee responsible for filing the form is listed in Part I. It checks for the correct spelling of the individual's name, cross-references it with related documents to ensure accuracy, and confirms that the title or position held by the individual is appropriately indicated. This information is vital for establishing who is authorized to act on behalf of the estate or trust.

Checks that the address details in Part I are complete, including number, street, room or suite number, or P.O. box number, and that city, state, and ZIP code are correct.

The software checks that the address details provided in Part I are complete and accurate. It ensures that the number, street, room or suite number, or P.O. box number are entered, and that the city, state, and ZIP code are correct. For foreign addresses, the software also ensures compliance with the specific instructions for foreign addresses. This validation is important for maintaining accurate records and ensuring that any correspondence reaches the correct location.

Determines that the correct type of entity prior to the election is indicated in Part I.

The software determines that the correct type of entity prior to making the election is indicated in Part I. It checks that the entity is properly classified according to the options provided on the form, such as a trust or estate, and that this classification aligns with legal and tax records. This is essential for the form to reflect the entity's status accurately and to ensure that the election is processed correctly.

Validates that the date of the executor's appointment is entered in Part I.

The system ensures that the date of the executor's appointment is accurately entered in Part I of the form. This check is crucial as it establishes the timeline of the executor's authority. The AI verifies the format of the date to ensure it adheres to the required standards and cross-references it with the date of death to maintain consistency. Any discrepancies or omissions in the date entry are flagged for correction to maintain the integrity of the election process.

And 9 more checks
  • Confirms that the executor or filing trustee has signed and dated Part I
  • Ensures that the name of the decedent is correctly entered in Part II.
  • Verifies that the Social Security Number (SSN) of the decedent is provided in Part II.
  • Checks that the date of death of the decedent is correctly filled in Part II.
  • Ensures that the name of the trust is correctly entered in Part III.
  • Confirms that the Employer Identification Number (EIN) for the trust is provided in Part III.
  • Verifies that the name of the trustee is listed in Part III.
  • Checks that the address details for the trust in Part III are complete and accurate.
  • Confirms that the trustee has signed and dated Part III, thereby confirming authority and agreement to the conditions of the election.

Let AI fill out your Form 8855

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 8855 Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 8855.
  2. Enter estate or trust information.
  3. Provide decedent and trustee details.
  4. Sign and date the form electronically.
  5. Check for accuracy and submit the form.

Common Mistakes in Completing Form 8855

The ones the AI is built to catch.

Incorrect or Incomplete Name of Estate or Trust
When completing Form Election To Treat a Qualified Revocable Trust as Part of an Estate, it is essential to provide the correct name of the estate or trust in both Part I and Part III. Incorrect or incomplete names may lead to processing delays or rejections. To avoid this mistake, double-check the name of the estate or trust as it appears on the legal documents. If the name has changed, ensure that the new name is used consistently throughout the form.
Incorrect or Incomplete Employer Identification Number (EIN)
Entering an incorrect or incomplete Employer Identification Number (EIN) in Part I or Part III can cause significant issues. The EIN is a unique identifier for the estate or trust, and any discrepancies may result in processing delays or rejections. To prevent this mistake, ensure that the EIN is entered accurately and completely, including any hyphens or other special characters. If the EIN is not known, contact the IRS or the person responsible for obtaining the EIN for the estate or trust.
Failure to Sign and Date the Form
Signing and dating the form by the executor or filing trustee in Part I or Part III is a critical step in completing Form Election To Treat a Qualified Revocable Trust as Part of an Estate. Failure to do so may result in processing delays or rejections. To avoid this mistake, ensure that the person signing the form has the necessary authority and that they sign and date the form in the designated areas. Keep in mind that the form may need to be signed and dated by multiple parties, depending on the specific circumstances of the estate or trust.
Incomplete Address Details
Providing complete address details in Part I or Part III is essential to ensure that the IRS can contact the estate or trust regarding any issues or questions related to the form. Incomplete address details may result in processing delays or rejections. To prevent this mistake, ensure that the address is entered in its entirety, including the street address, city, state, and zip code. If the estate or trust has multiple addresses, ensure that the correct address is used for the specific purpose of the form.
Failure to Indicate the Correct Type of Entity
Indicating the incorrect type of entity in Part I can lead to significant issues when completing Form Election To Treat a Qualified Revocable Trust as Part of an Estate. The form requires the estate or trust to be identified as a specific type of entity, such as a grantor trust or an exempt organization. Failure to indicate the correct type of entity may result in processing delays or rejections. To prevent this mistake, ensure that the estate or trust is identified correctly based on its legal structure and tax status. Consult with a tax professional or legal advisor if necessary to confirm the correct entity type.
Incorrectly completing Part II: Decedent's Information
One of the most critical sections of the Election To Treat a Qualified Revocable Trust as Part of an Estate form is Part II, which requires the decedent's correct name, Social Security Number (SSN), and date of death. Failure to enter the correct information in this section may result in processing delays or even rejection of the form. To avoid this mistake, double-check all the information entered in Part II against the decedent's death certificate and other relevant documents. Additionally, ensure that all fields are completed in their entirety to prevent any potential errors or omissions.
Missing the Filing Deadline
Another common mistake when filing the Election To Treat a Qualified Revocable Trust as Part of an Estate form is missing the filing deadline, including extensions. The form must be filed within nine months after the decedent's death to be eligible for processing. Failure to meet this deadline may result in the loss of potential tax benefits and additional penalties. To avoid this mistake, mark the deadline on your calendar and ensure that the form is submitted well before the due date to allow for any potential processing delays or mailing time.
Sending the Form to the Incorrect IRS Service Center
It is essential to send the completed Election To Treat a Qualified Revocable Trust as Part of an Estate form to the correct IRS Service Center to ensure timely processing. Failure to do so may result in processing delays or even rejection of the form. To avoid this mistake, refer to the instructions on the form or consult the IRS website for the correct address and mailing instructions for the form.
Incomplete or Inaccurate Information in Other Sections
Other sections of the Election To Treat a Qualified Revocable Trust as Part of an Estate form, such as Part III and Part IV, also require careful completion to prevent potential errors or omissions. For instance, failure to provide complete and accurate information regarding the trust and its assets may result in processing delays or even rejection of the form. To avoid this mistake, ensure that all sections of the form are completed in their entirety and that all information is accurate and consistent with other relevant documents.
Failure to obtain a new Employer Identification Number (EIN) for the Qualified Revocable Trust (QRT) upon the death of the decedent and use it on the form
Upon the death of the grantor of a QRT, the trust becomes part of the decedent's estate and requires a new EIN. Failing to obtain and provide this new EIN on the Election To Treat a Qualified Revocable Trust as Part of an Estate form can result in processing delays or rejections. To avoid this mistake, ensure that you apply for a new EIN from the IRS as soon as possible after the grantor's death and provide it on the form when filing. It is essential to understand that the QRT's EIN is different from the decedent's Social Security Number or the EIN of the grantor's estate.
Failure to file an amended Form 8855 within 90 days of the appointment of a new executor or trustee
Form 8855, Tax Information for Withholding and Reporting (Foreign), is required to be filed by the withholding agent when making distributions from the estate or trust to a nonresident alien. If a new executor or trustee is appointed, it is essential to file an amended Form 8855 within 90 days of the appointment to reflect the new appointee's information. Failing to do so can result in penalties and processing delays. To avoid this mistake, ensure that you file an amended Form 8855 as soon as possible after the appointment of a new executor or trustee.

Frequently Asked Questions About Form 8855


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 7 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 8855.
Can I fill other forms too?
This plan is for your Form 8855: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 8855?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 8855, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Form 8855 to fill out?
Form 8855 has a Form Complexity Index of 41 out of 100, in the basic tier: 23 fillable fields across 2 pages. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is Form 8855 and what is its purpose?
Form 8855, also known as the "Election To Treat a Qualified Revocable Trust as Part of an Estate," is a tax form used to make an election to include a Qualified Revocable Trust (QRT) as part of an estate for federal estate tax purposes. This election allows the estate to use the decedent's unified credit to reduce or eliminate estate taxes on the trust's assets.
Who should file Form 8855?
Form 8855 should be filed by the executor or the filing trustee of the QRT. It is important to note that the election can only be made on a timely filed estate tax return (Form 1041) or within two years of the decedent's death, whichever is earlier.
What information is required in Part I of Form 8855?
Part I of Form 8855 requires the identification of the decedent, the name and taxpayer identification number (TIN) of the executor or filing trustee, and the name and TIN of the trust. Additionally, it asks for the date of death and the date the election is being made.
What is the role of the executor or filing trustee in making a section 645 election?
The executor or filing trustee is responsible for making the section 645 election on behalf of the estate or trust. They must ensure that the election is made in a timely manner and that all required information is accurately reported on Form 8855. Failure to make the election or to file the form correctly may result in additional taxes and penalties.
What is a qualified revocable trust (QRT) and how is it defined for the purpose of this election?
A qualified revocable trust (QRT) is a trust that was created by the decedent during their lifetime and retained the power to revoke or amend the trust. For the purpose of the section 645 election, a QRT is defined as a trust that was in existence on the decedent's date of death and that was a grantor trust for federal income tax purposes. The trust must also meet certain other requirements, such as not being a complex trust or a grantor retained annuity trust.
What is an electing trust and how is it defined?
An electing trust is a qualified revocable trust that has elected to be included in the estate of the person who established the trust for federal estate tax purposes. This election allows the trust to be treated as part of the estate for tax purposes, which can have implications for estate tax liability and the filing of estate tax returns. The trust must meet certain requirements to be considered an electing trust, including being a trust that could have been included in the decedent's estate if the decedent had not made the election.
What is the election period and when does it begin and end?
The election period for an electing trust is generally within nine months after the decedent's death. However, if the decedent was a nonresident alien at the time of death, the election period may be longer. The election can be made by filing Form 8855, Application for Portability of Estate and Gift Tax Exemption, with the Internal Revenue Service (IRS).
What is the applicable date for determining the estate tax liability?
The applicable date for determining the estate tax liability for an electing trust is the date of the decedent's death. This means that the value of the trust's assets at the time of the decedent's death is used to determine the estate tax liability, even if the trust continues to exist and grow after the decedent's death. The decedent's unified credit or exemption amount can be used to offset the estate tax liability.
What is the filing deadline for Form 8855 and where should it be sent?
Form 8855 must be filed with the IRS within the election period, which is generally nine months after the decedent's death. The form should be sent to the address listed on the instructions for Form 8855, which is currently the Austin Service Center of the IRS. It is important to note that late filings or incorrect filings may result in penalties.
Who must sign Form 8855 and what are the penalties for false statements?
Form 8855 must be signed by the executor or administrator of the decedent's estate. False statements on the form may result in penalties, including fines and even criminal charges. It is important to ensure that all information provided on the form is accurate and complete to avoid any potential penalties.
What is the process for making an amended election when an executor is appointed after a valid election is made?
When an executor is appointed after a valid Section 622(c)(3) or (4) election has been made, the election can be amended by filing Form 8855, Application for Taxpayer Identification Number for Estate and Trusts, with the Internal Revenue Service (IRS). The amended election must be filed within 60 days after the appointment of the executor or alternate payee. It is recommended to consult with a tax professional to ensure proper completion and filing of the form.
What are the tax implications of the section 645 election for electing trusts and the related estate?
Section 645 of the Internal Revenue Code allows an estate or trust to elect to be taxed as a grantor trust for income tax purposes. This election, also known as the grantor trust election, causes the income of the trust to be included in the income of the grantor or transferor for income tax purposes. The grantor trust election can have significant tax implications for both the estate or trust and the related estate. It is recommended to consult with a tax professional to understand the potential tax consequences of making this election.
What is the procedure for obtaining a new Employer Identification Number (EIN) for a QRT following the decedent's death?
To obtain a new EIN for a Qualified Revocable Trust (QRT) following the decedent's death, the person responsible for administering the trust must file Form SS-4, Application for Employer Identification Number, with the IRS. The form can be filed online, by fax, or by mail. It is recommended to consult with a tax professional or the IRS to ensure proper completion and filing of the form.
What are the recordkeeping requirements for Form 8855 and related documents?
Form 8855 and related documents, including supporting documentation, must be kept by the estate or trust for a period of at least three years from the due date of the return or the date the election was made, whichever is later. It is recommended to consult with a tax professional or the IRS for specific recordkeeping requirements.
What is the estimated time required to complete and file Form 8855?
The estimated time required to complete and file Form 8855, Application for Taxpayer Identification Number for Estate and Trusts, depends on the complexity of the estate or trust and the availability of necessary information. Generally, it can take between 30 minutes to several hours to complete the form. It is recommended to allow sufficient time to gather all required information and consult with a tax professional to ensure proper completion and filing of the form.
Where can I find additional information about the reporting rules for a QRT (Qualified Revocable Trust), an electing trust, or a former electing trust?
The Internal Revenue Service (IRS) provides detailed instructions and reporting requirements for Form 8855, Election To Treat a Qualified Revocable Trust as Part of an Estate or Trust, in Publication 590, Individual Retirement Arrangements (IRAs). You can access this publication on the IRS website (irs.gov) or by calling the IRS at 1-800-TAX-FORM (1-800-829-3676). Additionally, the IRS website offers an Interactive Tax Assistant tool to help guide you through the process of determining whether you need to file Form 8855. It is recommended that you consult with a tax professional or attorney for specific advice regarding your individual situation.
What is the Paperwork Reduction Act Notice and how does it apply to Form 8855?
The Paperwork Reduction Act (PRA) is a federal law that requires federal agencies to obtain approval from the Office of Management and Budget (OMB) before collecting certain information from the public. Form 8855 is subject to the PRA, and the IRS includes the PRA notice on the form to inform taxpayers that their responses are being collected in accordance with the PRA. The notice includes the OMB control number, which is used to identify the form for PRA purposes. The IRS uses the information collected on Form 8855 to administer and enforce the tax laws related to trusts and estates. It is important for taxpayers to provide accurate and complete information on the form to ensure proper processing and avoid potential delays or penalties.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 8855 filled out by AI

$0 today. Cancel before Nov 7 and you pay nothing.

Other forms like this one

trust forms: Private Trust (Mod(PT).2005), Form 3520 (Rev. December 2023), Annual Return To Report Transactions With Foreign Trusts and Receipt of Certain Foreign Gifts, Judicial Council of California Form DE-120, Notice of Hearing—Decedent's Estate or Trust, Judicial Council of California Form DE-120, Notice of Hearing—Decedent's Estate or Trust, Fidelity Change of Account Ownership — Mutual Fund Only Accounts (Changing to a Trust, Estate, Guardian, or Conservator Account), Fidelity Ownership Change to Trust, Fidelity Change of Account Registration — Changing to a Trust, Estate, Guardian, or Conservator Brokerage Account, Trusted Contact Authorization Form, I.B.E.W. & Electrical Industry Local 697 Money Purchase Plan and Trust Direct Rollover Request Form Due to Qualified Domestic Relations Order, Bechtel Trust & Thrift Plan Rollover Process, General Purpose Loan Application Packet, IW DC of SOV Annuity Trust, NYPD Superior Officers Council Annuity Trust Fund Plan Rollover Form, Trust Certification and Trustee Powers, Housing Agency Retirement Trust Form #190, Request to Withdraw a Rollover Account, The Housing Agency Retirement Trust 457(b) Deferred Compensation Plan Request For Distribution Form, Housing Agency Retirement Trust Transfer/Rollover Form, Qualified Retirement Plan and Trust Summary Plan Description, The Housing Agency Retirement Trust 457b Deferred Compensation Plan Change of Beneficiary Designation Form, TIAA Trust, N.A. Private Asset Management, Request for a Direct Transfer From IRA Contracts, TIAA Trust Rollover From Your Retirement Plan (ERISA)

revocable trust forms: Letter of Authorization to Change Account Title to a Grantor Revocable Trust

7 days free, then $19.99/month · Cancel anytime