How to prepare Form W-2 accurately, box by box
An accurate Form W-2 comes down to four things: each employee's name and Social Security number exactly as on their Social Security card, the right wages in each of boxes 1, 3 and 5, the correct box 12 codes, and totals that match the employment tax returns you already filed. The IRS spells all of this out in the General Instructions for Forms W-2 and W-3, which change every year. This guide follows the order an employer works in, and says which tax year a figure belongs to whenever it is year-specific.
At a glance
- Form Form W-2, Wage and Tax Statement
- Issued by Internal Revenue Service; Copy A is filed with the Social Security Administration
- Who files Employers, for each employee whose tax they withheld or whose wages reached the reporting threshold
- Where it goes Copy A with Form W-3 to the SSA; Copies B, C and 2 to the employee; Copy 1 to state or local tax departments
- Due January 31 of the following year, to the SSA and to employees (February 1, 2027 for 2026 forms)
- Catalog forms Form W-2, Wage and Tax Statement
- Form categories IRS forms, Payroll forms
Who needs a Form W-2
You file a Form W-2 for each employee you paid for services in your trade or business, related or not, if you withheld any income, Social Security or Medicare tax. You also file one for an employee you paid at or above the reporting threshold even if you withheld nothing. That threshold was $600 for years before 2026. For wages paid in 2026 it is $2,000, under P.L. 119-21, and it is indexed for inflation after 2026.
Form W-3 travels with it. Anyone who files Forms W-2 on paper or electronically also files a Form W-3, which totals them. Keep a copy of Form W-3 and of each Copy A for at least four years.
Before you start
- Employee names and SSNs Exactly as on each Social Security card, not from an application or a tax return. The SSA's free verification service is linked from its employer page.
- Your EIN and business name Exactly as on Form 941 (or 943, 944, CT-1 or Schedule H). A mismatch between those returns and the W-2 is one of the errors the IRS lists.
- Payroll totals Year-to-date for each employee: gross pay, pre-tax deductions such as 401(k) deferrals, taxes withheld, tips, benefits and state wages.
Box by box
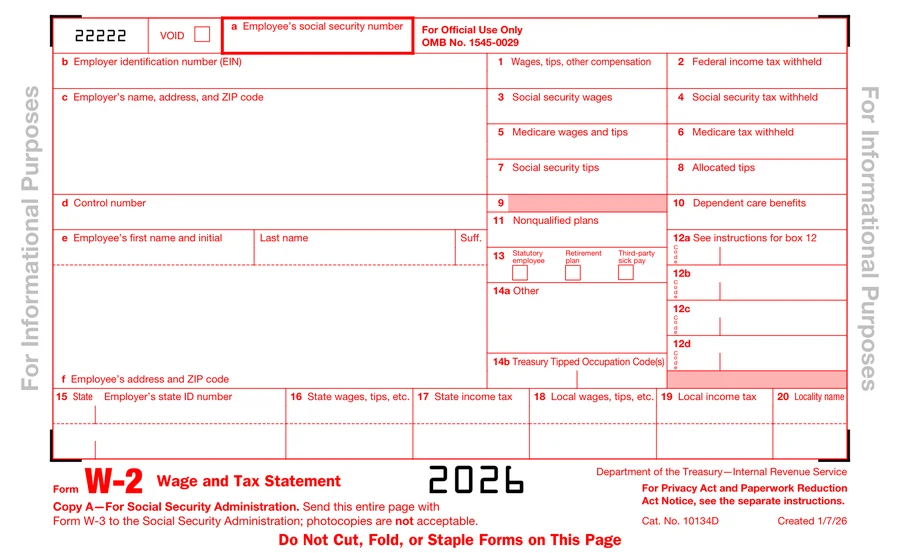
Boxes a to f identify the employee and employer. Enter the employee's name as on the card, first name and initial in the first field, surname in the second; no titles such as "Dr." Never truncate the EIN. You may truncate the SSN on employee copies, never on Copy A.
Box 1 is taxable wages, tips and other compensation. It leaves out elective deferrals such as employee 401(k) and 403(b) contributions, so it is often lower than boxes 3 and 5.
The IRS publishes the current Form W-2 each year.
Box 2 is the federal income tax withheld for the year.
Boxes 3 to 7: Social Security and Medicare. Box 3 is wages subject to Social Security tax, including 401(k) deferrals that box 1 leaves out, up to the year's wage base. Box 4 is the employee's Social Security tax withheld, not your share. Box 5 is Medicare wages and tips, with no cap, and box 6 the Medicare tax withheld at 1.45%, plus the 0.9% Additional Medicare Tax on wages above $200,000 in the year. Box 7 is Social Security tips the employee reported.
| Figure | 2026 amount |
|---|---|
| Social Security wage base (boxes 3 and 7 combined) | $184,500 |
| Most Social Security tax withheld (box 4) | $11,439 |
| Wages above which Additional Medicare Tax is withheld | $200,000 |
The instructions' own example: an employee paid $199,750 in 2026 has 184500.00 in box 3 and 199750.00 in box 5.
Box 12: codes. Each entry is an IRS code and an amount, such as D 5300.00 for $5,300 of 401(k) deferrals. Use capital letters and decimal points, no dollar signs or commas. Copy A holds four entries; for a fifth, issue a second Form W-2 with boxes a to f repeated and only the extra items filled in. Some common codes:
| Code | What it reports |
|---|---|
| D | Elective deferrals to a 401(k) plan |
| W | Employer contributions to an HSA, including what the employee elected through a cafeteria plan |
| DD | Cost of employer-sponsored health coverage (not taxable) |
| TP | Total cash tips reported to the employer (new for 2026) |
| TT | Total qualified overtime compensation (new for 2026) |
| TA | Employer contributions to an employee's or dependent's Trump account (new for 2026) |
Box 13: checkboxes. Check "Retirement plan" only if the employee was an active participant in the year, for example with contributions added to their 401(k) account; checking it when they were not is on the IRS list of common errors. "Statutory employee" is for the specific worker types the instructions name, never for common-law employees.
Box 14. On 2026 forms it is split: 14a, Other, for anything you want to tell the employee, such as union dues; 14b for the Treasury Tipped Occupation Code when tips are reported with code TP.
Boxes 15 to 20 hold state and local wages and taxes, for up to two states and two localities per form. An employee who worked in more states gets a second Form W-2. Each state sets its own reporting rules.
To fill the form itself, the Form W-2 page on Instafill.ai fills it online from your records and the details you give it, for you to check before filing.
Check it before you file
The SSA rejects a wage report outright when Medicare wages and tips (box 5) are less than Social Security wages plus tips (boxes 3 and 7), or when Social Security or Medicare tax is greater than zero while the matching wages are zero. Beyond that, compare the totals on Form W-3 with your four quarterly Forms 941 (or your Form 944) for the year.
On paper forms, the IRS asks you to avoid dollar signs, to keep the decimal point and cents, to use black ink, ideally in 12-point Courier, and never to cut, fold or staple Copy A. A Copy A printed from IRS.gov cannot be filed: it is for information only, and the scannable red version has to be ordered from the IRS.
File and furnish
Copy A with Form W-3 goes to the SSA, and Copies B, C and 2 go to the employee, both by January 31 of the year after the wages were paid. For 2026 Forms W-2 that date is February 1, 2027. If you ask before the due date, the IRS may grant one 30-day extension to file with the SSA on Form 8809, but only in extraordinary circumstances, and it does not extend the date for employees. That one is requested separately on Form 15397.
You must e-file if you file at least 10 information returns in the year, counting Forms W-2 together with Forms 1099, 1098 and the others the instructions list. The SSA's Business Services Online lets you key in up to 50 Forms W-2 at a time, or upload a file for more. Paper filers mail Copy A with Form W-3 to Social Security Administration, Direct Operations Center, Wilkes-Barre, PA 18769-0001.
Late or wrong forms carry a penalty for each Form W-2. These are the amounts for returns due after December 31, 2026:
| When the correct Form W-2 is filed | Penalty per form |
|---|---|
| Within 30 days after the due date | $60 |
| More than 30 days late, by August 1 | $130 |
| After August 1, or never | $340 |
Correct a mistake with Form W-2c
When you find an error after filing, file Form W-2c with Form W-3c as soon as possible, and give the employee a copy. A filed Form W-2 is corrected with the current Form W-2c, whether the error is a name, an SSN or an amount. If you had to e-file the original, you must e-file the correction. A change to wages or taxes may also mean correcting the Form 941 for the quarter, with Form 941-X.