Instafill.ai
7 days free
AI form filling · 425 fields · 6 pages · done in seconds

Yes! You can use AI to fill out Form 100, CA Corp Tax Return

Don't type 425 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
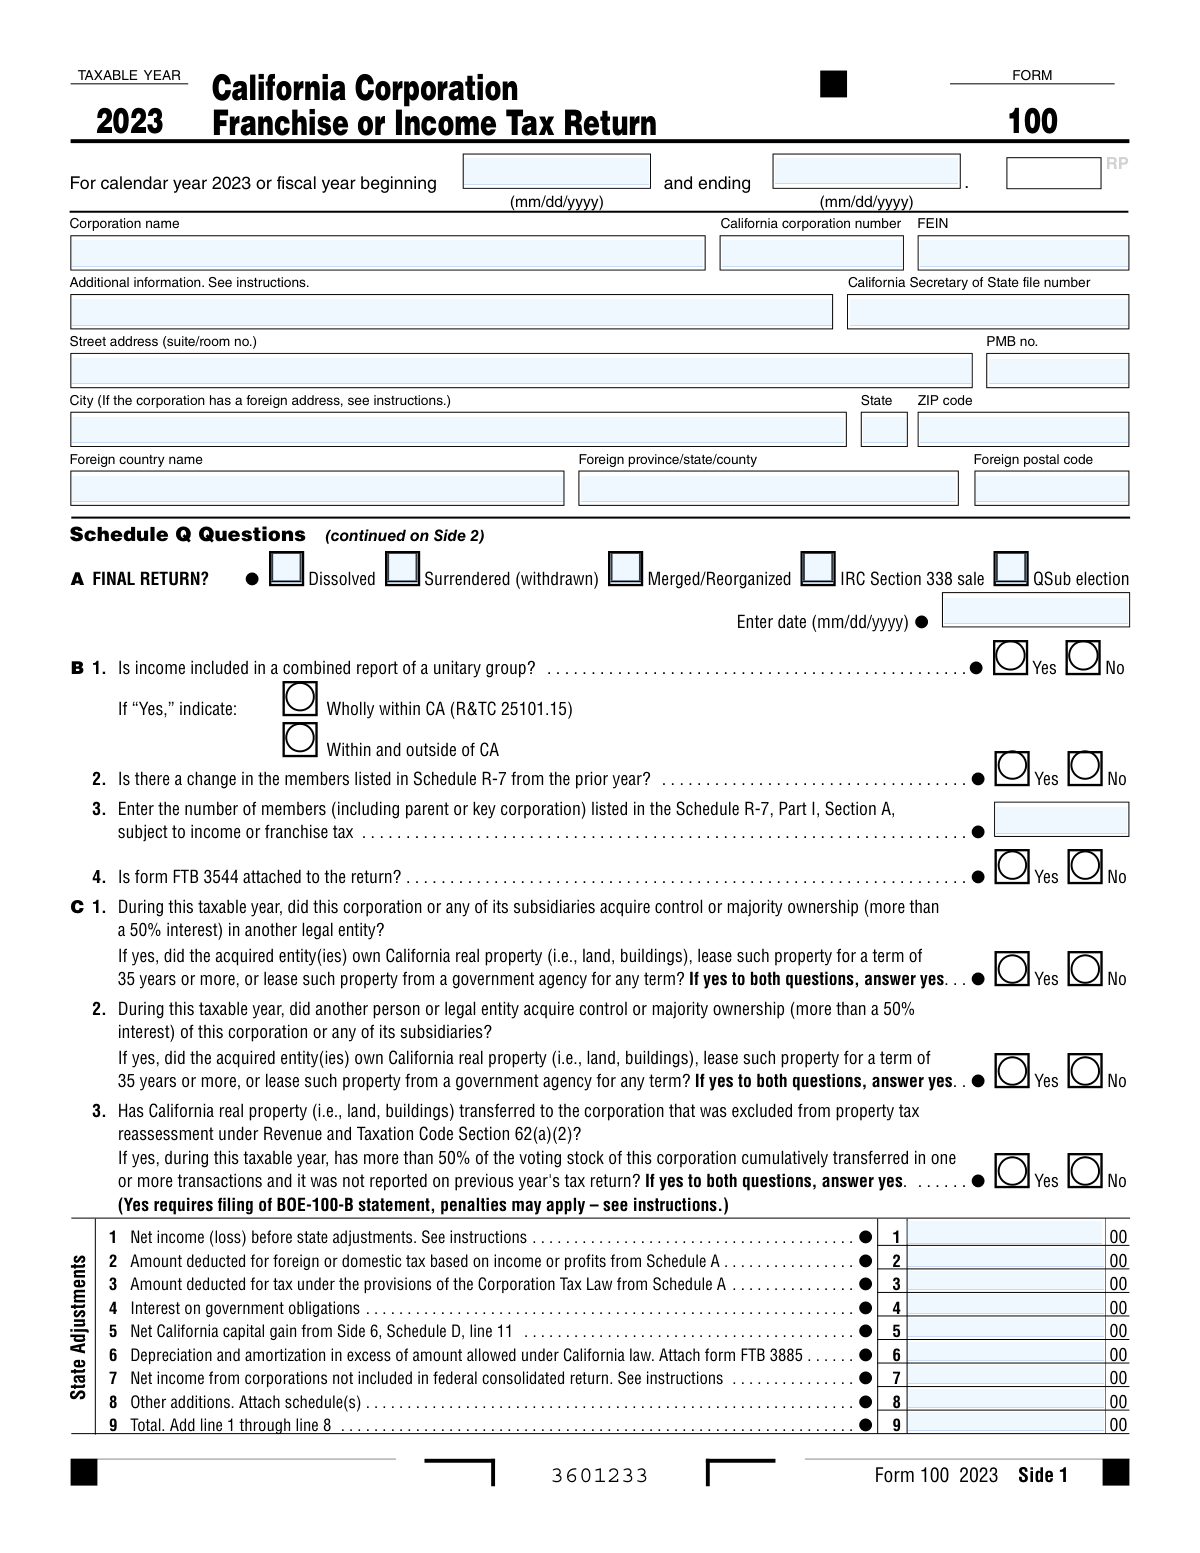
Form 100, CA Corp Tax Return, page 1
Complex · 76/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 100, California Corporation Franchise or Income Tax Return, is used by corporations to report their income, deductions, and tax liability to the state of California. Filling out this form is crucial for ensuring compliance with state tax regulations and determining the amount of tax owed or refund due.
Fillable fields425
Pages6
Sections65
Form Complexity IndexComplex, 76/100

The AI checks your answers before you download

16 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Ensures the taxable year is correctly entered as '2023'.

This validation check ensures that the taxable year field is accurately filled with the year '2023'. It verifies that the input matches the expected format of a four-digit year and corresponds to the current tax year. The check prevents the submission of outdated or future tax years that could lead to processing errors. It is crucial for aligning the tax return with the correct fiscal period.

Confirms the corporation name and additional information are accurately provided.

This validation check confirms that the corporation's legal name is correctly entered on the form. It also ensures that any additional identifying information, such as DBA (Doing Business As) names, is provided if applicable. The check includes verification of the accuracy and completeness of the information, which is essential for proper identification and correspondence. It helps to avoid confusion with other entities and ensures the tax return is associated with the correct corporation.

Verifies the complete address is included with street, city, state, ZIP code, and PMB number if applicable.

This validation check verifies that the corporation's full address is included in the form. It checks for the presence of the street address, city, state, and ZIP code, as well as a Private Mailbox (PMB) number if applicable. The check ensures that all parts of the address are provided and formatted correctly, which is necessary for any official correspondence or notices from the tax authorities. A complete and accurate address is critical for maintaining proper records and communication.

Checks the California Secretary of State file number, California corporation number, and Federal Employer Identification Number (FEIN) are present.

This validation check ensures that all necessary identification numbers are present on the tax return. It checks for the California Secretary of State file number, the California corporation number, and the Federal Employer Identification Number (FEIN). These numbers are crucial for the identification and verification of the corporation within state and federal systems. The check helps to prevent errors that could arise from missing or incorrect identification numbers.

Indicates if 'FINAL RETURN' is checked and the date of dissolution or other relevant event is entered if applicable.

This validation check indicates whether the 'FINAL RETURN' box is checked and, if so, verifies that the date of dissolution or the date of any other relevant event is properly entered. This is important for corporations that have ceased operations or undergone significant changes during the tax year. The check ensures that the tax authorities are informed of the final status of the corporation and that the return reflects the appropriate finalization details.

Confirms all Schedule Q Questions are answered, including unitary group income and changes in Schedule R-7 members.

The AI ensures that all questions on Schedule Q are fully answered, which is crucial for reporting the income of a unitary group. It checks for completeness in the responses, particularly focusing on any changes in the members of the Schedule R-7. The AI also verifies that the information provided aligns with the current tax year and cross-references data to prevent discrepancies. This validation is essential for maintaining the integrity of the tax return and avoiding errors that could lead to penalties or additional scrutiny from tax authorities.

And 10 more checks
  • Verifies responses to questions about control changes, property transfers, and inclusion in a consolidated federal return.
  • Reports net income before state adjustments and verifies the accuracy of any additions.
  • Calculates the total state adjustments by adding lines 1 through 8 and ensures accuracy.
  • Enters net income for state purposes and verifies deductions such as NOL and disaster loss.
  • Computes the tax based on net income
  • Applies any credits and calculates the total tax due
  • Reports any overpayment from the prior year, estimated tax payments, withholding, and amount paid with extension
  • Calculates the total payments and ensures accuracy
  • Determines use tax, payments balance, and franchise or income tax due
  • Calculates the refund or total amount due, including penalties and interest if applicable

Let AI fill out your Form 100

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 100 Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 100.
  2. Enter corporation name and address.
  3. Fill in taxable year and income details.
  4. Complete deductions and tax calculations.
  5. Sign and date the form electronically.
  6. Check for accuracy and submit the form.

Common Mistakes in Completing Form 100

The ones the AI is built to catch.

Incorrect Taxable Year in Section 1
Taxpayers may inadvertently enter an incorrect taxable year in Section 1 of the California Corporation Franchise or Income Tax Return. This error can lead to processing delays and potential penalties. To avoid this mistake, double-check the taxable year entered against the company's financial records and ensure it matches the year stated on the return title. Additionally, make sure all other relevant forms and filings use the same taxable year.
Omission or Incomplete Corporation Name and Address Information
Failure to provide complete and accurate corporation name and address information can result in processing delays and potential penalties. Ensure that all required fields, including the legal business name, mailing address, and principal place of business, are filled out completely and accurately. This information is crucial for the California Franchise Tax Board to properly process and communicate with the taxpayer.
Misreporting or Failure to Provide California Secretary of State File Number, California Corporation Number, and Federal Employer Identification Number (FEIN)
Taxpayers may inadvertently misreport or fail to provide essential identification numbers, such as the California Secretary of State file number, California corporation number, and Federal Employer Identification Number (FEIN), on their tax returns. These numbers are crucial for proper identification and processing of the return. To avoid this mistake, gather all necessary identification numbers before beginning the tax preparation process and ensure they are entered correctly on the return.
Failure to Indicate if This is a Final Return and Provide the Appropriate Reason and Date
Taxpayers may forget to indicate if their return is a final return and provide the appropriate reason and date. This oversight can lead to processing delays and potential penalties. To avoid this mistake, carefully review the instructions provided on the tax return and ensure that the appropriate box is checked and the reason for the final return is clearly stated. Additionally, provide the exact date of dissolution or liquidation as required.
Neglecting to Answer Schedule Q Questions Completely and Accurately
Schedule Q of the California Corporation Franchise or Income Tax Return contains important questions related to the taxpayer's federal income tax liability. Neglecting to answer these questions completely and accurately can lead to processing delays and potential penalties. To avoid this mistake, carefully review each question and provide all required information. If unsure about an answer, consult with a tax professional or the instructions provided on the tax return.
Incorrect calculation of net income before state adjustments and failure to include all necessary additions
California Corporation Franchise or Income Tax Return requires the accurate calculation of net income before state adjustments. This figure is crucial as it forms the basis for determining the total state tax liability. A common mistake occurs when taxpayers fail to include all necessary additions to income. These additions may include items such as interest income, gains from the sale of assets, or income from certain business activities. To avoid this mistake, taxpayers should carefully review the instructions and ensure they include all relevant income and additions in their calculations.
Failure to calculate the total state adjustments correctly
State adjustments are important modifications to the federal taxable income that California requires for calculating the state tax liability. These adjustments can significantly impact the final taxable income figure. A common mistake occurs when taxpayers fail to calculate the total state adjustments correctly. This error can lead to an incorrect tax liability. To prevent this mistake, taxpayers should double-check their calculations and ensure they include all applicable state adjustments.
Miscalculation of net income for tax purposes
Calculating net income for tax purposes can be a complex process, and a common mistake occurs when taxpayers miscalculate this figure. This error can result in an incorrect tax liability or even an audit. To avoid this mistake, taxpayers should carefully review the instructions and ensure they follow the correct method for calculating net income for tax purposes. They should also double-check their calculations and consider consulting a tax professional if they are unsure.
Failure to report all sources of income and deductions correctly
The California Corporation Franchise or Income Tax Return requires taxpayers to report all sources of income and deductions. A common mistake occurs when taxpayers fail to report all income or deductions, either intentionally or unintentionally. This error can lead to penalties, interest, and even an audit. To prevent this mistake, taxpayers should ensure they report all income and deductions accurately and completely. They should also keep detailed records of all income and expenses to support their tax filings.
Incorrect calculation of taxes, credits, and total tax due
Calculating taxes, credits, and the total tax due can be a complex process, and a common mistake occurs when taxpayers make errors in these calculations. This error can lead to an incorrect tax liability or even an audit. To prevent this mistake, taxpayers should carefully review the instructions and ensure they follow the correct method for calculating taxes, credits, and the total tax due. They should also double-check their calculations and consider consulting a tax professional if they are unsure.
Failure to report all payments
One of the most significant mistakes made on the California Corporation Franchise or Income Tax Return is the failure to report all payments received by the corporation. This includes overpayments from the prior year, estimated tax payments, withholding, and the amount paid with an extension. It is crucial to ensure that all income is reported accurately to avoid potential penalties and interest charges. To avoid this mistake, review all income sources carefully and ensure that all payments are reported, even if they were previously reported on a different tax form or in a different tax year.
Incomplete or incorrect information in required schedules and forms
Another common mistake made on the California Corporation Franchise or Income Tax Return is the failure to complete or provide accurate information in required schedules and forms, such as Schedule J, Schedule F, and Schedule A. Incomplete or incorrect information can lead to errors in the calculation of taxes owed and potential penalties. To avoid this mistake, ensure that all required schedules and forms are completed accurately and in a timely manner. Review each schedule and form carefully to ensure that all necessary information is provided.
Failure to sign and date the return properly
Another mistake made on the California Corporation Franchise or Income Tax Return is the failure to sign and date the return properly by an authorized officer. The return must be signed and dated by an officer of the corporation, and their title, email address, and telephone number must be included. Failure to do so can result in the return being rejected, leading to delays in processing and potential penalties. To avoid this mistake, ensure that the return is signed and dated properly by an authorized officer before submitting it.
Neglecting to complete and attach all required schedules and forms
Another common mistake made on the California Corporation Franchise or Income Tax Return is neglecting to complete and attach all required schedules and forms. Failure to do so can result in errors in the calculation of taxes owed and potential penalties. To avoid this mistake, ensure that all required schedules and forms are completed and attached to the tax return before submitting it.

Frequently Asked Questions About Form 100


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 2 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 100.
Can I fill other forms too?
This plan is for your Form 100: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 100?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 100, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Form 100 to fill out?
Form 100 has a Form Complexity Index of 76 out of 100, in the complex tier: 425 fillable fields across 6 pages. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is the purpose of California Corporation Franchise or Income Tax Return Form 100?
Form 100, California Corporation Franchise or Income Tax Return, is used by corporations and other business entities to report their income, pay the appropriate franchise tax, and file their annual report with the California Franchise Tax Board. This form is essential for maintaining the legal status and tax compliance of a business entity in California.
What is the difference between a final return and a non-final return in the context of Form 100?
A final return is filed when a corporation is dissolving or liquidating its business and distributing its assets to shareholders. In contrast, a non-final return is filed for the regular tax year, reporting the income and taxes for the current year. Non-final returns are typically filed annually to maintain the business's active status.
What is meant by 'dissolved,' 'surrendered,' 'merged/reorganized,' and 'IRC Section 338 sale' in the context of Form 100?
1. Dissolved: A corporation is considered dissolved when it has completed the winding up of its business and has distributed its assets to its shareholders or creditors. Dissolved corporations are no longer conducting business and are not required to file annual returns or pay taxes. 2. Surrendered: A corporation may surrender its franchise tax account to the California Franchise Tax Board when it is no longer in business or has moved its principal place of business out of California. 3. Merged/Reorganized: When two corporations merge or reorganize, they combine their assets, liabilities, and ownership. The surviving corporation files Form 100 to report the transaction and pay any applicable taxes. 4. IRC Section 338 sale: An IRC Section 338 sale is a taxable reorganization under the Internal Revenue Code where a corporation sells substantially all of its assets to another corporation in exchange for stock. The selling corporation remains in existence and files Form 100 to report the transaction and pay any applicable taxes.
What is the difference between a 'wholly within CA' and a 'within and outside of CA' situation regarding income inclusion in a combined report?
A 'wholly within CA' situation refers to a combined report where all income, deductions, and taxes are sourced within California. In contrast, a 'within and outside of CA' situation involves income, deductions, and taxes sourced both within and outside of California. In the latter case, the corporation must allocate and apportion its income, deductions, and taxes among the various jurisdictions using the California Unitary Business Tax (CUBT) apportionment formula.
What is the significance of Schedule Q Questions related to unitary groups in Form 100?
Schedule Q of Form 100 is used to report information about unitary groups, which are groups of corporations or other business entities under common control. The California Franchise Tax Board uses this information to determine the appropriate tax base and apportionment factors for the combined report. The questions on Schedule Q relate to the ownership structure, intercompany transactions, and taxable income of the unitary group members.
What is the meaning of 'members listed in Schedule R-7' and how is their change reported in Form 100?
The term 'members listed in Schedule R-7' refers to members of an affiliated group, as defined in California Revenue and Taxation Code Section 25121. Schedule R-7 is used to report information about these members, including their California taxable income and apportionment factor. If there is a change in membership during the taxable year, it must be reported on Form 100, California Corporation Franchise or Income Tax Return, in the current year and in the year of the change. The change in membership should be reported on Line 11 of Form 100, and the affected members' information should be reported on Schedule R-7.
What is the purpose of Form FTB 3544 and when should it be attached to Form 100?
Form FTB 3544, California Reconciliation of Worldwide and California Income, is used to reconcile the taxpayer's federal taxable income with their California taxable income. It is required to be attached to Form 100, California Corporation Franchise or Income Tax Return, if the taxpayer has a difference between their federal taxable income and their California taxable income. Form FTB 3544 is used to calculate and report the difference, which may be due to differences in the treatment of certain items for federal and state tax purposes. The form should be completed and attached to Form 100 when the taxpayer files their annual California corporate income tax return.
What is the significance of questions related to the acquisition or transfer of California real property in Form 100?
Questions related to the acquisition or transfer of California real property in Form 100 are significant because they affect the taxpayer's California taxable income. The taxpayer is required to report the sale or exchange of California real property in the year of the sale or exchange, and may be subject to California income tax on the gain from the sale. The taxpayer may also be required to file a California Real Property Tax Return (Form 571) if they are a nonresident or part-year resident and own California real property. The taxpayer should carefully review the instructions for Form 100 and complete the applicable sections related to real property transactions.
What is the difference between state adjustments and net income before state adjustments in Form 100?
Net income before state adjustments, also referred to as net income computed in accordance with federal tax laws, is the taxpayer's total income from all sources, reduced by all allowable deductions, as determined under the Internal Revenue Code. State adjustments are items that are deductible for federal tax purposes but are not allowed as deductions for California tax purposes, or are deductible for California tax purposes but not for federal tax purposes. These adjustments are added back or subtracted from net income before state adjustments to arrive at California taxable income. The taxpayer should carefully review the instructions for Form 100 and complete Schedule A, California Adjustments to Income, to calculate their California taxable income.
What is the purpose of Schedule J in Form 100 and what types of taxes are included?
Schedule J, California Franchise Tax Base, is used to calculate the California taxable income of a corporation or other business entity. It includes several sections, each of which reports different types of income and deductions. Section A reports the taxpayer's net income before state adjustments, as computed under federal tax laws. Section B reports state adjustments, which are items that are deductible for federal tax purposes but not for California tax purposes, or are deductible for California tax purposes but not for federal tax purposes. Section C reports the taxpayer's California taxable income, which is the result of adding back or subtracting state adjustments from net income before state adjustments. Schedule J also reports the taxpayer's apportionment factor, which is used to allocate their California taxable income to the various factors used to determine their California tax liability.
What is the significance of Schedule F in Form 100 and what types of income are included?
Schedule F, titled 'Profit or Loss from Farming,' is significant in Form 100 as it allows taxpayers to report income and expenses related to farming activities. This includes income from the sale of agricultural products, livestock, and forest products, as well as expenses related to farming operations such as fertilizer, seeds, and labor costs. Farmers may also be eligible for certain deductions and exemptions specific to agricultural businesses.
What is the purpose of Schedule A in Form 100 and what types of taxes are deducted?
Schedule A, titled 'California Net Income,' is a crucial component of Form 100 as it is used to calculate the taxpayer's net income for the taxable year. This schedule includes various adjustments to the taxpayer's federal adjusted gross income (AGI), such as deductions for state and local taxes, contributions to retirement plans, and certain business expenses. The net income calculated on Schedule A is then used to determine the taxpayer's California taxable income and subsequent tax liability.
What is the difference between the California computation method and the federal computation method for net income in Form 100?
The primary difference between the California and federal computation methods for net income in Form 100 lies in the treatment of certain deductions and adjustments. While both methods start with the taxpayer's federal adjusted gross income (AGI), California allows for additional deductions and adjustments not permitted under federal tax laws. For example, California allows a deduction for certain business expenses paid with a credit card, while the federal tax code does not. Additionally, California may have different tax rates and brackets, which can impact the final net income and tax liability.
What is the purpose of Schedules L, M-1, and M-2 in Form 100 and what information do they provide?
Schedules L, M-1, and M-2 in Form 100 serve different purposes in the tax return process. Schedule L, titled 'Reconciliation of Income,' is used to reconcile the taxpayer's federal taxable income with their California taxable income. This schedule includes adjustments for items that have different treatment under federal and California tax laws, such as certain business expenses and deductions. Schedule M-1, titled 'California Share of Income,' is used to calculate the California taxpayer's share of income from partnerships, S corporations, and other pass-through entities. Schedule M-2, titled 'California Tax on Income from Sources Outside California,' is used to calculate the taxpayer's liability for income earned from sources outside of California.
What is the significance of the inventory method (LIFO, FIFO, etc.) in Form 100?
The inventory method, specifically Last-In, First-Out (LIFO) and First-In, First-Out (FIFO), is significant in Form 100 as it is used to determine the cost of goods sold (COGS) for inventory-based businesses. The choice between LIFO and FIFO can impact the taxpayer's net income and subsequent tax liability. LIFO assumes that the most recently acquired inventory is sold first, while FIFO assumes that the oldest inventory is sold first. The difference between the two methods can result in different COGS and, consequently, different net income figures. Taxpayers must choose the inventory method that best represents their business and report it accordingly on Form 100.
What is the difference between short-term and long-term capital gains and losses in Form 100?
Short-term capital gains and losses are realized from the sale or exchange of assets held for one year or less. Long-term capital gains and losses are realized from the sale or exchange of assets held for more than one year. Short-term gains are taxed at ordinary income tax rates, while long-term gains are taxed at preferential rates.
What is the purpose of Schedule D in Form 100 and what types of capital gains and losses are reported?
Schedule D is used to report the capital gains and losses from the sale or exchange of capital assets, including stocks, bonds, real estate, and other property. It is divided into several parts, each dealing with specific types of transactions, such as sales of stock at a profit or loss, sales of real property, and sales of collectibles.
What is the significance of the excess of net short-term capital gain over net long-term capital loss in Form 100?
The excess of net short-term capital gain over net long-term capital loss is reported on line 11 of Form 100. This amount is added to net short-term capital losses carried over from previous years and subtracted from net long-term capital gains carried over from previous years. The result is the net capital loss or net capital gain for the current tax year.
What is the difference between net capital gain and total lines 9 and 10 in Form 100?
Net capital gain is the total of long-term capital gain and short-term capital gain, reduced by the total of long-term capital loss and short-term capital loss. Lines 9 and 10 of Form 100 report the total long-term capital gain and total short-term capital gain, respectively. Net capital gain is calculated by subtracting the total capital losses from the total capital gains.
What is the purpose of Schedule M-2 in Form 100 and what information does it provide?
Schedule M-2 is used to calculate the alternative minimum tax (AMT) for individuals, estates, and trusts. It includes adjustments to income, subtractions for certain items, and additions for other items to arrive at the alternative minimum taxable income. This schedule is important because it ensures that certain taxpayers pay a minimum amount of tax, regardless of their ability to reduce their taxable income through deductions and credits.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 100 filled out by AI

$0 today. Cancel before Nov 2 and you pay nothing.

7 days free, then $19.99/month · Cancel anytime