
Instafill.ai
7 days free
AI form filling · 248 fields · 6 pages · done in seconds

Yes! You can use AI to fill out Form 1042-S, Foreign Person’s U.S. Income

Don't type 248 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
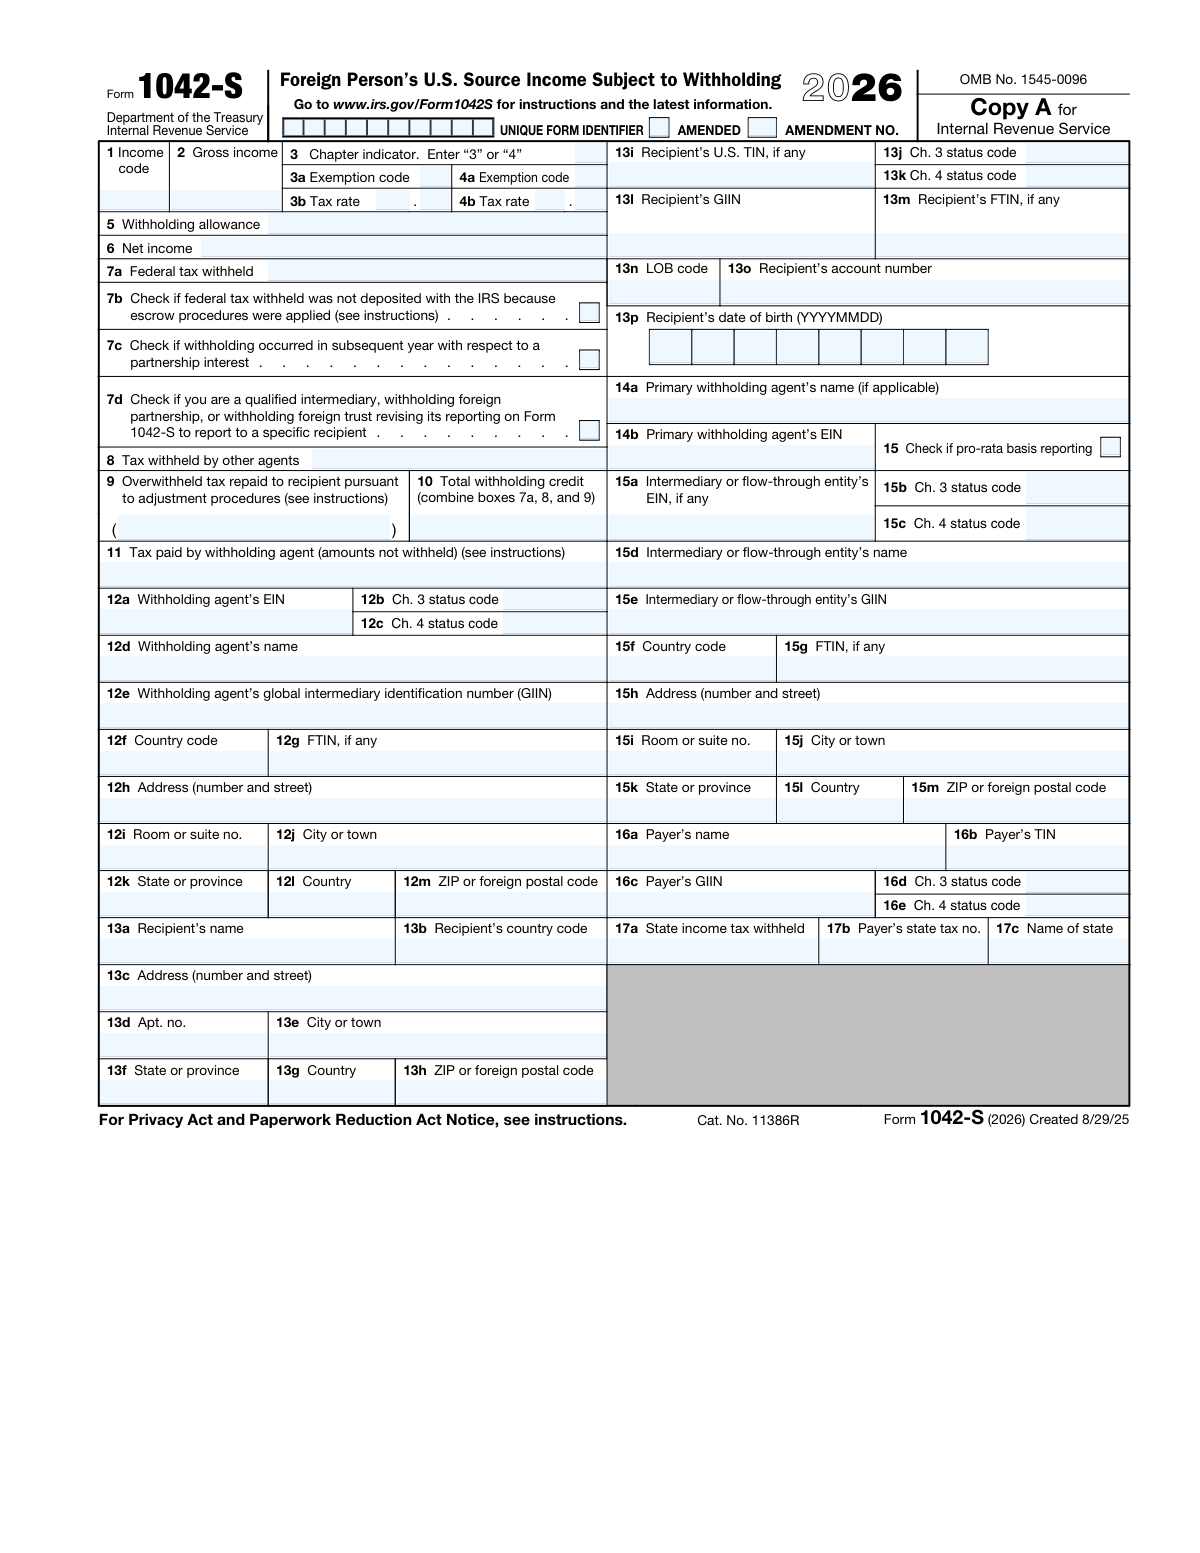
Form 1042-S, Foreign Person’s U.S. Income, page 1
Complex · 71/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 1042-S, Foreign Person’s U.S. Source Income Subject to Withholding, is used to report income paid to foreign persons that is subject to U.S. withholding tax. This form is crucial for ensuring that the correct amount of tax is withheld from payments made to non-U.S. residents.
Fillable fields248
Pages6
Sections27
Form Complexity IndexComplex, 71/100

The AI checks your answers before you download

25 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Ensures that the UNIQUE FORM IDENTIFIER is entered if applicable.

The AI ensures that the UNIQUE FORM IDENTIFIER field is populated when required. It checks for the presence of an identifier that distinguishes this form from others for tracking and processing purposes. If the form's instructions indicate that a unique identifier is necessary, the AI verifies that this field is not left blank. Additionally, it may validate the format of the identifier to ensure it conforms to any specified standards.

Confirms that the AMENDED box is checked if the form is an amended version.

The AI confirms that the 'AMENDED' checkbox is marked in cases where the form being processed is an amended version of a previously filed document. It ensures that this indication is clear and unambiguous, as it is crucial for the proper handling of the form by tax authorities. The AI also checks for consistency in the form's data, ensuring that if the form is marked as amended, all necessary sections are completed to reflect the changes made.

Verifies that the AMENDMENT NO. is entered correctly if the form is amended.

Upon detecting that the form is an amended version, the AI verifies that the AMENDMENT NO. field is filled out correctly. It checks that the amendment number is present and accurately reflects the sequence of amendments, if there have been multiple. The AI ensures that this number is consistent with any related documentation and that it follows any specific formatting rules as may be required by the form's guidelines.

Checks that the OMB No. 1545-0096 is present as it is pre-printed on the form.

The AI checks for the presence of the Office of Management and Budget (OMB) control number, which is OMB No. 1545-0096, on the form. This number is typically pre-printed on federal forms to indicate approval under the Paperwork Reduction Act. The AI ensures that this number has not been inadvertently omitted or altered during the form preparation process.

Determines which copy of the form (Copy A/B/C/D) is being filled out and used appropriately.

The AI determines which specific copy of the form (Copy A, B, C, or D) is being completed. It ensures that the correct copy is used for its intended purpose, as each copy may have a different destination or use case (e.g., one for the IRS, one for the taxpayer, etc.). The AI checks that all information is consistent across copies if multiple are required and that each is appropriately labeled and directed to the correct recipient.

Validates that all boxes from 1 to 17 are completed with accurate and relevant information.

The AI ensures that every field from Box 1 to Box 17 is filled out with the correct information. It cross-references data from other documents and databases to confirm the accuracy of the details entered. The AI also checks for logical consistency across the form to ensure that all provided information aligns with the expected values for each box. In case of missing or inconsistent data, the AI flags the specific box for review and correction.

And 19 more checks
  • Confirms the correct income code is entered in Box 1 corresponding to the type of income reported.
  • Ensures the gross income amount is entered in Box 2.
  • Verifies the correct chapter indicator ('3' or '4') is entered in Box 3.
  • Checks for the correct exemption code in Boxes 3a and 4a, if applicable.
  • Ensures the correct tax rate is entered in Boxes 3b and 4b
  • Verifies the withholding allowance entered in Box 5, if any
  • Calculates and confirms the net income after allowances in Box 6
  • Ensures the federal tax withheld is entered in Box 7a and checks Boxes 7b and 7c if applicable
  • Validates the tax withheld by other agents in Box 8 and the overwithheld tax repaid in Box 9
  • Total Withholding Credit and Tax Paid Verification
  • Withholding Agent's Details Accuracy
  • Recipient's Details Verification
  • Primary Withholding Agent's Information
  • Pro-Rata Basis Reporting and Intermediary Details
  • Validates the payer's details in Boxes 16a-16e, including name and TIN.
  • Confirms state income tax withheld and payer's state tax number in Boxes 17a-17c.
  • Ensures that the 'Explanation of Codes' section is referred to for accurate reporting of codes.
  • Verifies that Copy C is attached to any federal tax return filed and Copy D to any state tax return filed.
  • Confirms compliance with the Privacy Act and Paperwork Reduction Act Notice as per IRS instructions.

Let AI fill out your Form 1042-S

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 1042-S Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 1042-S.
  2. Enter income code and gross income.
  3. Fill in recipient and withholding agent details.
  4. Complete tax rate and exemption codes if applicable.
  5. Sign and date the form electronically.
  6. Check for accuracy and submit the form.

Common Mistakes in Completing Form 1042-S

The ones the AI is built to catch.

Neglecting to include the unique form identifier if applicable
The Foreign Person's U.S. Source Income form may require a unique identifier, such as a Form W-8BEN or W-8BEN-E number. Failing to enter this identifier correctly can lead to processing delays or potential rejection of the form. To avoid this mistake, ensure that you have the correct form type and version, and carefully follow the instructions for entering the identifier. If you are unsure about the identifier required, consult the form instructions or seek advice from a tax professional.
Overlooking the 'Amended' box if filing an amended version
If you are filing an amended version of the Foreign Person's U.S. Source Income form, it is essential to check the 'Amended' box to indicate this. Failure to do so may result in the form being processed as a new submission, potentially causing confusion and delays. To prevent this mistake, double-check the form instructions and ensure that you have completed all necessary corrections before filing, and always remember to mark the 'Amended' box if applicable.
Entering the incorrect Office of Management and Budget number
The Office of Management and Budget (OMB) number is an essential identifier for the Foreign Person's U.S. Source Income form. Incorrectly entering this number can lead to processing errors or potential rejection of the form. To avoid this mistake, ensure that you have the correct OMB number for the form type and version you are using. Double-check the number against the instructions and consult the form instructions or a tax professional if you are unsure.
Misidentifying the copy of the form being filled out
The Foreign Person's U.S. Source Income form may have multiple copies, each with different purposes and requirements. Misidentifying the copy you are filling out can lead to incorrect or incomplete information being provided. To prevent this mistake, carefully review the form instructions and ensure that you have the correct copy for your situation. If you are unsure, consult a tax professional or the form instructions for clarification.
Leaving boxes 1-17 incomplete or with incorrect information
Boxes 1-17 on the Foreign Person's U.S. Source Income form are used to report various types of income and tax withholding. Failing to complete these boxes correctly or leaving them blank can result in incorrect tax reporting and potential penalties. To avoid this mistake, carefully review the form instructions and ensure that you have entered all required information accurately. If you are unsure about how to complete any of the boxes, consult a tax professional or the form instructions for guidance.
Incorrectly entering income codes in Box 1
This form requires specific income codes to be entered in Box 1 to indicate the type of U.S. source income. Failure to enter the correct codes may result in incorrect reporting and potential IRS scrutiny. To avoid this mistake, ensure you have a clear understanding of the income codes and double-check your entries against the instructions provided on the form and in the instructions booklet.
Failing to enter the gross income amount in Box 2
Box 2 requires the total gross income to be reported, which is the amount before any deductions or exemptions are applied. Neglecting to enter this amount may result in underreporting of income and potential IRS penalties. To prevent this mistake, carefully review the instructions and ensure all income is accounted for and reported in the correct boxes.
Misidentifying the chapter indicator in Box 3
The chapter indicator in Box 3 is used to identify the specific tax treaty article that applies to the income reported. Misidentifying this indicator may result in incorrect taxation or potential penalties. To avoid this mistake, carefully review the instructions and consult the relevant tax treaty articles to determine the correct chapter indicator.
Entering incorrect exemption codes in Boxes 3a and 4a
Exemption codes in Boxes 3a and 4a are used to indicate the specific tax treaty article that applies to the exemption. Entering the incorrect codes may result in incorrect taxation or potential penalties. To prevent this mistake, carefully review the instructions and consult the relevant tax treaty articles to determine the correct exemption codes.
Entering incorrect tax rates in Boxes 3b and 4b
Boxes 3b and 4b require the correct tax rates to be entered based on the income codes and exemption codes used. Entering incorrect tax rates may result in incorrect taxation or potential penalties. To prevent this mistake, carefully review the instructions and consult the relevant tax treaty articles to determine the correct tax rates.
Neglecting to Enter Withholding Allowances in Box 5
When completing the Foreign Person's U.S. Source Income form, it is essential to accurately report any withholding allowances in Box 5. Withholding allowances reduce the amount of income subject to tax. Failing to enter these allowances can result in an overpayment of taxes or potential penalties. To avoid this mistake, ensure you have a clear understanding of the withholding allowances applicable to your situation and enter them correctly in the designated box.
Entering Incorrect Net Income after Allowances in Box 6
Another common mistake is entering incorrect net income after allowances in Box 6. This box should reflect the total income subject to tax after deducting withholding allowances. Incorrectly reporting net income can lead to inaccurate tax calculations and potential penalties. To prevent this error, double-check your calculations and ensure the net income reported in Box 6 matches the total income reported on the form.
Failing to Check the Appropriate Boxes in Box 7 for Federal Tax Withheld
Box 7 on the Foreign Person's U.S. Source Income form requires taxpayers to indicate the federal tax withheld. Failing to check the appropriate boxes can result in incorrect tax calculations and potential penalties. To avoid this mistake, carefully review the instructions and ensure you select the correct box based on the amount of federal tax withheld.
Failing to Report Withholding by Other Agents in Box 8
It is crucial to report any withholding by other agents in Box 8. This includes withholding by U.S. payors, such as employers or pension providers. Failing to report this information can result in an incomplete tax return and potential penalties. To prevent this mistake, gather all necessary documentation and report any withholding by other agents as required.
Failing to Report Overwithheld Tax Repaid to the Recipient in Box 9
Lastly, it is essential to report any overwithheld tax repaid to the recipient in Box 9. This box applies when a taxpayer receives a refund of excess withholding. Failing to report this information can result in incorrect tax calculations and potential penalties. To avoid this mistake, ensure you accurately report any overwithheld tax repaid to the recipient in the designated box.
Neglecting to Enter Total Withholding Credit in Box 10
Failure to enter the total withholding credit in Box 10 can lead to underreporting of taxable income. This may result in potential penalties and interest charges. To avoid this mistake, ensure that the total amount of withholding credits claimed is accurately entered in this box. Double-check the figures to ensure consistency with the information reported in other relevant sections of the form.
Omitting Tax Paid by the Withholding Agent in Box 11
Leaving Box 11 blank can result in an incomplete submission of the form. The tax paid by the withholding agent is an essential piece of information required for accurate tax reporting. To prevent this error, make sure to enter the total tax paid by the withholding agent in this box. Verify the figure against the records provided by the withholding agent to ensure accuracy.
Incorrectly Entering Recipient's Details in Boxes 13a-13l
Misrecording the recipient's details, such as name, address, or TIN, in Boxes 13a-13l can lead to significant complications during tax processing. Incorrect information may result in delayed or incorrect tax refunds or even penalties. To prevent this mistake, double-check all the information entered in these boxes against the recipient's original documentation. Ensure that all fields are completed accurately and consistently.
Failing to Enter Primary Withholding Agent's Name and EIN in Boxes 14a and 14b
Neglecting to enter the primary withholding agent's name and EIN in Boxes 14a and 14b can cause processing delays and potential penalties. This information is crucial for proper tax reporting and withholding credit allocation. To avoid this mistake, ensure that the primary withholding agent's name and EIN are entered correctly and completely in these boxes. Verify the information against the withholding agent's documentation to ensure accuracy.
Overlooking the Applicability of Pro-rata Basis Reporting in Box 15
Failing to check if pro-rata basis reporting is applicable in Box 15 can result in incorrect tax reporting. Pro-rata basis reporting may be required for certain types of income, and failure to apply it can lead to underreporting or overreporting of taxable income. To prevent this mistake, carefully review the instructions provided on the form and determine if pro-rata basis reporting is applicable to the income reported. If so, ensure that the appropriate percentage is entered in Box 15 to accurately reflect the taxable income.
Neglecting to Provide Intermediary or Flow-Through Entity Details in Boxes 15a-15i
When completing the Foreign Person's U.S. Source Income form, it is essential to provide accurate details of any intermediary or flow-through entities involved in the income generation. Failure to do so can lead to processing delays or potential rejections of the tax return. To avoid this mistake, ensure that all required information, such as the name, address, and taxpayer identification number (TIN) of the intermediary or flow-through entity, is entered correctly in the designated boxes. It is also crucial to double-check that all provided information is complete and up-to-date.
Incorrectly Entering Payer Details in Boxes 16a-16e
Another common mistake on the Foreign Person's U.S. Source Income form is entering incorrect payer details in Boxes 16a-16e. This can include providing an incorrect name, address, or TIN for the payer. Inaccurate payer information can lead to processing delays or potential rejections of the tax return. To prevent this mistake, carefully review the payer's details and ensure that they are entered correctly in the designated boxes. If there is any uncertainty, contact the payer to confirm the information or consult with a tax professional for guidance.
Omitting State Income Tax Withheld, Payer's State Tax Number, and Name of the State in Boxes 17a-17c
Failing to enter state income tax withheld, payer's state tax number, and the name of the state in Boxes 17a-17c is a common mistake on the Foreign Person's U.S. Source Income form. This information is crucial for the accurate processing of the tax return. To avoid this mistake, ensure that all required state-related information is gathered and entered correctly in the designated boxes. Double-check that the state tax number and name are consistent with the payer's details and that the state income tax withheld is accurately calculated and reported.
Neglecting to Attach Copies C and D to the Appropriate Tax Returns
Another mistake on the Foreign Person's U.S. Source Income form is failing to attach copies C and D to the appropriate tax returns. These copies are essential for the verification of the income reported and can lead to processing delays or potential rejections of the tax return if not included. To prevent this mistake, carefully review the instructions for attaching copies C and D and ensure that they are properly attached to the appropriate tax returns. If there is any uncertainty, consult with a tax professional for guidance.
Ignoring the Instructions for the 'Explanation of Codes' Section
Lastly, ignoring the instructions for the 'Explanation of Codes' section is a common mistake on the Foreign Person's U.S. Source Income form. This section is crucial for providing context and clarity to the income reported on the form. Failure to complete this section accurately can lead to processing delays or potential rejections of the tax return. To avoid this mistake, carefully review the instructions for the 'Explanation of Codes' section and ensure that all required information is entered accurately and completely. If there is any uncertainty, consult with a tax professional for guidance.
Neglecting to carefully review IRS instructions for Form 1042-S
The IRS instructions for Form 1042-S provide essential guidance on how to complete the form accurately. Failing to review these instructions can lead to mistakes in reporting U.S. source income for a foreign person. For instance, a foreign person might overlook important details regarding the types of income that need to be reported or the necessary withholding certificates to be submitted. To avoid this mistake, it is recommended to read the instructions thoroughly before filling out the form. Additionally, keeping track of any updates or changes to the instructions for future tax years is crucial to ensure ongoing compliance.
Incorrectly reporting income type or amount
Another potential mistake when completing Form 1042-S is reporting the incorrect type of income or its amount. This error can occur if a foreign person fails to understand the specific income categories listed on the form or miscalculates the income amount. To prevent this mistake, it is essential to double-check the income reported against the relevant documentation, such as bank statements or other financial records. Additionally, consulting a tax professional or the IRS instructions can help clarify any uncertainties regarding income reporting.
Overlooking the requirement for a withholding certificate
A foreign person may overlook the need to submit a withholding certificate when completing Form 1042-S. This certificate, such as Form W-8BEN or W-8BEN-E, is necessary to establish the foreign person's tax status and the appropriate withholding rate. Failing to provide this certificate can result in incorrect withholding or potential penalties. To avoid this mistake, it is recommended to carefully review the instructions for Form 1042-S and ensure that the appropriate withholding certificate is obtained and submitted with the form.
Incomplete or inaccurate personal information
Providing incomplete or inaccurate personal information on Form 1042-S can lead to processing delays or incorrect reporting. A foreign person might overlook providing essential details, such as their correct name, address, or taxpayer identification number. To prevent this mistake, it is crucial to double-check all personal information provided on the form against relevant documentation and ensure its accuracy. Additionally, maintaining updated personal information and promptly notifying the IRS of any changes can help ensure ongoing compliance.

Frequently Asked Questions About Form 1042-S


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 1 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 1042-S.
Can I fill other forms too?
This plan is for your Form 1042-S: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 1042-S?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 1042-S, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Form 1042-S to fill out?
Form 1042-S has a Form Complexity Index of 71 out of 100, in the complex tier: 248 fillable fields across 6 pages. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is the purpose of Form 1042-S for a Foreign Person's U.S. Source Income?
Form 1042-S is used to report U.S. source income subject to withholding for foreign persons, including individuals, estates, trusts, and foreign corporations.
What information is required on Form 1042-S for a Foreign Person's U.S. Source Income?
Form 1042-S requires information about the income earned, the withholding agent, the recipient, and the tax withheld. It also includes codes for income type, exemption status, and chapter status for both the withholding agent and the recipient.
Who is required to file Form 1042-S for a Foreign Person's U.S. Source Income?
U.S. persons, including withholding agents, are required to file Form 1042-S for any payment of U.S. source income to a foreign person. The form must be filed annually and must be accompanied by the appropriate instructions and supporting documentation.
What is the difference between Chapter 3 and Chapter 4 status codes on Form 1042-S for a Foreign Person's U.S. Source Income?
Chapter 3 status codes apply to U.S. branches, withholding foreign partnerships, and publicly traded partnerships, while Chapter 4 status codes apply to foreign financial institutions (FFIs) and foreign flowing entities (FFEs).
What is the difference between a withholding agent and a paying agent on Form 1042-S for a Foreign Person's U.S. Source Income?
A withholding agent is responsible for withholding and paying over the tax to the IRS on behalf of the recipient, while a paying agent is the person or entity making the payment to the recipient.
What is the difference between a gross payment and a net payment?
A gross payment is the total amount paid to a foreign person before any deductions, such as taxes or fees. A net payment, on the other hand, is the amount paid after these deductions have been made.
What is the difference between a tax treaty exemption and a portfolio interest exemption?
A tax treaty exemption is a reduction or elimination of withholding tax based on a tax treaty between the United States and the recipient's country. A portfolio interest exemption, on the other hand, is a reduction or elimination of withholding tax on certain types of income derived from U.S. securities.
What is the difference between a participating FFI and a registered deemed-compliant FFI?
A participating FFI is a foreign financial institution that has entered into an agreement with the IRS to report and withhold taxes on U.S. source income paid to non-U.S. persons. A registered deemed-compliant FFI, on the other hand, is a foreign financial institution that has registered with the IRS to be treated as compliant with FATCA.
What is the difference between a recalcitrant account and a nonconsenting account?
A recalcitrant account is a financial account held by a foreign financial institution (FFI) or foreign flowing entity (FFE) that has not provided the required information to the IRS. A nonconsenting account, on the other hand, is a financial account held by a foreign person that has not provided a U.S. taxpayer identification number (TIN) or a foreign tax identification number (ITIN) to the withholding agent.
What is the difference between a passive NFFE and an active NFFE?
A passive NFFE is a foreign person that derives income primarily from investments, while an active NFFE is a foreign person that derives income from an active trade or business.
What is the difference between a qualified intermediary (QI) and a qualified securities lender (QSL)?
A Qualified Intermediary (QI) is a foreign financial institution that has entered into an agreement with the Internal Revenue Service (IRS) to facilitate the flow of funds between parties without U.S. withholding. QIs help ensure that the withholding tax obligations are met by the parties involved in the transaction. A Qualified Securities Lender (QSL) is a foreign financial institution that has entered into an agreement with the IRS to act as a securities lender and provide certain withholding services. QSLs help ensure that the withholding tax obligations are met when securities are borrowed and lent between foreign persons.
What is the difference between a withholding rate pool and a participating agent pool?
A Withholding Rate Pool is a group of payments made by a withholding agent to one or more recipients that have the same withholding rate. This means that the same rate of withholding tax applies to all payments in the pool. A Participating Agent Pool is a group of payments made by a participating agent to one or more recipients that have the same participating agent. Participating agents are entities that have been authorized by the IRS to act on behalf of the withholding agent to collect and remit withholding taxes.
What is the difference between a low value account and a high value account?
A Low Value Account is a financial account held by a Foreign Financial Institution (FFI) or Foreign Flow Entity (FFE) that has a balance below a certain threshold. The threshold amount varies depending on the type of account and the applicable tax treaty. A High Value Account is a financial account held by a Foreign Financial Institution (FFI) or Foreign Flow Entity (FFE) that has a balance above a certain threshold. The threshold amount for high value accounts is typically higher than that for low value accounts.
What is the difference between a passive NFFE reported by an FFI and a passive NFFE identified by the IRS?
A Passive NFFE reported by an FFI is a foreign person identified by the FFI as a passive NFFE based on the information provided by the foreign person. The FFI is required to report this information to the IRS. A Passive NFFE identified by the IRS is a foreign person identified by the IRS based on its own analysis of the information available to it. The IRS may use various sources of information to identify passive NFFEs, including information reported by other FFIs and information from public sources.
What is the difference between a nonreporting IGA FFI and a direct reporting NFFE?
A Nonreporting IGA FFI is a foreign financial institution (FFI) that has entered into an intergovernmental agreement (IGA) with the IRS to report and withhold taxes on U.S. source income paid to non-U.S. persons, but does not directly report the information to the IRS. Instead, the FFI reports the information to its local tax authority, which then shares the information with the IRS. A Direct Reporting NFFE is a foreign financial institution (FFI) that reports and withholds taxes on U.S. source income paid to non-U.S. persons directly to the IRS. Direct reporting NFFEs are typically located in jurisdictions that have an IGA in place but do not have a local tax authority that can facilitate the reporting process.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 1042-S filled out by AI

$0 today. Cancel before Nov 1 and you pay nothing.

7 days free, then $19.99/month · Cancel anytime