
Instafill.ai
7 days free

Yes! You can use AI to fill out Form 2438, Undistributed Capital Gains Tax Return

Don't type this form by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
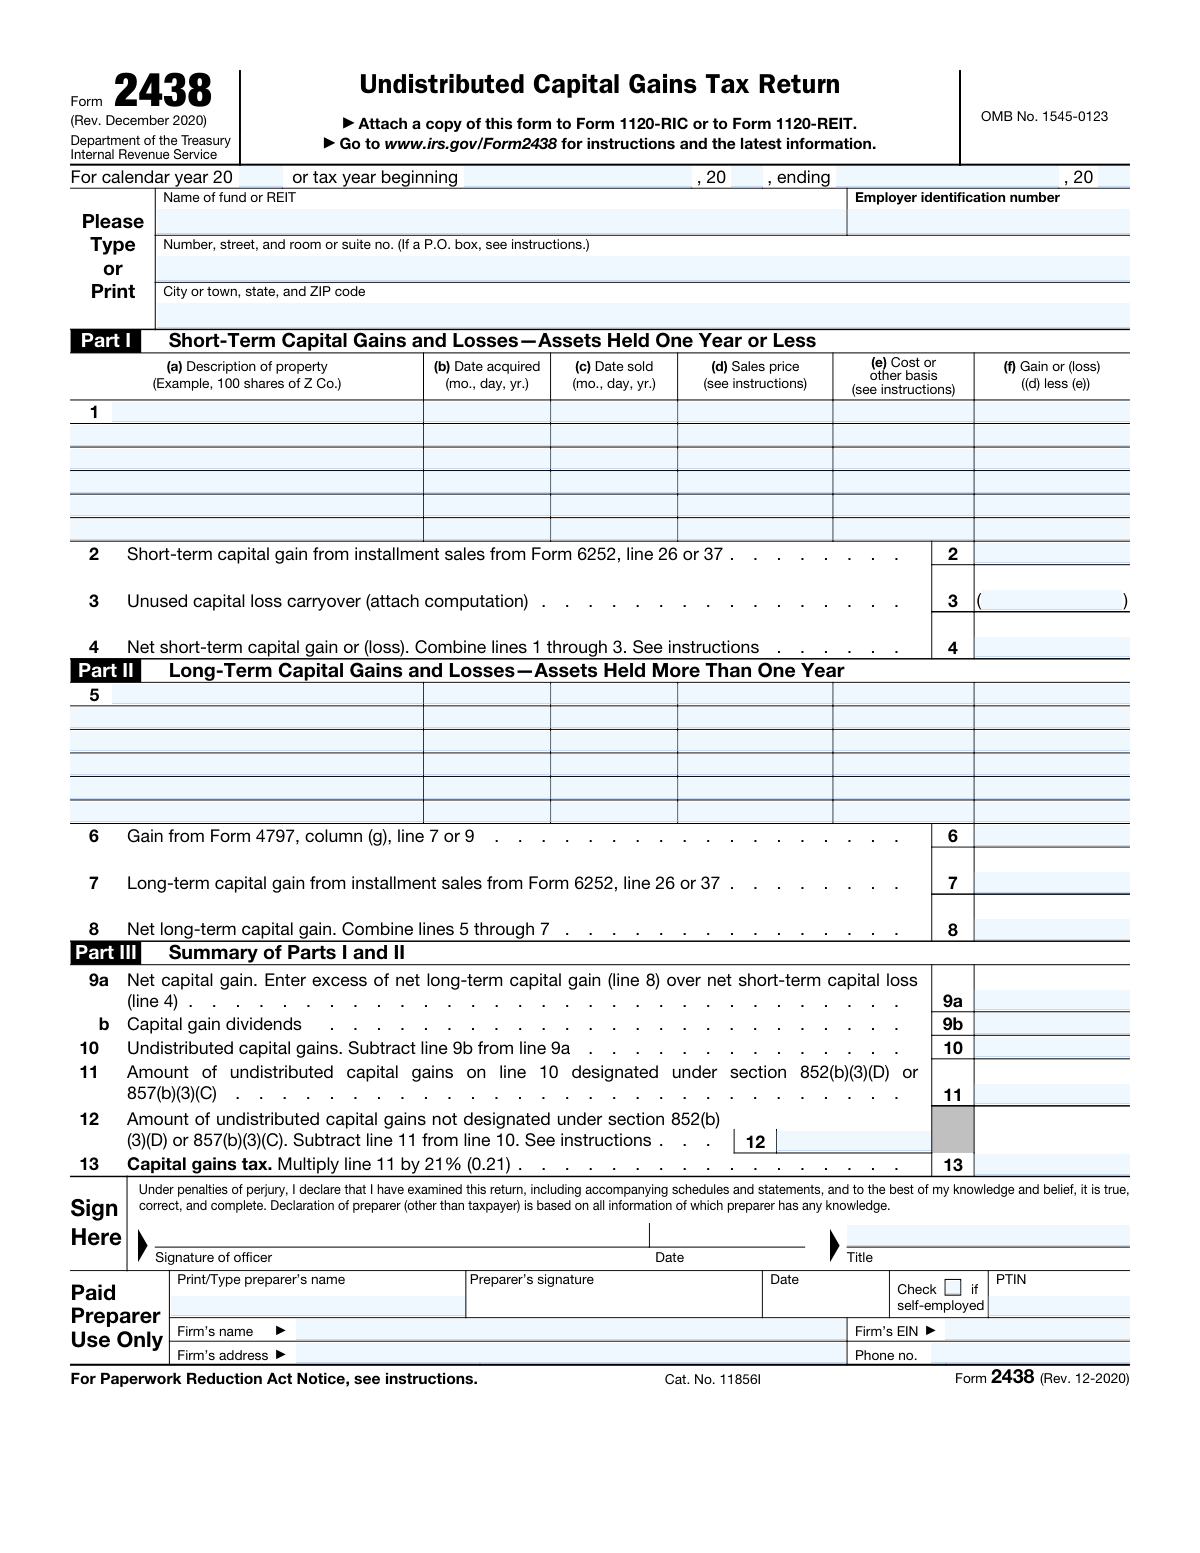
Form 2438, Undistributed Capital Gains Tax Return, page 1

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 2438, Undistributed Capital Gains Tax Return, is used by regulated investment companies (RICs) and real estate investment trusts (REITs) to report undistributed capital gains. This form is important for calculating the tax owed on these gains and ensuring compliance with IRS regulations.

The AI checks your answers before you download

15 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Property Details Completeness

Ensures that for each property listed in Part I, all necessary details are thoroughly checked for completeness. This includes verifying that a description of the property is provided, the date on which the property was acquired is accurately recorded, the date on which the property was sold is clearly stated, the sales price is correctly entered, the cost or other basis is duly noted, and the gain or loss is calculated in accordance with the relevant tax regulations.

Short-term Capital Gain from Installment Sales

Verifies that any short-term capital gain resulting from installment sales is correctly reported. This involves cross-referencing the amounts reported on Form 6252, specifically lines 26 or 37, and ensuring that these figures are accurately reflected in Part I of the Undistributed Capital Gains Tax Return. The check includes a detailed review of the installment sale information to confirm that the short-term capital gain has been computed and reported in compliance with tax laws.

Capital Loss Carryover Inclusion

Confirms the inclusion of any unused capital loss carryover in Part I of the tax return. This validation check involves ensuring that the taxpayer has attached the required computation for the capital loss carryover and that the amount included in the tax return is accurate and substantiated. The check is crucial for maintaining the integrity of the tax return and for ensuring that the taxpayer is utilizing capital loss carryovers in accordance with tax code provisions.

Net Short-term Capital Gain or Loss Calculation

Calculates and verifies the net short-term capital gain or loss by combining the figures reported on lines 1 through 3 in Part I. This check involves a meticulous review of the arithmetic operations used to arrive at the net figure, ensuring that all gains and losses have been accounted for and that the final amount is mathematically correct. The accuracy of this calculation is essential for the correct determination of the taxpayer's tax liability.

Form 4797 Gain Entry

Checks for the correct entry of any gain reported from Form 4797, specifically from column (g), lines 7 or 9, into Part II of the Undistributed Capital Gains Tax Return. This validation ensures that gains from the sale of business property, as reported on Form 4797, are accurately transferred and reflected in the capital gains tax return. The check is critical for the proper reporting of gains and for the accurate calculation of the tax due.

Includes long-term capital gain from installment sales from Form 6252, line 26 or 37 in Part II.

The validation process ensures that the long-term capital gains from installment sales are correctly included from Form 6252, line 26 or 37, as applicable. It verifies that the figures entered in Part II of the Undistributed Capital Gains Tax Return are accurate and correspond to the reported amounts on Form 6252. This check is crucial for maintaining the integrity of the tax return by ensuring that capital gains are not underreported or overreported. The AI cross-references the data to prevent any discrepancies that may arise from manual entry errors.

And 9 more checks
  • Calculates the net long-term capital gain by combining lines 5 through 7 in Part II.
  • Determines the net capital gain in Part III by subtracting the net short-term capital loss from the net long-term capital gain.
  • Ensures accurate entry of capital gain dividends in Part III.
  • Subtracts line 9b from line 9a to determine undistributed capital gains in Part III.
  • Specifies the amount of undistributed capital gains designated under section 852(b)(3)(D) or 857(b)(3)(C) in Part III
  • Subtracts line 11 from line 10 to find the amount of undistributed capital gains not designated under the specified sections in Part III
  • Multiplies line 11 by 21% to calculate the capital gains tax in Part III
  • Confirms that the form is signed and dated by an authorized officer of the fund or REIT
  • Checks that the paid preparer, if applicable, has signed and filled in their information in the designated area

Let AI fill out your Form 2438

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 2438 Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 2438.
  2. Enter the name of the fund or REIT.
  3. Provide the employer identification number.
  4. Fill in the address details accurately.
  5. Complete the capital gains and losses sections.
  6. Sign and date the form electronically.
  7. Check for accuracy and submit the form.

Common Mistakes in Completing Form 2438

The ones the AI is built to catch.

Unclear or inaccurate property descriptions in Part I and Part II
Failure to provide a clear and concise description of each property in Part I and Part II of the Undistributed Capital Gains Tax Return can lead to confusion and potential errors. It is essential to include the legal description, property address, and any other relevant details to ensure accurate reporting of capital gains or losses. To avoid this mistake, take the time to double-check the information provided for each property and make any necessary corrections before submitting the form.
Incorrect or incomplete dates for acquisition and sale of properties
Entering incorrect or incomplete dates for the acquisition and sale of properties can result in significant errors when calculating capital gains or losses. It is crucial to ensure that the dates are accurate and complete, as they are used to determine the holding period and the tax treatment of the gain or loss. To avoid this mistake, double-check the dates provided for each property and make any necessary corrections before submitting the form.
Incorrect calculation of gains or losses
Calculating gains or losses incorrectly by not subtracting the cost/basis from the sales price is a common mistake on the Undistributed Capital Gains Tax Return. This error can result in significant discrepancies in the reported capital gains or losses. To avoid this mistake, carefully review the calculations for each property and ensure that the cost/basis is subtracted from the sales price before reporting the gain or loss.
Neglecting to include short-term capital gains from installment sales or long-term capital gains from installment sales in the respective parts
Failing to include short-term capital gains from installment sales or long-term capital gains from installment sales in the respective parts of the Undistributed Capital Gains Tax Return can result in underreporting of income and potential penalties. It is essential to ensure that all capital gains, regardless of their holding period, are reported accurately. To avoid this mistake, carefully review the instructions for reporting installment sales and ensure that all gains are reported in the correct section of the form.
Forgetting to include any unused capital loss carryover
Failing to include any unused capital loss carryover on the Undistributed Capital Gains Tax Return can result in missed opportunities to offset capital gains and reduce tax liability. It is essential to ensure that all capital losses, including any carryover amounts, are reported accurately. To avoid this mistake, carefully review the instructions for reporting capital losses and ensure that all losses, including any carryover amounts, are reported in the correct section of the form.
Incorrectly combining lines in Part I and Part II
When filling out the Undistributed Capital Gains Tax Return (Form 1120-RIC or Form 1120-REIT), a common mistake occurs when taxpayers incorrectly combine lines in Part I and Part II. This error can lead to an incorrect net capital gain or loss. To avoid this mistake, ensure that each line is filled out correctly and that all gains and losses are properly categorized. Double-check the totals in each section to ensure they match the totals from the underlying capital gain and loss statements. Additionally, make sure to follow the instructions carefully regarding the order in which to fill out the lines.
Omitting capital gain dividends in Part III
Another common mistake is failing to enter capital gain dividends in Part III of the form. Capital gain dividends are taxed differently than regular dividends and must be reported separately. To avoid this mistake, carefully review the instructions for Part III and ensure that all capital gain dividends are properly reported. This may require obtaining a Form 1099-DIV or other relevant documentation from the payer. Properly reporting capital gain dividends will ensure that the correct tax is paid and that the taxpayer is in compliance with IRS regulations.
Incorrectly specifying undistributed capital gains
Taxpayers may also make the mistake of not specifying the correct amount of undistributed capital gains designated under sections 852(b)(3)(D) or 857(b)(3)(C). These sections refer to certain types of capital gains that are not distributed to shareholders but are instead retained by the RIC or REIT. To avoid this mistake, carefully review the instructions for Part IV and ensure that the correct amounts are reported. This may require consulting the RIC or REIT's tax return or other relevant documentation. Properly reporting undistributed capital gains will ensure that the taxpayer is in compliance with IRS regulations and that the correct tax is paid.
Late filing or incorrect mailing of the form
A common mistake is failing to file the form by the 30th day after the end of the RIC's or REIT's tax year or not sending the original form to the Department of the Treasury and attaching a copy to Form 1120-RIC or Form 1120-REIT. To avoid this mistake, ensure that the form is filed and mailed in a timely manner. The instructions for the form provide the due date for filing and the mailing address for the Department of the Treasury. Properly filing and mailing the form will ensure that the taxpayer is in compliance with IRS regulations and that any potential penalties for late filing or failure to file can be avoided.
Failure to Deposit Tax Due on Time
One of the most significant mistakes made when filing the Undistributed Capital Gains Tax Return is neglecting to deposit any tax due by the 30th day after the end of the tax year. This delay can result in penalties and interest charges, increasing the overall tax liability. To avoid this mistake, it is essential to calculate the tax due accurately and make the deposit promptly to avoid any potential penalties and interest charges.
Neglecting to Sign and Date the Form
Another common mistake is failing to sign and date the form by an authorized officer of the fund or REIT. The signature and date are crucial to the validity of the return. Without proper authorization, the IRS may not process the return, causing delays and potential penalties. To prevent this mistake, ensure that the authorized officer signs and dates the form before submitting it to the IRS.
Inadequate Recordkeeping
Failing to maintain proper recordkeeping related to the form and its instructions is another common mistake. Proper recordkeeping is essential to accurately complete the form and to provide supporting documentation if required by the IRS. Inadequate recordkeeping can lead to errors, delays, and potential penalties. To prevent this mistake, maintain detailed records of all transactions related to the form and keep them in a secure and organized manner.

Frequently Asked Questions About Form 2438


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 1 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 2438.
Can I fill other forms too?
This plan is for your Form 2438: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 2438?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 2438, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
What is the purpose of Form 2438 for Undistributed Capital Gains Tax Return?
Form 2438, also known as the Undistributed Filters for Capital Gains Tax, is used to report capital gains and losses that are not distributed to shareholders or partners. This form is required when a corporation or partnership has a capital gain that is not currently distributed to its owners. The form is used to calculate and report the undistributed capital gains tax to the IRS.
Who is required to file Form 2438?
Form 2438 is required to be filed by corporations and partnerships that have undistributed capital gains. This includes corporations that have sold assets for a capital gain and have not distributed the gain to their shareholders, and partnerships that have reported capital gains on their tax return but have not distributed the gains to their partners. The form must be filed with the IRS and any applicable state taxing authority.
What information is required to be reported in Part I of Form 2438 for Short-Term Capital Gains and Losses?
Part I of Form 2438 is used to report short-term capital gains and losses. Short-term gains and losses are realized on the sale of assets held for one year or less. The information required to be reported includes the description of the property sold, the date of sale, the sale price, the cost basis, and the gain or loss. It is important to note that the total of short-term capital gains and losses must be reported on Schedule D (Form 1040) for individuals or on Form 1120 for corporations.
What information is required to be reported in Part II of Form 2438 for Long-Term Capital Gains and Losses?
Part II of Form 2438 is used to report long-term capital gains and losses. Long-term gains and losses are realized on the sale of assets held for more than one year. The information required to be reported includes the description of the property sold, the date of sale, the sale price, the cost basis, and the gain or loss. It is important to note that the total of long-term capital gains and losses is netted to determine the net long-term capital gain or loss, which is reported on Schedule D (Form 1040) for individuals or on Form 1120 for corporations.
How is the net capital gain calculated in Part III of Form 2438?
Part III of Form 2438 is used to calculate the net capital gain or loss. This is done by netting the total long-term capital gains against the total long-term capital losses. The result is the net long-term capital gain or loss. If there is a net long-term capital loss, it can be used to offset capital gains in other years or can be deducted up to $3,000 per year against ordinary income. Any remaining loss can be carried forward to future years.
What is the deadline for filing Form 2438?
Form 2438, also known as the Undistributed Capital Gains Tax Return, is typically due on the same day as the taxpayer's income tax return for the year. For individuals, this means April 15th of the following year, with extensions available until October 15th. For corporations, the due date is the 15th day of the 4th month after the end of the tax year.
Where should Form 2438 be filed?
Form 2438 should be filed with the Internal Revenue Service (IRS) along with the taxpayer's income tax return. If filing electronically, the form and payment can be submitted through the Electronic Federal Tax Payment System (EFTPS) or other approved electronic filing methods. If filing a paper return, the form should be mailed to the address indicated on the form instructions.
Who should sign Form 2438?
Form 2438 must be signed by the person responsible for the undistributed capital gains. This is typically the taxpayer or the taxpayer's representative. If a corporation is filing, the form must be signed by an officer or an authorized representative.
What are the penalties for late filing and payment of tax on Form 2438?
Late filing of Form 2438 can result in a penalty of up to 5% of the tax due per month, with a maximum penalty of 25%. Late payment of the tax can result in a penalty of 0.5% of the tax due per month, with a maximum penalty of 25%. These penalties can be waived or reduced under certain circumstances, such as reasonable cause or first-time filer status.
What is the Electronic Deposit Requirement for federal tax deposits?
For taxpayers with an average annual tax liability of $50,000 or more, the IRS requires electronic federal tax deposits (EFTPS) for Form 2438 payments. This requirement applies to both individual and corporate taxpayers. Smaller taxpayers may still file and pay electronically, but are not required to do so.
What is the Same-day wire payment option for making deposits on time in Form 2438?
The Same-day wire payment option is a service that allows taxpayers to make deposits to the IRS on the same day they file their electronic return. This can be useful for taxpayers who want to ensure their payment is received by the IRS in a timely manner to avoid penalties or interest charges. To use this option, taxpayers must file their return and make the payment through an Electronic Funds Withdrawal (EFW) or Electronic Federal Tax Payment System (EFTPS). The payment must be made by 8:00 p.m. Eastern Time on the day of filing. Please note that there may be additional fees for using this service.
What is the difference between gross sales price and net sales price in Form 2438?
Gross sales price refers to the total amount of consideration received by the taxpayer for the sale of capital assets, including any commissions or fees paid to brokers. Net sales price, on the other hand, is the gross sales price reduced by any allowable deductions, such as sales taxes, transfer taxes, and certain closing costs. The net sales price is used to calculate the taxable gain or loss on the sale of the capital asset. Form 2438 requires taxpayers to report both the gross sales price and the net sales price for each sale or exchange of a capital asset.
How is the cost or other basis calculated in Form 2438?
The cost or other basis of a capital asset is the original purchase price or other cost basis, such as transfer costs or improvement costs, of the asset. This amount is used to determine the gain or loss on the sale or exchange of the asset. Form 2438 requires taxpayers to report the cost or other basis for each capital asset sold or exchanged during the tax year. Taxpayers should keep accurate records of their purchase prices and other costs related to the acquisition of capital assets to ensure they can accurately report the cost basis on their tax return.
What should be reported in line 4 of Form 2438?
Line 4 of Form 2438 is for reporting the total gain or loss from the sale or exchange of capital assets that are not subject to Section 1250 or 1252. This includes gains or losses from the sale of collectibles, partnership interests, and other types of property that do not qualify for the more favorable capital gains rates under those sections. Taxpayers should report the total gain or loss from all such sales or exchanges during the tax year, including any losses that can be used to offset gains or other income.
What should be reported in line 12 of Form 2438?
Line 12 of Form 2438 is for reporting the total net short-term capital gain or loss for the tax year. Short-term capital gains are gains from the sale or exchange of capital assets that are held for one year or less. Net short-term capital gain is the total of all short-term capital gains, reduced by any short-term capital losses. Net short-term capital losses can be used to offset other income, up to a limit of $3,000 per year, or carried forward to future years.
What is the tax due and when should it be deposited?
The tax due on Form 2438, Undistributed Capital Gains Tax Return, is the tax on the capital gains that have not been distributed to the taxpayer. The tax payment is typically made with the filing of the form. The due date for filing and paying the tax depends on the taxpayer's tax year. For most taxpayers, the due date is April 15, but it may be later if this date falls on a weekend or holiday. Extensions to file and pay may be available. It is important to note that the tax payment is separate from any estimated tax payments that may be required throughout the year.
What is the Paperwork Reduction Act Notice and its implications?
The Paperwork Reduction Act (PRA) Notice is a statement included in tax forms that explains the time and effort required to complete and file the form. The PRA Notice for Form 2438 informs taxpayers that the time required to complete and file the form is estimated to be approximately 1 hour and 30 minutes. The PRA Notice also provides information about where to send the form and any associated penalties for late filing or non-filing. It is important for taxpayers to understand the implications of the PRA Notice and allow sufficient time to complete and file the form to avoid any potential penalties.
How long should taxpayers retain the records related to Form 2438?
Taxpayers should retain the records related to Form 2438 for a period of at least 3 years from the due date of the return or 2 years from the date the tax was paid, whichever is later. This is in accordance with the IRS record retention guidelines. It is important for taxpayers to maintain accurate records to support their tax filings and to be able to provide this information to the IRS if requested.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 2438 filled out by AI

$0 today. Cancel before Nov 1 and you pay nothing.

7 days free, then $19.99/month · Cancel anytime