
Instafill.ai
7 days free
AI form filling · 33 fields · 1 page · done in seconds

Yes! You can use AI to fill out Form 8613, Return of Excise Tax

Don't type 33 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
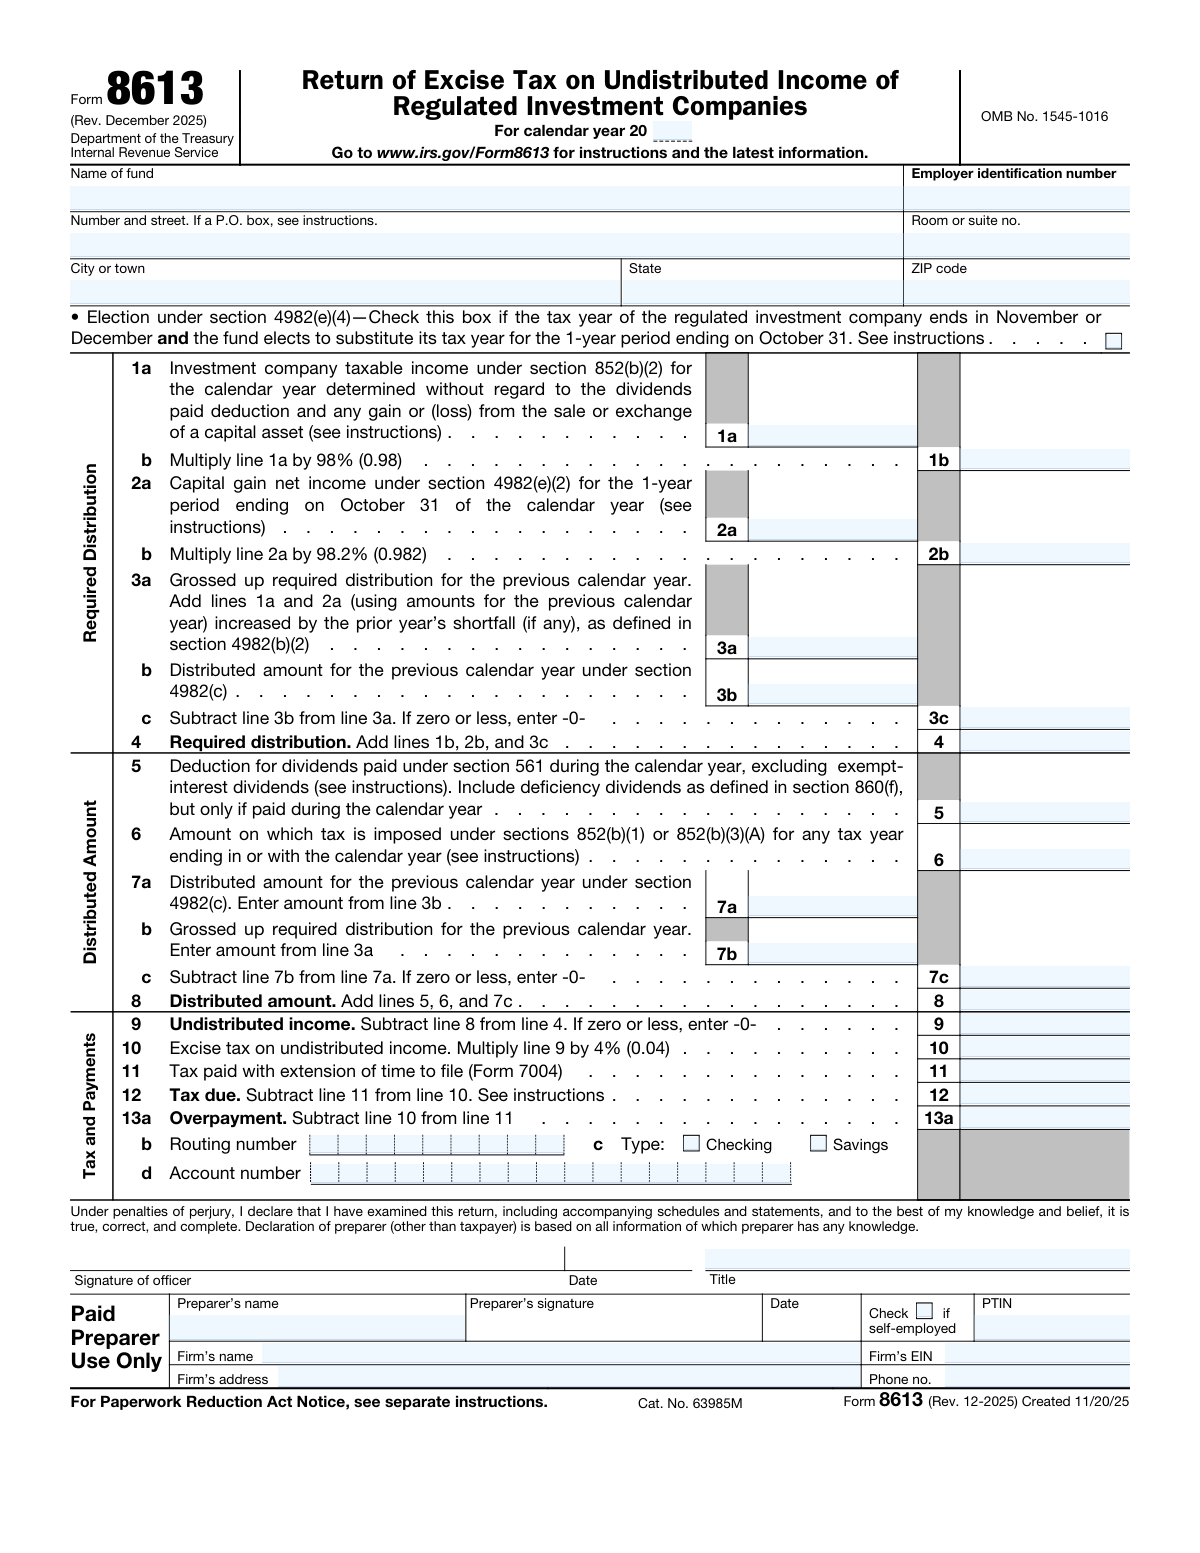
Form 8613, Return of Excise Tax, page 1
Basic · 45/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 8613, Return of Excise Tax on Undistributed Income of Regulated Investment Companies, is used to calculate and pay the excise tax on undistributed income. This form is important for regulated investment companies to report their tax liabilities accurately.
Fillable fields33
Pages1
Sections10
Form Complexity IndexBasic, 45/100

The AI checks your answers before you download

16 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Ensures that all information is typed or printed clearly on the 'Return of Excise Tax on Undistributed Income' (Form 8613).

The AI ensures that all entries on the 'Return of Excise Tax on Undistributed Income' (Form 8613) are legible and clear, minimizing the risk of errors due to misinterpretation. It checks for readability in all fields, including numerical and textual data, to facilitate accurate processing by tax authorities. The AI also confirms that no fields are left blank, and that all required information is provided in a format that is consistent with IRS guidelines.

Confirms that the form is being used by a Regulated Investment Company (RIC) as intended.

The AI confirms that the entity filing the 'Return of Excise Tax on Undistributed Income' is indeed a Regulated Investment Company (RIC) as defined by the IRS. It verifies the entity's status by cross-referencing the provided information with official records or databases. The AI ensures that the form is not being misused by entities that do not meet the criteria of a RIC, thus upholding the integrity of the filing process.

Verifies that the form is filed by the deadline of March 15 following the calendar year to which the tax liability applies, or confirms that Form 7004 has been filed for an extension.

The AI verifies the timeliness of the filing by checking the date of submission against the statutory deadline of March 15 following the calendar year to which the tax liability applies. If the form is submitted after this date, the AI checks for a confirmation that Form 7004 has been filed to secure an extension. This ensures compliance with IRS deadlines and helps avoid potential penalties for late filing.

Checks if 'Amended' is written at the top of the form when filing an amended Form 8613.

When processing an amended 'Return of Excise Tax on Undistributed Income' (Form 8613), the AI checks for the word 'Amended' inscribed at the top of the form. This validation is crucial to distinguish the amended filing from the original and to ensure that the IRS is alerted to the nature of the submission. The AI's attention to this detail aids in the proper handling and review of the amended return.

Ensures that the form is signed by an authorized officer of the RIC and includes the date and officer's title.

The AI ensures that the 'Return of Excise Tax on Undistributed Income' (Form 8613) is duly signed by an authorized officer of the Regulated Investment Company. It checks for the presence of a signature, the date of signing, and the title of the officer to confirm the form's authenticity and validity. The AI's validation process helps prevent the submission of unsigned or improperly executed forms, which could result in processing delays or rejections.

Rounding Off to Whole Dollars

Ensures that all monetary amounts entered on the form are rounded off to the nearest whole dollar. This validation check eliminates cents from all figures, maintaining consistency throughout the form and adhering to the IRS requirement for rounding. It prevents errors that may arise from including cents in the calculations, which are not accepted on this form.

And 10 more checks
  • Accuracy of Calculations
  • Investment Company Taxable Income
  • Capital Gain Net Income
  • Distributions
  • Verifies that the required distribution and the distributed amount are correctly calculated on Lines 4 and 8, respectively.
  • Ensures that the deduction for dividends paid is correctly entered on Line 5, excluding exempt-interest dividends.
  • Confirms that the excise tax on undistributed income is correctly calculated on Line 10 by multiplying Line 9 by 4%.
  • Validates that any tax paid with an extension (Form 7004) is correctly reported on Line 11.
  • Ensures that the tax due or overpayment is accurately calculated on Lines 12 and 13, respectively.
  • Paid Preparer Use Only Section Completion

Let AI fill out your Form 8613

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 8613 Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 8613.
  2. Enter the name of the fund and EIN.
  3. Fill in the required distribution amounts.
  4. Complete the distributed amount section.
  5. Sign and date the form electronically.
  6. Check for accuracy and submit the form.

Common Mistakes in Completing Form 8613

The ones the AI is built to catch.

Incorrect entry of investment company taxable income (Line 1a)
One of the most common mistakes on the Return of Excise Tax on Undistributed Income form is the failure to enter investment company taxable income (Line 1a) correctly. This error can occur when dividends paid deduction and capital gains are not excluded from the taxable income. To avoid this mistake, carefully review the instructions for calculating taxable income and ensure all adjustments are made before entering the figure on Line 1a. Additionally, double-check the figures for dividends paid and capital gains to ensure they are correctly reported and subtracted from the taxable income.
Calculation errors on lines 1b, 2b, and 10
Another common mistake on the Return of Excise Tax on Undistributed Income form is calculation errors on lines 1b, 2b, and 10. These lines require percentages to be applied to previous calculations. To avoid calculation errors, double-check all calculations before submitting the form. Use a calculator or spreadsheet to ensure accuracy and consistency in your calculations. Additionally, carefully review the instructions for each line to ensure you are applying the correct percentage to the correct calculation.
Miscalculation or omission of required distributions (Lines 3a, 3c, and 7b)
Failure to report and include required distributions (Lines 3a, 3c, and 7b) can lead to incorrect tax calculations on the Return of Excise Tax on Undistributed Income form. To avoid this mistake, carefully review the instructions for calculating required distributions and ensure all distributions are reported and included in the correct sections. Double-check your calculations to ensure accuracy and consistency.
Failure to report and include grossed-up required distributions (Lines 3a and 7b) in the correct sections
Another common mistake on the Return of Excise Tax on Undistributed Income form is the failure to report and include grossed-up required distributions (Lines 3a and 7b) in the correct sections. This error can result in incorrect tax calculations and potential penalties. To avoid this mistake, carefully review the instructions for calculating grossed-up required distributions and ensure they are reported and included in the correct sections.
Incorrect reporting or failure to report dividends paid (Line 5)
Failure to correctly report or report dividends paid (Line 5) on the Return of Excise Tax on Undistributed Income form can result in under or overpayment of tax. To avoid this mistake, carefully review the instructions for reporting dividends paid and ensure all dividends are reported in the correct section. Double-check your calculations to ensure accuracy and consistency.
Neglecting to sign the form and provide the required officer title and date in the 'Signature of Officer' section
The Return of Excise Tax on Undistributed Income form requires the signature of an officer authorized to sign for the organization, along with their title and the date. Failing to complete this section accurately can result in delays or rejections of the form by the Internal Revenue Service (IRS). To avoid this mistake, ensure that the person signing the form has the necessary authority and completes all required fields in the 'Signature of Officer' section.
Late filing or failure to file the form by the deadline
The IRS imposes strict deadlines for filing the Return of Excise Tax on Undistributed Income form. Failing to meet these deadlines can result in potential interest and penalties. To avoid this mistake, familiarize yourself with the filing deadlines and ensure that you submit the form on time. If you anticipate difficulty meeting the deadline, contact the IRS for guidance and potential extensions.
Omitting the paid preparer's information in the 'Paid Preparer Use Only' section, if applicable
If you have engaged a tax professional to help you complete the Return of Excise Tax on Undistributed Income form, it is essential to provide their information in the 'Paid Preparer Use Only' section. Failing to do so can result in delays or rejections of the form. To avoid this mistake, ensure that you provide the required information for the paid preparer, including their name, tax identification number, and signature. This information is necessary for the IRS to process the form and acknowledge the tax professional's involvement.

Frequently Asked Questions About Form 8613


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Oct 31 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 8613.
Can I fill other forms too?
This plan is for your Form 8613: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 8613?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 8613, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Form 8613 to fill out?
Form 8613 has a Form Complexity Index of 45 out of 100, in the basic tier: 33 fillable fields across 1 page. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is the purpose of Form 8613?
Form 8613, also known as the 'Return of Excise Tax on Undistributed Income,' is used to report and pay the excise tax on undistributed income from certain types of retirement plans and individual retirement accounts (IRAs). This tax applies to individuals who have reached the required minimum distribution age but have not yet taken their required minimum distributions.
Who is required to file Form 8613?
Individuals who have an interest in a retirement plan or IRA and have not taken their required minimum distributions by the deadline are required to file Form 8613 if their combined account balances exceed the minimum distribution amount. The minimum distribution amount is determined by the IRS based on the account owner's age and life expectancy.
What types of income should be included in line 1a?
Line 1a of Form 8613 requires reporting the total amount of taxable income from all of your retirement plans and IRAs that you have not yet taken distributions from. This includes traditional IRAs, SEP IRAs, SIMPLE IRAs, 401(k) plans, 403(b) plans, and other qualified retirement plans.
What is the difference between required distribution and distributed amount?
The required distribution is the minimum amount that must be withdrawn from a retirement account each year based on the account owner's age and life expectancy. The distributed amount is the actual amount that is taken out of the account and paid to the account owner. If the distributed amount is less than the required minimum distribution, the difference must be reported and paid as excise tax on Form 8613.
What is the penalty for late payment of tax?
The penalty for late payment of the excise tax on undistributed income is 50% of the amount that should have been paid. This penalty applies if the tax is not paid by the due date, which is typically April 15 of the year following the year in which the required minimum distribution was due. However, there are certain exceptions and waivers to this penalty, so it's important to consult the IRS guidelines or consult with a tax professional for specific situations.
What is the penalty for late filing of return?
The penalty for late filing of the Return of Excise Tax on Undistributed Income is generally 5% of the tax required to be shown on the return for each month or part of a month that the return is late, not to exceed 25% of the tax. If the return is more than 60 days late, an additional penalty of 10% of the tax is assessed. It is important to note that these penalties apply in addition to any interest that may accrue on the unpaid tax.
What is the election under section 4982(e)(4) and how does it affect the form?
Section 4982(e)(4) of the Internal Revenue Code allows a taxpayer to elect to include certain undistributed income in income during the taxable year in which it is earned, rather than in the year it is distributed. This election can affect the Return of Excise Tax on Undistributed Income by changing the amount of taxable income reported on the form. To make this election, taxpayers must file Form 2704, Periodic Application for Large Taxpayer Status and Administrative Adjustment Request, along with the Return of Excise Tax on Undistributed Income. It is important to consult with a tax professional before making this election, as it may have significant tax implications.
How should capital gain net income be calculated for line 2a?
Capital gain net income for line 2a of the Return of Excise Tax on Undistributed Income is calculated by subtracting the total capital losses from the total capital gains reported on the taxpayer's income tax return for the taxable year. Capital gains and losses are reported on Schedule D (Form 1040), Capital Gains and Losses. It is important to note that only net capital gains or losses are reported on the Return of Excise Tax on Undistributed Income, not the individual gains or losses themselves.
What is the difference between line 5 and line 6?
Line 5 of the Return of Excise Tax on Undistributed Income reports the total taxable income from all sources, including tax-exempt income, that is subject to the excise tax. Line 6 reports the total taxable income from sources other than tax-exempt income that is subject to the excise tax. The difference between the two lines represents the amount of tax-exempt income that is included in the taxable income for excise tax purposes. It is important to note that tax-exempt income may still be subject to income tax, but it is not subject to the excise tax reported on this form.
What is the method for making federal tax deposits?
Federal tax deposits for the excise tax reported on the Return of Excise Tax on Undistributed Income can be made electronically using the Electronic Federal Tax Payment System (EFTPS) or by check or money order. To make a deposit electronically, taxpayers must enroll in EFTPS and make deposits according to the deposit schedule provided by the IRS. To make a deposit by check or money order, taxpayers should make the check or money order payable to the 'United States Treasury' and include the deposit slip provided with the form. It is important to note that federal tax deposits must be made by the due date of the return to avoid penalties.
What is the deadline for making federal tax deposits using EFTPS?
The deadline for making federal tax deposits using EFTPS for Form 8613 is the same as the due date of the tax return. Please refer to the instructions of Form 8613 or consult with a tax professional for the specific due date of your return.
What is the Paperwork Reduction Act Notice and how does it affect the form?
The Paperwork Reduction Act (PRA) notice is a statement that explains the data collection requirements of the form and the estimated burden on taxpayers. The notice number for Form 8613 is 1545-1111. Compliance with the PRA is mandatory, and failure to provide the required information may result in penalties or delays in processing your return.
What is the estimated time to complete and file Form 8613?
The estimated time to complete and file Form 8613 depends on the complexity of your tax situation. Generally, it may take several hours to a few days to gather all the necessary information and complete the form. It is recommended to start the process early and consult with a tax professional if you have any questions or concerns.
How should the fund show amounts on the return as whole dollars?
The fund should report amounts on Form 8613 in whole dollars, without any cents. If the fund has a fraction of a cent, it should be rounded to the nearest whole dollar. For example, if the amount is $123.45, it should be reported as $124 on the form.
What is the tax imposed under sections 852(b)(1) or 852(b)(3)(A) for any tax year ending in or with the calendar year?
Section 852(b)(1) imposes a tax on the undistributed income of a tax-exempt organization that is subject to the tax on unrelated business taxable income (UBTI). The tax rate is equal to the corporate income tax rate. Section 852(b)(3)(A) imposes an additional tax on the undistributed income of a tax-exempt organization that is invested in a controlled organization. The tax rate is equal to the highest individual income tax rate. Both taxes apply to tax years ending in or with the calendar year.
What is the difference between Form 8613 and Form 7004?
Form 8613, the Excise Tax Return for Undistributed Income, is used by tax-exempt organizations, trusts, and estates to report and pay the excise tax on undistributed income. Form 7004, the Annual Return or Application for Automatic Extension of Time To File Certain Business Income Tax, Corporate, and Certain Other Returns, is used by businesses and individuals to request an extension of time to file their tax returns. While both forms involve tax reporting, they serve distinct purposes.
How should the fund make an amended return?
To file an amended return (Form 8613-A), the fund must submit a corrected Form 8613 along with an explanation of the changes made. The explanation should include the reason for the correction and the difference between the originally reported amount and the corrected amount. The amended return should be filed as soon as possible to minimize any potential penalties or interest.
What is the signature requirement for Form 8613?
Form 8613 requires the signature of an officer, trustee, or other authorized individual of the fund. The signature signifies that the individual has examined the return and believes it to be accurate. In the case of a trust, the signature of the trustee or the trust's fiscal agent is required. For estates, the signature of the executor or the estate's fiscal representative is necessary.
What is the rounding off to whole dollars rule?
The rounding off to whole dollars rule applies to the calculation of the excise tax on undistributed income. The tax is rounded up to the nearest multiple of $5 for amounts between $0.01 and $9.99, and rounded up to the nearest multiple of $10 for amounts equal to or greater than $10. This rule simplifies the reporting and payment process for funds and reduces the administrative burden.
What is the difference between a series fund and a regular fund?
A series fund is a type of investment company that offers multiple series of shares, each with distinct investment objectives, policies, or strategies. Series funds are treated as a single fund for tax purposes, but they allow investors to choose the series that best fits their investment goals. A regular fund, on the other hand, is a single investment company with a single investment objective or strategy. Both series funds and regular funds are subject to the excise tax on undistributed income if they meet the applicable requirements.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 8613 filled out by AI

$0 today. Cancel before Oct 31 and you pay nothing.

7 days free, then $19.99/month · Cancel anytime