
Instafill.ai
7 days free
AI form filling · 28 fields · 1 page · done in seconds

Yes! You can use AI to fill out Form 8910, Alternative Motor Vehicle Credit

Don't type 28 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
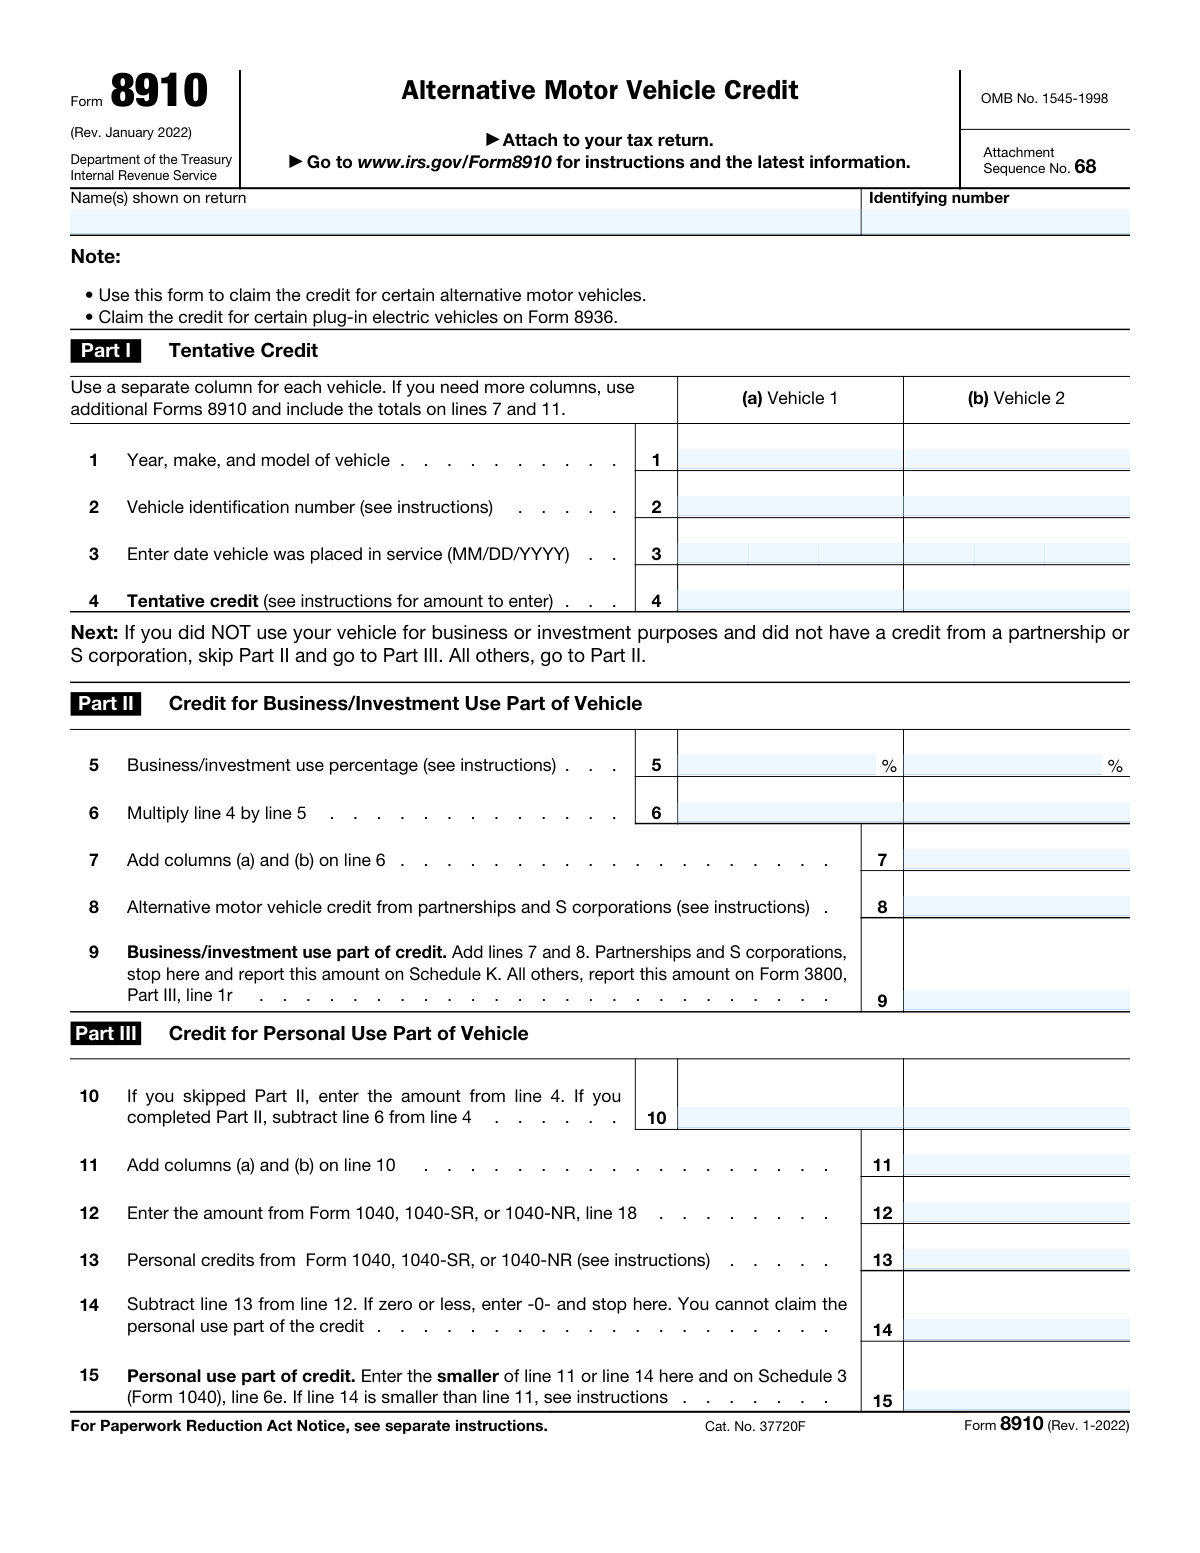
Form 8910, Alternative Motor Vehicle Credit, page 1
Basic · 37/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Form 8910, Alternative Motor Vehicle Credit, is used to claim a credit for certain alternative motor vehicles. This form is important for taxpayers who have purchased eligible vehicles, as it allows them to reduce their tax liability by claiming the appropriate credits.
Fillable fields28
Pages1
Sections4
Form Complexity IndexBasic, 37/100

The AI checks your answers before you download

15 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Ensures the Vehicle Identification Number (VIN) entered on Line 2 is a valid 17-character alphanumeric string.

This validation check ensures that the VIN provided on Line 2 adheres to the standard format, which is a 17-character alphanumeric string. It confirms that all characters are either letters or numbers, without any special symbols or spaces. The check also verifies that the VIN does not contain any illegal characters that are not used in VINs, such as 'I', 'O', or 'Q'. Additionally, it validates that the VIN length is exactly 17 characters, as required for proper identification of the vehicle.

Confirms that the tentative credit amount entered on Line 4 matches the manufacturer's or domestic distributor's certification to the IRS.

This validation check confirms that the amount of tentative credit claimed on Line 4 is consistent with the certification provided by the vehicle's manufacturer or domestic distributor to the IRS. It ensures that the credit amount does not exceed the certified limit and matches the figures authorized for the specific make and model of the alternative motor vehicle. The check also verifies the accuracy of the credit calculation against the current IRS guidelines and approved amounts.

Verifies the percentage of business/investment use entered on Line 5 is calculated correctly based on the miles driven for business purposes versus total miles driven.

This validation check verifies that the percentage of business or investment use claimed on Line 5 is accurately calculated. It ensures that the calculation is based on the actual miles driven for business or investment purposes in comparison to the total miles driven by the vehicle. The check also confirms that the percentage is represented as a decimal fraction of one and does not exceed 100%, which would be logically incorrect.

Checks that any alternative motor vehicle credits reported from a partnership or S corporation on Line 8 are accurately totaled from Schedule K-1.

This validation check ensures that any alternative motor vehicle credits reported on Line 8, which originate from a partnership or S corporation, are accurately summed up from the information provided on Schedule K-1. It confirms that the total credit amount claimed is the aggregate of the individual credits reported on the K-1 forms. The check also verifies that the credits are applicable for the tax year in question and have been correctly transferred to the main form.

Validates the total of other credits entered on Line 13 against the sum from Schedule 3 (Form 1040) lines 1 through 4, 6d, and 6I; and Form 5695, line 30.

This validation check validates that the total of other credits entered on Line 13 is in agreement with the sum of the credits reported on Schedule 3 (Form 1040) lines 1 through 4, 6d, and 6I, as well as Form 5695, line 30. It ensures that there are no discrepancies between the credits claimed on different parts of the tax return and that the total on Line 13 accurately reflects the sum of these individual credit amounts. The check also confirms that the credits are eligible for the current tax year and have been properly documented.

Qualified Fuel Cell Vehicle Confirmation

The system confirms that the vehicle in question is indeed a qualified fuel cell vehicle, which is a prerequisite for eligibility for the Alternative Motor Vehicle Credit. It cross-references the vehicle's make, model, and year against the list of qualified fuel cell vehicles provided by the IRS. This ensures that the credit is not erroneously claimed for a vehicle that does not meet the necessary environmental and efficiency standards set forth by the government.

And 9 more checks
  • Vehicle Placement and Purchase Year Verification
  • Taxpayer Ownership and Usage Check
  • Seller to Tax-Exempt Organization Verification
  • Basis Reduction by Credit Amount Verification
  • No Carryback or Forward of Unused Personal Credit
  • Recapture of Credit Compliance
  • Recordkeeping for Future Administration
  • Acknowledgement of Time Estimates
  • Current Information and Legislative Changes Review

Let AI fill out your Form 8910

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Form 8910 Online for Free in 2026

What the AI walks you through.

  1. Visit instafill.ai site and select Form 8910.
  2. Enter your name and identifying number.
  3. Provide vehicle details and tentative credit.
  4. Complete business/investment use section if applicable.
  5. Fill out personal use part of the credit.
  6. Sign and date the form electronically.
  7. Check for accuracy and submit the form.

Common Mistakes in Completing Form 8910

The ones the AI is built to catch.

Incorrect or Incomplete Vehicle Identification Number (VIN) on Line 2
The Vehicle Identification Number (VIN) is a unique code assigned to every motor vehicle. It is essential to enter the correct and complete VIN on Line 2 of the Alternative Motor Vehicle Credit form. Failing to do so may result in incorrect calculations of your credit. To avoid this mistake, ensure you have the correct VIN before filling out the form. You can find the VIN on the vehicle's registration or insurance documents or on the vehicle itself, usually located near the windshield or the driver's side door. Double-check the VIN before submitting the form to prevent any errors.
Failure to Enter Tentative Credit Amount from Manufacturer or Domestic Distributor on Line 4
Line 4 of the Alternative Motor Vehicle Credit form requires you to enter the tentative credit amount from the manufacturer or domestic distributor. This amount is crucial for calculating the actual credit you can claim. Neglecting to enter this information may result in an incorrect credit calculation. To avoid this mistake, ensure you have the necessary information from the manufacturer or domestic distributor before filling out the form. You can find this information on the Certificate of Origin or the invoice from the dealer. Double-check the information before submitting the form to prevent any errors.
Neglecting to Calculate the Percentage of Business/Investment Use on Line 5
Line 5 of the Alternative Motor Vehicle Credit form requires you to calculate the percentage of business or investment use of the vehicle. This percentage is essential for determining the amount of credit you can claim. Neglecting to calculate this percentage may result in an incorrect credit calculation. To avoid this mistake, ensure you have accurate records of the total miles driven for business or investment purposes and the total miles driven for personal use. Use the provided formula on the form to calculate the percentage and double-check your work before submitting the form to prevent any errors.
Incorrect Total of Credits from Schedule 3 and Form 5695 on Line 13
Line 13 of the Alternative Motor Vehicle Credit form requires you to enter the total of credits from Schedule 3 and Form 5695. This total is crucial for determining the total alternative motor vehicle credit you can claim. Entering an incorrect total may result in an incorrect credit calculation. To avoid this mistake, ensure you have accurate records of all the credits claimed on Schedule 3 and Form 5695. Double-check the totals before submitting the form to prevent any errors.
Failure to Report Any Alternative Motor Vehicle Credits Received from a Partnership or S Corporation on Line 8
Line 8 of the Alternative Motor Vehicle Credit form requires you to report any alternative motor vehicle credits received from a partnership or S corporation. Failing to report these credits may result in an incorrect credit calculation. To avoid this mistake, ensure you have accurate records of any alternative motor vehicle credits received from a partnership or S corporation. Report these credits on Line 8 and double-check the information before submitting the form to prevent any errors.
Neglecting to account for the loss of unused personal credit on Line 15
Taxpayers may overlook the fact that they have lost any unused personal credit carryforward when calculating the Alternative Motor Vehicle Credit. This oversight can lead to an incorrect credit amount being claimed. To avoid this mistake, taxpayers should carefully review their previous tax returns and account for any unused personal credit when filling out this form.
Failure to maintain proper records related to the form and its instructions
Proper documentation and record-keeping are essential when claiming the Alternative Motor Vehicle Credit. Taxpayers may overlook the importance of keeping records related to the purchase, ownership, and disposal of qualifying vehicles. This can lead to errors or discrepancies when calculating the credit. To prevent this mistake, taxpayers should keep detailed records of all transactions related to the qualifying vehicles and refer to the form instructions regularly.
Placing a vehicle in service after the credit expiration date
Taxpayers may mistakenly believe they can still claim the Alternative Motor Vehicle Credit for a vehicle that was placed in service after the credit expiration date. This can result in an incorrect credit amount being claimed or even disqualification of the credit. To avoid this mistake, taxpayers should familiarize themselves with the credit expiration dates and ensure that all qualifying vehicles are placed in service before these dates.
Claiming the credit for a vehicle that does not meet the qualifications for a fuel cell vehicle
Taxpayers may mistakenly claim the Alternative Motor Vehicle Credit for a vehicle that does not meet the qualifications for a fuel cell vehicle. This can result in an incorrect credit amount being claimed or even disqualification of the credit. To prevent this mistake, taxpayers should carefully review the form instructions and ensure that the vehicle meets all the necessary qualifications for the credit.
Failing to report the sale of a vehicle to a tax-exempt organization, governmental unit, or foreign person/entity
Taxpayers may overlook the requirement to report the sale of a qualifying vehicle to a tax-exempt organization, governmental unit, or foreign person/entity. This can result in an incorrect credit amount being claimed or even disqualification of the credit. To prevent this mistake, taxpayers should familiarize themselves with the reporting requirements and ensure that all necessary reports are filed.
Neglecting to Adjust the Basis of the Vehicle
One of the most common mistakes made when filling out the Alternative Motor Vehicle Credit form is failing to adjust the basis of the vehicle by the amount of the credit claimed. The basis of the vehicle is the cost or other basis in the vehicle before applying the credit. By not making this adjustment, the taxpayer may overstate their basis in the vehicle and potentially underreport their taxable income. To avoid this mistake, it is recommended to carefully review the instructions on the form and make the necessary adjustment to the basis of the vehicle before calculating the credit. Additionally, keeping accurate records of the purchase price, sales price, and any relevant improvements or adjustments made to the vehicle can help ensure the correct basis is used.
Failing to Recapture Part or All of the Credit When the Vehicle No Longer Qualifies
Another mistake made when filling out the Alternative Motor Vehicle Credit form is failing to recapture part or all of the credit when the vehicle no longer qualifies. The credit is only allowed for vehicles that are used for business purposes over 50% of the time. If the vehicle is no longer used for business purposes or the percentage of business use falls below 50%, the taxpayer must recapture the previously claimed credit. Failure to do so can result in underreported income and potential penalties. To avoid this mistake, it is recommended to carefully review the instructions on the form and keep accurate records of the percentage of business use for each vehicle. Additionally, if a vehicle is sold, traded, or no longer used for business purposes, the taxpayer should calculate and report any necessary recapture of previously claimed credits on their tax return.

Frequently Asked Questions About Form 8910


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 1 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Form 8910.
Can I fill other forms too?
This plan is for your Form 8910: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Form 8910?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Form 8910, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Form 8910 to fill out?
Form 8910 has a Form Complexity Index of 37 out of 100, in the basic tier: 28 fillable fields across 1 page. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is the Alternative Motor Vehicle Credit form used for?
Form 8910, Alternative Motor Vehicle Credit, is used to calculate and claim a credit for the cost of purchasing, leasing, or placing in service certain alternative motor vehicles or their components. These vehicles include qualified fuel cell motor vehicles, qualified hybrid vehicles, qualified plug-in electric vehicles, and qualified alternative fuel vehicle refueling property.
Who should use Form 8910 for the Alternative Motor Vehicle Credit?
Individuals, estates, and trusts who have purchased, leased, or placed in service a qualified alternative motor vehicle or qualified alternative fuel vehicle refueling property during the tax year should file Form 8910 to calculate and claim the credit.
What information is required for Part I of Form 8910?
Part I of Form 8910 requires the taxpayer to provide information about each qualified alternative motor vehicle or qualified alternative fuel vehicle refueling property, including the vehicle identification number (VIN), the date of acquisition, the cost or lease price, and the type of vehicle or property. The taxpayer must also indicate whether the vehicle is a new or used vehicle and whether it is a passenger automobile or light truck.
How do I calculate the tentative credit for each vehicle in Part I?
The tentative credit for each vehicle is calculated using the applicable percentage and the cost or lease price of the vehicle. The applicable percentage depends on the type of vehicle and the taxpayer's taxable income. The instructions for Form 8910 provide tables to help taxpayers determine the applicable percentage. The tentative credit is then reduced by any qualified plug-in electric vehicle credit or qualified fuel cell motor vehicle credit the taxpayer may be eligible for.
What should I do if I used my vehicle for business or investment purposes or received a credit from a partnership or S corporation?
If you used your qualified alternative motor vehicle for business or investment purposes, you must complete Part II of Form 8910 to figure the business use percentage and the business use credit. If you received a credit from a partnership or S corporation for the same vehicle, you must subtract that credit from the total credit you figure on Form 8910.
How do I calculate the credit for business/investment use in Part II?
To calculate the credit for business or investment use in Part II of Form 8910, you need to follow these steps: 1. Determine the total amount of qualified fuel costs for the tax year. Qualified fuel costs include the cost of alternative fuel and the cost of the transportation of the alternative fuel to the point where it is first used, sold, or otherwise disposed of in a trade or business or in an activity held for the production of income. 2. Determine the percentage of the total amount of qualified fuel costs that is attributable to business or investment use. 3. Multiply the total amount of qualified fuel costs by the percentage of business or investment use. 4. Enter the result on line 1 of Part II. 5. Multiply line 1 by the alternative motor vehicle credit rate for the tax year. 6. Enter the result on line 2. 7. Subtract line 3 from line 2 to find the credit for business or investment use.
What should I do if I am not required to complete Part II?
If you are not required to complete Part II of Form 8910, you should still complete Part III to claim the credit for personal use of an alternative motor vehicle. If you are not required to complete Part II because you did not have any qualified fuel costs for business or investment use during the tax year, you should enter a zero on line 1 of Part II and sign the form.
How do I calculate the credit for personal use in Part III?
To calculate the credit for personal use in Part III of Form 8910, you need to follow these steps: 1. Determine the total amount of qualified fuel costs for personal use during the tax year. Qualified fuel costs include the cost of alternative fuel and the cost of the transportation of the alternative fuel to the point where it is first used in a personal vehicle. 2. Multiply the total amount of qualified fuel costs for personal use by the alternative motor vehicle credit rate for the tax year. 3. Enter the result on line 1 of Part III. 4. Subtract any qualified fuel costs for business or investment use (from Part II) from the total qualified fuel costs for personal use. 5. Multiply the result from step 4 by the alternative motor vehicle credit rate for the tax year. 6. Enter the result on line 2 of Part III. 7. Subtract line 1 from line 6 to find the credit for personal use.
What information is required for Part III of Form 8910?
To complete Part III of Form 8910, you need to provide the following information: 1. Your name, address, and social security number or taxpayer identification number. 2. The total amount of qualified fuel costs for personal use during the tax year. 3. The alternative motor vehicle credit rate for the tax year. 4. The total amount of qualified fuel costs for business or investment use during the tax year (if applicable).
What is the difference between lines 10 and 11 in Part III?
Lines 10 and 11 in Part III of Form 8910 serve different purposes. Line 10 is used to calculate the total amount of qualified fuel costs for personal use during the tax year. This amount is multiplied by the alternative motor vehicle credit rate to determine the credit for personal use (line 2). Line 11 is used to calculate the alternative fuel mixture percentage for the tax year. This percentage is used to determine the amount of qualified fuel costs for business or investment use that can be subtracted from the total qualified fuel costs for personal use to find the net qualified fuel costs for personal use (line 6).
What personal credits can be subtracted from line 12 in Part III?
The Alternative Motor Vehicle Credit allows taxpayers to claim a credit for the purchase of certain alternative fuel vehicles or for the installation of alternative fuel vehicle refueling equipment. The personal credits that can be subtracted from line 12 in Part III include the Qualified Plug-in Electric Drive Motor Vehicle Credit, the Alternative Fuel Vehicle Refueling Property Credit, and the Alternative Fuel Mixture Excise Tax Credit. Taxpayers should refer to the instructions for Form 8910 and the IRS Publication 596 for more information on these credits.
What should I do if the personal use part of the credit is less than the total credit?
If the personal use part of the Alternative Motor Vehicle Credit is less than the total credit, taxpayers should report the excess amount as a business credit on Form 4562, Part II. The instructions for Form 8910 provide more details on how to calculate and report the business credit.
Where should I report the Alternative Motor Vehicle Credit from Form 8910?
The Alternative Motor Vehicle Credit from Form 8910 is reported on Form 1040, line 43, or Form 1041, line 15, as other credits. Taxpayers should refer to the instructions for their specific tax form for more information on reporting the credit.
What is the purpose of the Paperwork Reduction Act Notice on Form 8910?
The Paperwork Reduction Act (PRA) Notice on Form 8910 is a statement from the Internal Revenue Service (IRS) that the collection of information on the form is necessary for the IRS to administer and enforce the Internal Revenue Code. The notice includes the estimated time required to complete the form and the estimated burden on taxpayers. Taxpayers are encouraged to read the instructions for Form 8910 carefully to ensure they provide all required information.
Can I file Form 8910 electronically?
Yes, taxpayers can file Form 8910 electronically using IRS-approved software or through the IRS Free File program. Taxpayers should refer to the instructions for Form 8910 and the IRS website for more information on electronic filing options.
What is the OMB No. for Form 8910?
The OMB (Office of Management and Budget) No. for Form 8910, Alternative Motor Vehicle Credit, is 1120-2714.
Where can I find the latest instructions and information for Form 8910?
The latest instructions and information for Form 8910, Alternative Motor Vehicle Credit, can be found on the IRS (Internal Revenue Service) website. You can visit the IRS website at www.irs.gov and search for Form 8910 in the Forms library. Alternatively, you can call the IRS Business and Specialty Tax Line at 1-800-829-4933 for assistance.
What form should I use to claim the credit for certain plug-in electric vehicles?
To claim the credit for certain plug-in electric vehicles, you should use Form 8910, Alternative Motor Vehicle Credit. This form is used to calculate and claim the credit for qualified plug-in electric vehicles, including passenger vehicles and light trucks. Make sure to follow the instructions carefully and provide all required information to ensure the accurate calculation and claim of the credit.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Form 8910 filled out by AI

$0 today. Cancel before Nov 1 and you pay nothing.

Other forms like this one

credit forms: Form 5405, Repayment of First-Time Homebuyer Credit, Form 8862, Information To Claim Certain Credits, Form 8880, Credit for Qualified Retirement Savings Contributions, Form 5695, Residential Energy Credits, Form 3468, Investment Credit, Form 8801, Credit for Prior Year Minimum Tax, Form FTB 3514, California Earned Income Tax Credit, Form 8885, Health Coverage Tax Credit, Form 5884-A, Employee Retention Credit, Form 5884, Work Opportunity Credit, Form 5884-C, Work Opportunity Credit, Form 8994, Employer Credit for Paid Family and Medical Leave, Form 8962, Premium Tax Credit (PTC), Form 8812, Credits for Qualifying Children, Form 104, List of Creditors 20 Largest Unsecured Claims, WestRock Credit Application and Uniform Sales & Use Tax Exemption/Resale Certificate — Multijurisdiction, Personal Financial Statement (REV 06/2018) – Northwest Federal Credit Union, Form G-1450, Authorization for Credit Card Transactions, 2023 Schedule IL-E/EIC, Illinois Exemption and Earned Income Tax Credit (Illinois Department of Revenue), Form 5695 (2025), Residential Energy Credits

motor vehicle forms: Colorado Form DR 0026, Tax Statement for Leased Motor Vehicle, State of Florida Department of Highway Safety and Motor Vehicles (FLHSMV) Form HSMV 82993, Separate Odometer Disclosure Statement and Acknowledgment, California Department of Motor Vehicles (DMV) Form REG 135, Bill of Sale, Letter of Authorization - County of Kauai Department of Finance, Division of Motor Vehicles & Licensing, Form 735-501, Vehicle Bill of Sale, Form DR 0024, Standard Sales Tax Receipt for Vehicle Sales, Form DR 2020SP, Exception Processing Application, Form MV-82TON, Application for Title, Form VR-005, Application for Certificate of Title, Georgia Department of Revenue Form T-7, Bill of Sale, Form MV-104, Report of Motor Vehicle Accident, Form DTF-802, Statement of Transaction – Sale or Gift of Motor Vehicle, Trailer, All-Terrain Vehicle (ATV), Vessel (Boat), or Snowmobile, Form HSMV 82050, Notice of Sale and/or Bill of Sale for a Motor Vehicle, Mobile Home, Off-Highway Vehicle or Vessel, Power of Attorney for a Motor Vehicle, Mobile Home, or Vessel, Emancipated Minor's Application to California Department of Motor Vehicles, Form PLD-PI-001(1), Cause of Action—Motor Vehicle, Small Claims Complaint - Motor Vehicle - Appendix XI-D, Supplemental Plea Form for Eluding (N.J.S.A. 2C:29-2b) or Theft of a Motor Vehicle or Unlawful Taking of a Motor Vehicle (N.J.S.A. 2C:20-2.1) (Plea 07), Complaint and Proposed Form of Order for Action Seeking Title to Motor Vehicle, Form REG 343, Application for Title or Registration (Rev. 2/2012)

7 days free, then $19.99/month · Cancel anytime