
Instafill.ai
7 days free
AI form filling · 390 fields · 3 pages · done in seconds

Yes! You can use AI to fill out Schedule J (Form 5471), Accumulated Earnings & Profits (E&P) of Controlled Foreign Corporation

Don't type 390 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
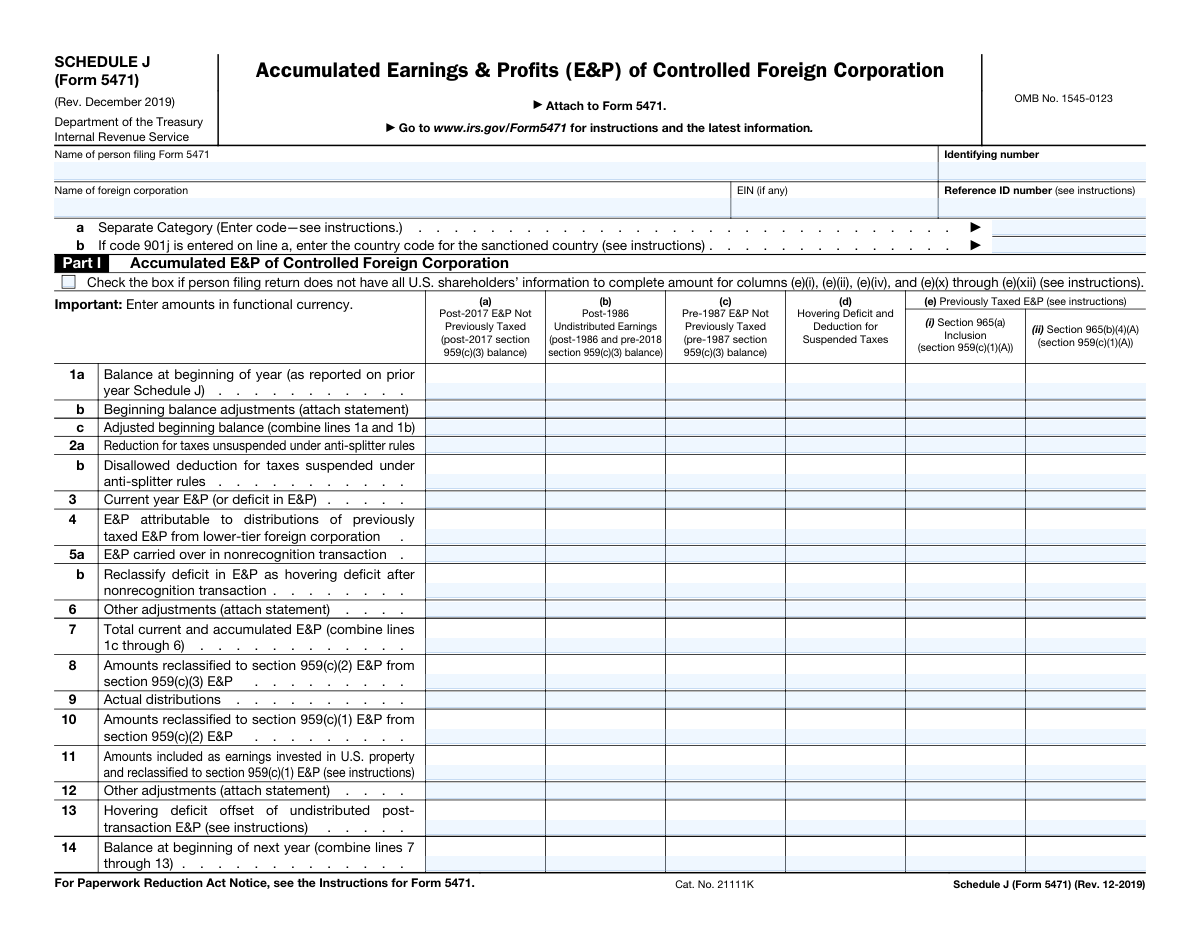
Schedule J (Form 5471), Accumulated Earnings & Profits (E&P) of Controlled Foreign Corporation, page 1
Complex · 78/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, tables and checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

Schedule J (Form 5471) is a detailed tax schedule attached to Form 5471, used by U.S. shareholders of a Controlled Foreign Corporation (CFC) to report the corporation's accumulated earnings and profits (E&P). This form is critical for tracking E&P pools, calculating taxable income from foreign operations, and ensuring compliance with complex international tax rules like Subpart F and GILTI. The intricate calculations and classifications required make accuracy paramount. Today, this form can be filled out quickly and accurately using AI-powered services like Instafill.ai, which can also convert non-fillable PDF versions into interactive fillable forms.
Fillable fields390
Pages3
Sections43
Tables and lists3
Questions that depend on earlier answers12
Form Complexity IndexComplex, 78/100

The AI checks your answers before you download

12 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Filer Identifying Number Format

This check verifies that the 'Filer identifying number' is in a valid format, either a 9-digit Employer Identification Number (EIN) (XX-XXXXXXX) or a 9-digit Social Security Number (SSN) (XXX-XX-XXXX). This is critical for correctly identifying the filer with the IRS and linking the form to the correct tax return. If the format is invalid, the submission could be rejected or delayed, causing processing issues.

Conditional Sanctioned Country Code Requirement

This validation ensures that the 'Sanctioned country code' on line b is filled out only when the 'Separate Category' code on line a is '901j'. The country code is required for this specific category but should be empty for all others. This check prevents incorrect or extraneous data entry, ensuring compliance with the form's specific instructions. A failure would trigger an error asking the user to either remove the country code or change the category code.

Part I, Line 1c Calculation Accuracy

This check validates that for each column in Part I, the value on 'Line 1c - Adjusted beginning balance' correctly equals the sum of 'Line 1a - Balance at beginning of year' and 'Line 1b - Beginning balance adjustments'. This is a fundamental arithmetic check to ensure the starting balance for the year's calculations is accurate. An error here would cascade through the rest of the form, making all subsequent calculations incorrect.

Part I, Line 7 Calculation Accuracy

This validation verifies that for each column in Part I, the value on 'Line 7 - Total current and accumulated E&P' is the precise sum of lines 1c through 6. This is a critical subtotal that represents the total E&P before distributions and reclassifications. If this calculation is incorrect, it indicates a flaw in the reported activities for the year and will lead to an incorrect ending balance.

Part I, Line 14 Calculation Accuracy

This check ensures that for each column in Part I, the 'Line 14 - Balance at beginning of next year' is the correct result of combining lines 7 through 13. This is the final and most important calculation in Part I, as it determines the ending balance that will be carried over to the next year's form. An incorrect total here would create continuity problems and require future amendments.

Part II, Line 4 Calculation Accuracy

This validation confirms that 'Line 4 - Balance at end of year' in Part II is correctly calculated by taking 'Line 1 - Balance at beginning of year', adding 'Line 2 - Additions', and subtracting 'Line 3 - Subtractions'. This ensures the roll-forward calculation for nonpreviously taxed E&P subject to recapture is arithmetically sound. An incorrect balance could lead to miscalculation of future tax liabilities.

And 6 more checks
  • Attachment Requirement for Adjustments
  • Completeness of Filer and Corporation Names
  • Total E&P Column (f) Row Summation
  • Beginning Balance Consistency with Prior Year
  • Hovering Deficit Sign Consistency
  • Foreign Corporation EIN Format

Let AI fill out your Schedule J (Form 5471)

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Schedule J (Form 5471) Online for Free in 2026

What the AI walks you through.

  1. Navigate to Instafill.ai and upload or select Schedule J (Form 5471).
  2. Provide the filer's and foreign corporation's identification details, such as names and identifying numbers, as prompted by the AI.
  3. Complete Part I by entering financial data for the accumulated E&P, following the AI's guidance for each category, including beginning balances, adjustments, and current year E&P.
  4. Input amounts for reclassifications, distributions, and other adjustments in lines 8 through 13 of Part I.
  5. Fill out Part II to report nonpreviously taxed E&P subject to recapture, including the beginning balance, additions, and subtractions for the year.
  6. Review the entire form after the AI populates the fields, verifying the accuracy of all financial figures and identification details.
  7. Securely download, print, or e-file the completed Schedule J, ready to be attached to your Form 5471.

Common Mistakes in Completing Schedule J (Form 5471)

The ones the AI is built to catch.

Using Incorrect Currency for Financial Amounts
This form explicitly requires all financial amounts to be entered in the foreign corporation's functional currency, not U.S. dollars. This mistake often occurs when preparers default to USD or are unaware of the functional currency rules. Using the wrong currency leads to a completely inaccurate representation of the corporation's E&P, which can trigger IRS inquiries, require amended returns, and result in incorrect tax calculations for U.S. shareholders. To avoid this, always verify the CFC's functional currency from its books and records before starting the form and ensure all entries are converted and reported accordingly.
Mismatching Beginning and Prior Year-End Balances
Line 1a, 'Balance at beginning of year,' must exactly match the ending balance from the prior year's Schedule J (Line 14). Filers often make mistakes by manually re-entering data, referencing the wrong prior-year file, or failing to account for amendments made to the prior year's return. A mismatch is a red flag for the IRS, suggesting a break in the continuity of the E&P tracking and potentially leading to audits. To prevent this, directly carry over the figures from the previous year's filed and accepted Schedule J, and if any adjustments are needed, report them on Line 1b with an attached statement.
Misclassifying Earnings and Profits (E&P)
The form has over 20 columns for different categories of E&P, such as Post-2017, Pre-1987, and numerous types of Previously Taxed E&P (PTI). A common error is placing an amount in the wrong column, for example, confusing a Section 951A inclusion under 959(c)(1)(A) with one under 959(c)(2). This happens due to the complexity of the tax code and the sheer number of similar-looking columns. Misclassification can lead to incorrect taxation of distributions, double taxation, or failure to utilize PTI, resulting in significant tax overpayments or underpayments. Careful review of the source and character of each E&P item against the column definitions is critical.
Forgetting to Attach Required Statements
Lines 1b ('Beginning balance adjustments'), 6 ('Other adjustments'), and 12 ('Other adjustments') explicitly state '(attach statement)'. Filers frequently enter a value on these lines but forget to include the required supporting documentation. This omission makes the return incomplete and prevents the IRS from understanding the nature of the adjustment. An incomplete filing can lead to processing delays, correspondence from the IRS, and potential disallowance of the adjustment. Always double-check that any line item requiring an attachment has a corresponding statement included with the tax filing.
Incorrect Calculation of Summary Lines
Lines 1c, 7, and 14, as well as the 'Total Section 964(a) E&P' column (f), require combining amounts from multiple other cells. Manual calculations are highly susceptible to simple arithmetic errors, such as incorrect addition or subtraction, especially when dealing with negative numbers (deficits). An error in a summary line invalidates all subsequent calculations on the form, creating a cascading effect that results in an entirely incorrect schedule. To avoid this, use tax software with built-in calculations or an AI-powered tool like Instafill.ai, which can perform these calculations automatically to ensure accuracy.
Improper Use of Category and Country Codes
Line 'a' requires a specific 'Separate Category' code from the IRS instructions, and Line 'b' requires a country code if '901j' is entered on Line 'a'. Filers may use outdated codes, guess the code, or fail to enter the country code on Line 'b' when required. This mistake can lead to the misallocation of foreign tax credits and incorrect application of sanctions rules. Always refer to the latest version of the Form 5471 instructions for the correct codes for the filing year to ensure proper classification and compliance.
Mishandling of Deficits and Negative Numbers
The form involves tracking both profits and deficits, including complex concepts like 'Hovering Deficits' in column (d). Filers often struggle with the correct reporting of negative numbers, either by omitting the negative sign, placing a deficit in a profit column, or incorrectly netting amounts across columns. These errors can drastically misstate the corporation's taxable E&P and its ability to make distributions. It is crucial to report deficits as negative numbers in the correct columns and follow the specific ordering rules for offsetting deficits against profits.
Inconsistent Filer or Corporation Identification
The identification section at the top of the form requires the exact legal name and identifying number (SSN/EIN/Reference ID) for both the filer and the foreign corporation. People often use abbreviations, trade names instead of legal names, or transpose digits in the identifying numbers. These inconsistencies can cause the form to be rejected by the IRS e-filing system or create difficulties for the IRS in matching the schedule to the correct taxpayer and foreign entity records. To prevent this, copy the information precisely from official documents and prior-year filings.
Errors in Reclassifying E&P Between Baskets
Lines 8 and 10 are critical as they track the reclassification of E&P from one tax category to another (e.g., from non-taxed E&P under §959(c)(3) to PTI under §959(c)(2)). These are not new income items but movements between accounts, which is a common point of confusion. An error here, such as double-counting an amount or moving it to the wrong PTI basket, fundamentally breaks the PTI tracking. This can lead to previously taxed income being incorrectly taxed again upon distribution. Understanding the specific events that trigger these reclassifications (like a Subpart F inclusion) is essential for accurate reporting.
Incorrectly Handling Non-Fillable PDF Versions
Tax professionals often receive this form as a flat, non-fillable PDF from clients or prior preparers, leading to manual data entry that is slow and error-prone. The complexity of the grid with its numerous columns and rows makes manual alignment and calculation extremely difficult, often resulting in transcription errors, misaligned entries, and incorrect totals. This can compromise the integrity of the entire tax filing. To mitigate this, use a service like Instafill.ai, which can convert any non-fillable PDF into an interactive, fillable form, enabling accurate data entry and automated calculations to prevent common mistakes.

Frequently Asked Questions About Schedule J (Form 5471)


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 13 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Schedule J (Form 5471).
Can I fill other forms too?
This plan is for your Schedule J (Form 5471): your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Schedule J (Form 5471)?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Schedule J (Form 5471), on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Schedule J (Form 5471) to fill out?
Schedule J (Form 5471) has a Form Complexity Index of 78 out of 100, in the complex tier: 390 fillable fields across 3 pages. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is the purpose of Schedule J (Form 5471)?
Schedule J is used to report the accumulated earnings and profits (E&P) of a Controlled Foreign Corporation (CFC). It tracks the various categories of E&P, including previously taxed and not-yet-taxed amounts, and reconciles the balances from the beginning to the end of the tax year.
Who is required to file Schedule J?
You must file Schedule J if you are a U.S. person required to file Form 5471, 'Information Return of U.S. Persons With Respect to Certain Foreign Corporations.' The schedule is an integral part of the Form 5471 filing and must be attached to it.
In what currency should the amounts on Schedule J be reported?
All monetary amounts reported on Schedule J must be stated in the functional currency of the foreign corporation. Do not convert the amounts to U.S. dollars on this schedule.
What should I do if I don't have all the U.S. shareholders' information for Part I?
If you do not have the information from all U.S. shareholders needed to complete certain columns in Part I, you should check the designated box at the top of Part I. This indicates to the IRS why those specific columns may be incomplete.
What is the difference between Part I and Part II of Schedule J?
Part I provides a comprehensive reconciliation of all accumulated E&P, broken down into numerous specific categories. Part II is a simpler schedule that specifically tracks the balance of non-previously taxed E&P that is subject to recapture as Subpart F income in future years.
How do I submit Schedule J?
Schedule J is not a standalone form and cannot be filed by itself. It must be completed and attached to your Form 5471, which is then filed with your annual income tax return.
What is a 'hovering deficit' in column (d)?
A hovering deficit is a tax concept that arises when a foreign corporation with an E&P deficit is acquired in certain tax-free transactions. This deficit can only be used to offset post-acquisition earnings and cannot reduce pre-acquisition E&P.
The form requires an attached statement for several lines. What should I include?
When an attached statement is required, you must provide a clear and detailed explanation for the adjustment or amount being reported. The statement should specify the line number and column it relates to and provide all necessary supporting calculations or descriptions.
The beginning balance on line 1a is based on the prior year's form. What if this is my first time filing?
If this is the first year of filing for the corporation, the beginning balances will generally be zero. If the corporation existed previously but you are a new filer, you must make a reasonable effort to reconstruct the E&P history to establish an accurate opening balance.
Can AI tools help me fill out the complex Schedule J?
Yes, AI-powered services like Instafill.ai can assist with filling out this form. These tools can help auto-fill fields based on your data, saving time and helping to ensure accuracy on this complex schedule.
How can I use Instafill.ai to complete Schedule J online?
You can upload the Schedule J PDF to the Instafill.ai platform. Its AI will make the form interactive, allowing you to easily enter information, save your progress, and download the completed document ready for filing.
What should I do if my version of the Schedule J PDF is not fillable?
If you have a non-fillable or 'flat' PDF, you can use a service like Instafill.ai to convert it into an interactive, fillable form. Simply upload the document, and the platform will make it easy to complete online.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Schedule J (Form 5471) filled out by AI

$0 today. Cancel before Nov 13 and you pay nothing.

7 days free, then $19.99/month · Cancel anytime