
Instafill.ai
7 days free
AI form filling · 65 fields · 2 pages · done in seconds

Yes! You can use AI to fill out Third Party Financing Addendum

Don't type 65 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
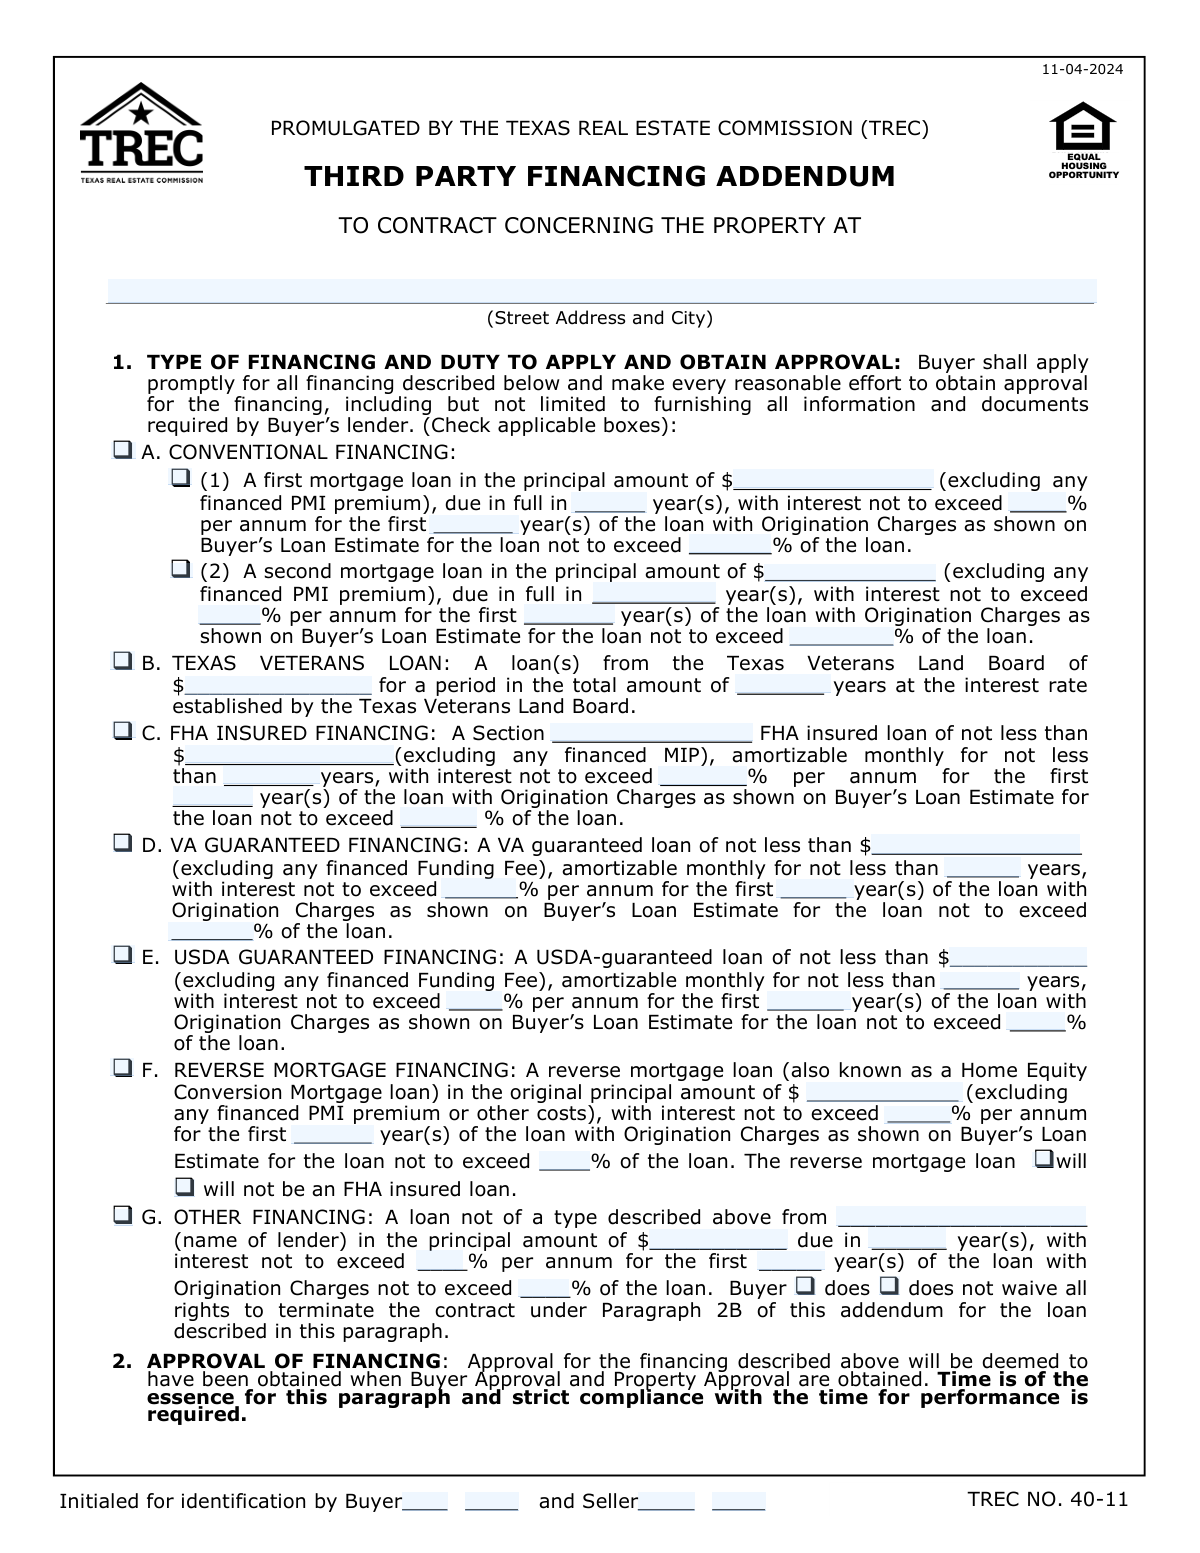
Third Party Financing Addendum, page 1
Complex · 63/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, tables and checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

This addendum is attached to a real estate purchase contract to specify the details of the financing the buyer intends to obtain from a third-party lender. It covers various loan types, including Conventional, FHA, VA, and USDA, and sets conditions for the contract's validity based on the buyer's ability to secure the described loan. Today, this form can be filled out quickly and accurately using AI-powered services like Instafill.ai, which can also convert non-fillable PDF versions into interactive fillable forms.
Fillable fields65
Pages2
Sections15
Tables and lists3
Questions that depend on earlier answers28
Form Complexity IndexComplex, 63/100

The AI checks your answers before you download

13 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Exclusive Financing Type Selection

This check ensures that only one of the primary financing type checkboxes (A. Conventional, B. Texas Veterans, C. FHA, D. VA, E. USDA, F. Reverse Mortgage, G. Other) is selected. The terms for each financing option are mutually exclusive, and selecting more than one creates a critical ambiguity in the contract. If this validation fails, the form is considered invalid as the intended financing method is unclear.

Conditional Completion for Conventional First Mortgage

Validates that if the checkbox for '(1) A first mortgage loan' under Conventional Financing is selected, all associated detail fields (Principal Amount, Loan Term, Maximum Interest Rate) must be filled. This is crucial for ensuring that the financing terms are clearly and completely defined when this option is chosen. An incomplete section renders the financing terms void and can lead to contract disputes.

Loan Term and Initial Period Consistency

Verifies that for any given loan, the 'Initial Interest Period (years)' is less than or equal to the total 'Loan Term (years)'. It is logically impossible for an initial fixed-rate period to exceed the entire life of the loan. This check prevents data entry errors that would create nonsensical and invalid loan terms, ensuring the contract is based on a feasible financial structure.

Mutually Exclusive Buyer Approval Selection

Ensures that only one of the two 'BUYER APPROVAL' checkboxes is selected ('This contract is subject to...' or 'This contract is not subject to...'). These options are mutually exclusive and define whether the contract has a financing contingency. Selecting both or neither creates a critical ambiguity regarding the buyer's right to terminate based on loan approval.

Required Buyer Approval Deadline

Checks that if the contract is marked as 'subject to Buyer obtaining Buyer Approval,' the 'Buyer Approval Deadline (days)' field must contain a positive integer. Without a specified deadline, the contingency period is undefined, making it unclear when the buyer's right to terminate expires. This validation ensures the contingency clause is complete and enforceable.

Loan Amount and Term Numeric Format

Validates that all fields representing dollar amounts (e.g., 'First Mortgage Principal Amount') and time periods (e.g., 'Loan Term (years)') contain only valid, positive numeric values. This prevents data entry errors like text or negative numbers in fields that are critical for financial calculations. Incorrect formatting can cause processing failures and misinterpretation of the contract's financial terms.

And 7 more checks
  • Valid Percentage Range for Charges and Rates
  • Exclusive Waiver of Rights Selection
  • Property Address Completeness
  • Conditional Completion for VA Guaranteed Financing
  • Valid FHA/VA Minimum Appraised Value
  • Presence of Required Initials and Signatures
  • Exclusive Reverse Mortgage FHA Insurance Status

Let AI fill out your Third Party Financing Addendum

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out Third Party Financing Addendum Online for Free in 2026

What the AI walks you through.

  1. Navigate to Instafill.ai and upload your Third Party Financing Addendum or select it from a template library.
  2. Provide the property address and the names of the buyer(s) and seller(s) as they appear on the main contract.
  3. Select the appropriate financing type by checking the box for Conventional, FHA, VA, USDA, or another loan type.
  4. Enter the specific financial details for the chosen loan, such as the principal amount, loan term, maximum interest rate, and origination charge limits.
  5. Indicate whether the contract is contingent on buyer approval and specify the deadline for obtaining it.
  6. Review all the information automatically populated by the AI to ensure accuracy and completeness.
  7. Electronically initial and sign the document, then share it with the seller for their initials and signature.

Common Mistakes in Completing Third Party Financing Addendum

The ones the AI is built to catch.

Selecting the Wrong Financing Type
Buyers sometimes check the box for the wrong loan type, such as selecting 'FHA Insured Financing' when they are actually approved for a 'Conventional Financing' loan. This often happens due to a misunderstanding of loan products or simple clerical error. This mistake invalidates the terms of the financing addendum, causing significant delays, contract disputes, or even termination of the purchase agreement. To avoid this, buyers must confirm their exact loan program with their lender before filling out the form.
Missing Details for a Selected Loan Type
A frequent error is checking a primary financing box (e.g., 'A. CONVENTIONAL FINANCING') but then failing to fill in the mandatory subordinate fields like 'First Mortgage Principal Amount', 'Loan Term', and 'Maximum Interest Rate'. This renders the financing contingency vague and potentially unenforceable, as the specific terms the buyer must be approved for are not defined. Always perform a secondary review to ensure all required fields corresponding to a selected loan type are completed accurately.
Confusing Loan Amount with Purchase Price
Users often mistakenly enter the property's total purchase price into fields like 'First Mortgage Principal Amount' or 'VA Guaranteed Loan Amount'. These fields are intended only for the amount being borrowed, not the full sale price. This error creates an incorrect legal document and can cause confusion for the lender, seller, and title company, requiring amendments and delaying the closing process. Double-check that you are entering only the financed amount, which is the purchase price minus your down payment.
Entering Unrealistic Loan Terms
In an attempt to secure the best possible deal, buyers may enter an unachievably low 'Maximum Interest Rate' or 'Origination Charges Limit'. If market conditions make these terms impossible for a lender to meet, the buyer may not be able to obtain 'Buyer Approval' as defined in the contract. This can jeopardize the transaction and lead to disputes over the financing contingency. It is crucial to consult with a lender to input realistic, market-based figures that you can reasonably expect to be approved for.
Contradictory Checkbox Selections
The form contains mutually exclusive options, such as 'This contract is subject to Buyer obtaining Buyer Approval' versus 'This contract is not subject to Buyer obtaining Buyer Approval'. Users sometimes check both boxes, or check both 'Buyer does waive rights' and 'Buyer does not waive rights', creating a legal contradiction. This ambiguity makes the addendum invalid and can lead to serious contract disputes. To prevent this, read each set of options carefully and select only one.
Incorrect Formatting of Percentages and Numbers
Many fields have specific formatting requirements, such as entering a number for an interest rate without the '%' symbol, or a loan amount without a '$' or commas. For example, entering '3.5%' instead of '3.5' in the 'Maximum Interest Rate' field can cause data entry or system rejection issues. These formatting errors can lead to misinterpretation of the terms and require correction. AI-powered tools like Instafill.ai can help prevent these mistakes by automatically validating and formatting data correctly as you type.
Incomplete or Mismatched Property Address
This form has two separate fields for the property address, and users often fill them out inconsistently or incompletely, for example, by omitting a unit number or zip code. An incorrect or incomplete address can create ambiguity and legal challenges, as it must precisely match the address on the main purchase contract. Ensure the full, correct address is entered identically in all required locations on the document.
Setting an Impractical Buyer Approval Deadline
When making the contract subject to Buyer Approval, users must specify a deadline in days. Entering a number that is too short (e.g., 7 days) may not give the lender sufficient time to complete underwriting and issue a formal approval, putting the buyer's earnest money at risk if they cannot terminate in time. This deadline should be discussed with the real estate agent and lender to set a realistic timeframe that protects the buyer's interests.
Forgetting All Initials and Signatures
A simple but critical oversight is missing one or more of the initial or signature lines for all parties (Buyer 1, Buyer 2, Seller 1, Seller 2). An addendum that is not fully initialed and signed by all parties to the contract is not legally binding. This can invalidate the financing contingency and create major issues at closing. Before considering the form complete, carefully scan every page for all required signature and initial blocks.
Filling Out Multiple Financing Sections
A buyer typically uses only one type of financing, yet may erroneously fill out details in more than one main section (e.g., completing fields in both 'Conventional Financing' and 'FHA Insured Financing'). This creates confusion and a legally ambiguous contract, as it's unclear which financing terms apply. Buyers should only complete the single section that corresponds to their specific loan. If the form is a non-fillable PDF, a tool like Instafill.ai can convert it to an interactive version, making it easier to navigate and fill only the correct sections.

Frequently Asked Questions About Third Party Financing Addendum


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 19 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your Third Party Financing Addendum.
Can I fill other forms too?
This plan is for your Third Party Financing Addendum: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out Third Party Financing Addendum?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of Third Party Financing Addendum, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is Third Party Financing Addendum to fill out?
Third Party Financing Addendum has a Form Complexity Index of 63 out of 100, in the complex tier: 65 fillable fields across 2 pages. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is the purpose of the Third Party Financing Addendum?
This form is an addendum to a real estate sales contract that outlines the terms of the loan the buyer is seeking to purchase the property. It makes the contract contingent on the buyer successfully obtaining the specified financing.
Who needs to complete this form?
The buyer and their real estate agent complete this form to specify the details of the financing they plan to use. It must then be signed by both the buyer and the seller to become part of the purchase contract.
Do I need to fill out all the financing sections from A to G?
No, you only need to check the box and complete the section that corresponds to the specific type of loan you are applying for, such as Conventional, FHA, or VA. The other sections should be left blank.
What does the 'Buyer Approval' section mean?
This section determines if the contract is contingent on you receiving loan approval from your lender within a specified number of days. If you don't get approval within that timeframe, this contingency gives you the right to terminate the contract and have your earnest money returned.
Why do I need to enter a maximum interest rate and loan term?
These fields protect you, the buyer, by defining the loan terms you are willing to accept. If you can only secure a loan with a higher interest rate or different term than what's specified, you are not obligated to proceed with the purchase.
What happens if the property's appraised value is lower than the amount in the 'FHA/VA Required Provision'?
If the property appraises for less than the amount specified, this provision allows you, the buyer, to terminate the contract without penalty. The seller may also have the option to adjust the sales price to match the appraised value.
I'm getting a first and a second mortgage. How do I fill that out?
You would check the box for 'A. CONVENTIONAL FINANCING' and then complete the details for both '(1) A first mortgage loan' and '(2) A second mortgage loan' within that section.
What are 'Origination Charges'?
Origination charges are fees charged by the lender for processing your loan application, which may include underwriting and other administrative costs. This form lets you set a maximum percentage for these charges that you are willing to pay.
Should I check the box that the contract is 'not subject to Buyer obtaining Buyer Approval'?
Checking this box means you are obligated to buy the property even if your financing falls through, which is very risky and could result in the loss of your earnest money. It is generally not recommended unless you are certain your financing is secure.
Where do I submit this form after completing it?
This addendum should be submitted along with your purchase offer to the seller or their agent. Once signed by all parties, it becomes a legally binding part of the sales contract.
Can an AI tool help me fill out this Third Party Financing Addendum?
Yes, services like Instafill.ai use AI to accurately auto-fill form fields from your saved data, which can save you significant time and help prevent errors.
How can I use Instafill.ai to complete this form online?
Simply upload the Third Party Financing Addendum to the Instafill.ai platform. The AI will identify the fields, and you can then fill them out interactively or have the system auto-fill information from your profile.
The PDF version of this form I have isn't fillable. What can I do?
You can use a service like Instafill.ai, which can convert flat, non-fillable PDFs into interactive, fillable forms. This allows you to easily type your information directly into the fields online.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your Third Party Financing Addendum filled out by AI

$0 today. Cancel before Nov 19 and you pay nothing.

7 days free, then $19.99/month · Cancel anytime