
Instafill.ai
7 days free
AI form filling · 396 fields · 5 pages · done in seconds

Yes! You can use AI to fill out ACORD 131, Umbrella / Excess Section

Don't type 396 fields by hand. Tell our AI about yourself, or upload a document you already have, and it fills every field in seconds. You check it, then download, print or sign.
7 days free, then $19.99/month · Cancel anytime
AI fills it, no typingEncrypted, never used to train AICancel in two clicks
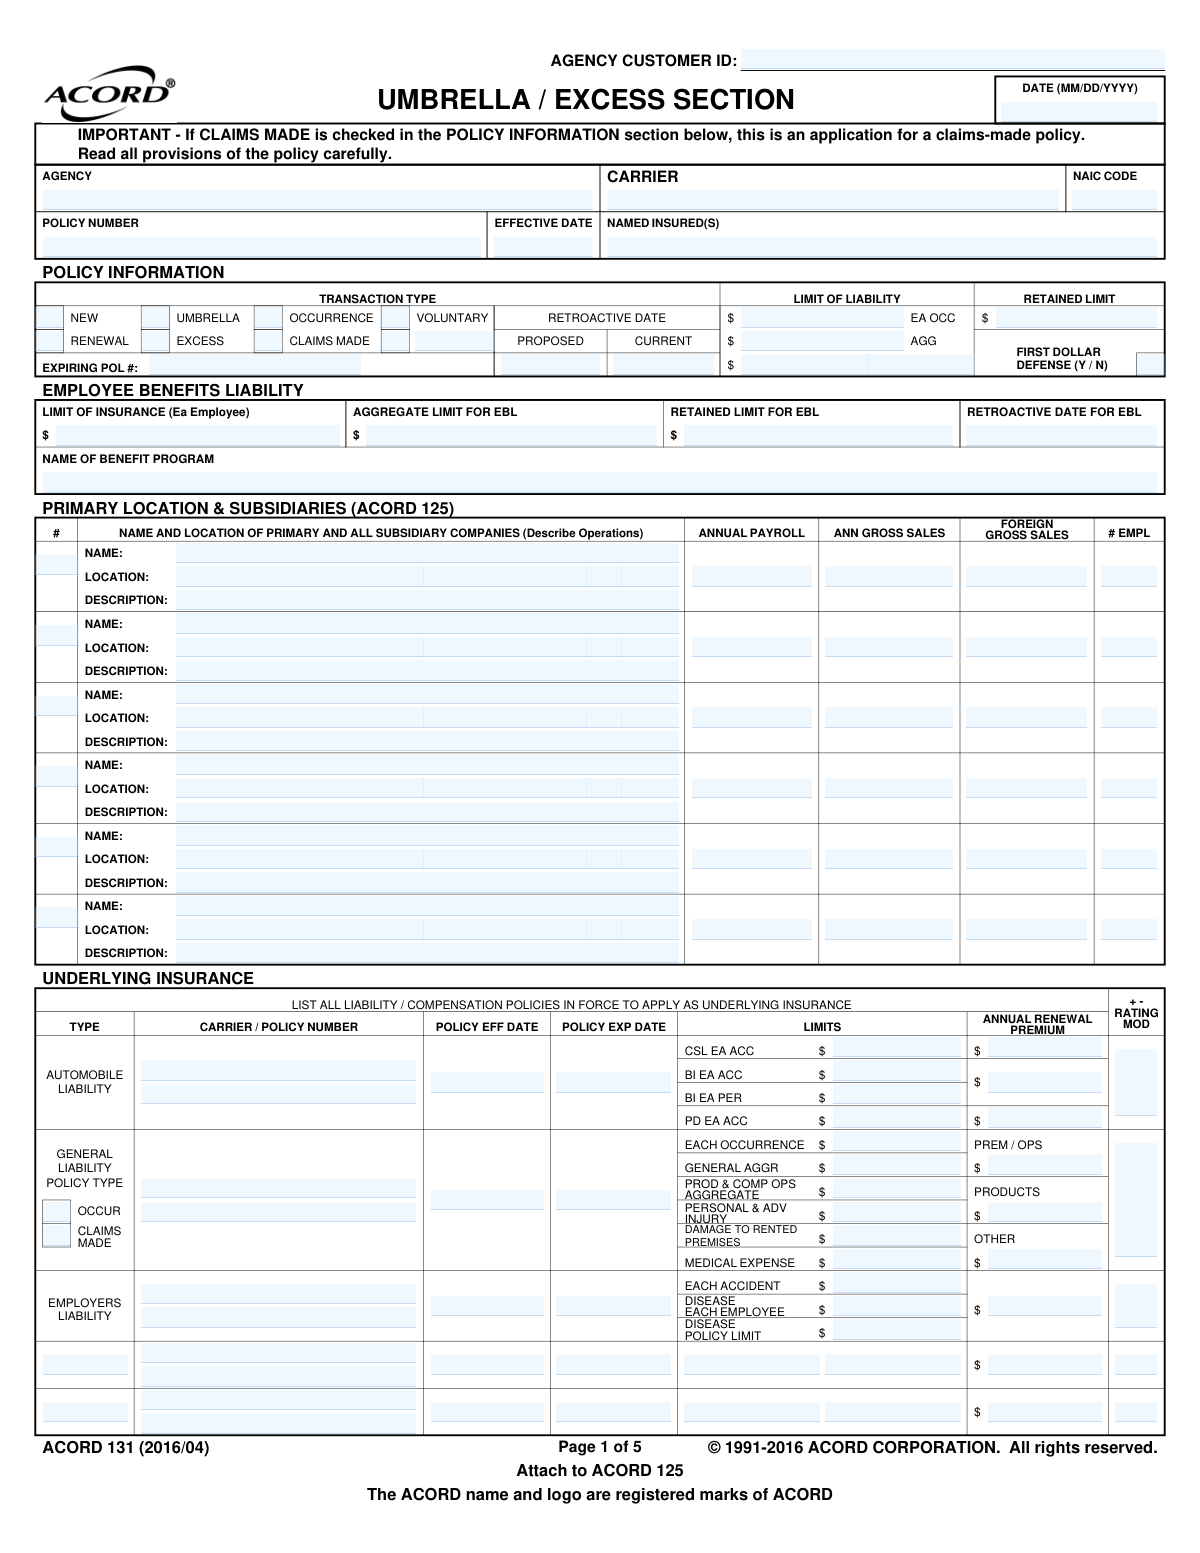
ACORD 131, Umbrella / Excess Section, page 1
Very Complex · 83/100Form Complexity Index

The AI does the filling. You just check it.

No typing into boxes, nothing to install.

Tell the AI about youAnswer a few questions in plain words, or upload a document you already have. That is all the typing there is.
AI fills every field in secondsIt puts each answer in the right box on every page, tables and checkboxes included.
Check it and downloadReview every field, change anything, then download, print or sign the PDF.

What this form asks for

The AI fills all of it, from your answers or your documents.

ACORD Form 131 is a comprehensive application used by insurance agents and underwriters to gather necessary information for issuing a commercial umbrella or excess liability policy. It details the applicant's business operations, existing insurance coverage, and specific risk exposures to determine eligibility and pricing for higher liability limits. Today, this form can be filled out quickly and accurately using AI-powered services like Instafill.ai, which can also convert non-fillable PDF versions into interactive fillable forms.
Fillable fields396
Pages5
Sections33
Tables and lists3
Questions that depend on earlier answers45
Form Complexity IndexVery Complex, 83/100

The AI checks your answers before you download

14 checks built for this form, so a wrong date or a missing answer is caught before anyone else sees it.

Mandatory Retroactive Date for Claims-Made Policies

This check ensures that if the policy type is 'CLAIMS MADE', the 'RETROACTIVE DATE' field is populated with a valid date. A claims-made policy only covers claims reported during the policy period for incidents that occurred on or after the retroactive date, making this date essential for defining the scope of coverage. Failure to provide this date will result in an incomplete application and prevent accurate quoting and binding.

Required Expiring Policy Number for Renewals

Validates that if the 'TRANSACTION TYPE' is 'RENEWAL', the 'EXPIRING POL #' field is not empty. This information is critical for underwriters to locate the previous policy term's information, review prior coverage, and ensure continuity. An empty field for a renewal transaction will cause processing delays and require manual follow-up.

Logical Underlying Policy Period

Verifies that for each policy listed in the 'UNDERLYING INSURANCE' section, the 'POLICY EXP DATE' is on or after the 'POLICY EFF DATE'. This ensures the policy period is logical and represents a valid term of coverage. An expiration date before an effective date is an impossible scenario and indicates a data entry error that must be corrected.

Mandatory Explanation for 'Yes' Responses

This rule checks all questions where a 'YES' answer requires an explanation, such as question 5 in the Auto Liability section. If a user answers 'YES', the corresponding explanation field must be filled out. These explanations are crucial for underwriters to assess non-standard risks, and missing information can lead to application rejection or incorrect pricing.

Mutually Exclusive Claims Experience

Ensures that the applicant either provides details of past liability claims or checks the 'NO SUCH CLAIMS' box, but not both. These two states are mutually exclusive and selecting both creates a logical contradiction. This validation prevents ambiguity in the applicant's claims history, which is a primary factor in underwriting.

Valid UM/UIM Selection and Rejection

For states with specific Uninsured/Underinsured Motorist coverage options (e.g., New Hampshire, Louisiana), this validates that the applicant has made a clear choice. The user must either select limits and initial, or reject coverage and initial, but cannot do both or neither. This is a legal requirement to document the applicant's choice, protecting both the insured and the agency from Errors & Omissions exposure.

And 8 more checks
  • Florida National Producer Number Requirement
  • Retained Limit vs. Limit of Liability Consistency
  • Arkansas Defense Cost Compliance
  • Required Documentation for Foreign Operations
  • Underlying Insurance Schedule Completeness
  • Exclusive Policy Type Selection
  • Conditional Details for Incidental Malpractice
  • Valid Three-Year Product Liability Sales Data

Let AI fill out your ACORD 131

No typing. Every field filled in seconds, checked, ready to sign.

7 days free, then $19.99/month · Cancel anytime

How to Fill Out ACORD 131 Online for Free in 2026

What the AI walks you through.

  1. Navigate to Instafill.ai and upload or select the ACORD 131, Umbrella / Excess Section form.
  2. Provide the named insured's information and specify the desired policy information, such as effective dates and whether it's a new or renewal policy.
  3. Detail all underlying insurance policies, including general liability, automobile liability, and employers liability, by listing carriers, policy numbers, limits, and effective dates.
  4. Complete the sections on underlying insurance coverage and additional exposures by answering questions about your business operations, such as product liability, aircraft use, and care, custody, control.
  5. Disclose any liability claims from the past five years that exceeded $10,000, providing details for each occurrence.
  6. Use the AI to review all entered information for completeness and consistency across the form, ensuring all required fields are filled.
  7. Electronically sign the application in the designated signature section and submit it to your insurance producer or carrier.

Common Mistakes in Completing ACORD 131

The ones the AI is built to catch.

Misreporting Underlying Insurance Limits
Applicants often confuse different limit types, such as 'Each Occurrence' versus 'General Aggregate,' or transpose digits when entering policy limits from their existing documents. This happens due to the complexity of insurance declaration pages and the dense grid format on the form. Inaccurate limits can lead to the underwriter quoting the wrong premium or, worse, issuing a policy with a coverage gap, leaving the business exposed. To avoid this, double-check all limit amounts against the source policy documents; tools like Instafill.ai can help by intelligently extracting and placing this data into the correct fields, reducing manual entry errors.
Incorrectly Selecting Policy Type (Occurrence vs. Claims-Made)
Many applicants do not understand the critical difference between 'Occurrence' and 'Claims-Made' coverage, leading them to select the wrong type or provide incorrect associated dates, like the Retroactive Date. This mistake can result in significant, unexpected gaps in coverage, as the trigger for a payable claim is fundamentally different for each policy type. Always confirm the structure of your underlying policies before applying, and if unsure, consult your insurance agent for clarification.
Omitting Required Explanations for 'Yes' Responses
The form contains numerous questions requiring a 'Yes' or 'No' answer, with instructions to 'Explain all YES responses.' Applicants frequently check 'Yes' to an exposure, such as owning watercraft or performing marine work, but fail to provide the necessary details in the space provided. This omission creates significant delays as the underwriter must halt the quoting process to request the missing information. To prevent this, carefully review each section and provide a complete, detailed explanation for every 'Yes' answer, attaching an ACORD 101 schedule if more space is needed.
Failing to Disclose Full Prior Claims History
The application requires disclosing all liability claims exceeding $10,000 in the past five years, yet applicants may forget claims, underestimate their potential, or intentionally omit them to seek a better rate. This is a material misrepresentation that can lead to the policy being voided, a future claim being denied, or even accusations of insurance fraud. It is crucial to maintain accurate records and disclose all relevant claim history; checking 'NO SUCH CLAIMS' when claims do exist is a serious error.
Incomplete Listing of Underlying Insurance Policies
An Umbrella/Excess policy sits on top of other primary liability policies, so a complete and accurate list is essential for proper rating and coverage structuring. Applicants sometimes forget to include all relevant policies, such as a separate Professional Liability (E&O), Pollution, or Foreign Liability policy. This oversight can result in a dangerous coverage gap where the umbrella policy does not apply because the underlying policy was not scheduled, leaving the insured responsible for the full amount of a large claim.
Improperly Selecting or Rejecting UM/UIM Coverage
The Uninsured/Underinsured Motorist (UM/UIM) section on page 5 is complex, with state-specific rules and requirements for initials. Applicants often get confused, selecting limits but forgetting to initial, or rejecting coverage unintentionally by leaving the section blank. An error here can lead to a dispute after an accident, where the applicant may not have the coverage they thought they selected. Carefully read the instructions for your state and ensure you both select/reject and provide initials as required.
Omitting or Mismatching Critical Policy Dates
The form requires several dates, including policy effective/expiration dates and, for claims-made policies, the Retroactive Date. Applicants often make simple data entry errors, transpose month and day, or leave a required date blank. An incorrect Retroactive Date is particularly dangerous as it can create a gap in coverage for prior acts, while incorrect policy term dates can cause lapses in coverage. Using a tool like Instafill.ai can help prevent these mistakes by validating date formats and auto-filling information from existing documents.
Failing to Sign and Date the Application
An application is not a valid, legally binding document until it is signed and dated by the applicant. It's a simple but surprisingly common oversight for applicants to complete all five pages but forget to sign the final page. An unsigned application cannot be processed by the carrier, leading to unnecessary delays in binding coverage and leaving the business uninsured for longer than intended. Always perform a final check to ensure all signature and date fields are properly completed before submission.
Mismatching Coverage and Exposure Checkboxes
In the 'Underlying Insurance Coverage Information' section, applicants must indicate both the coverages included in their underlying policies and whether their business has an exposure for that risk. A common error is to check one but not the other (e.g., checking that they have 'Liquor Liability' coverage but not checking the 'Exposure' box, or vice versa). This ambiguity forces the underwriter to seek clarification, slowing down the quote and delaying the issuance of the policy.
Vague Descriptions of Operations or Exposures
Fields such as 'DESCRIBE TYPICAL JOBS PERFORMED' for contractors or the description of property under 'Care, Custody, Control' require specific details for accurate risk assessment. Applicants often provide one-word or overly brief answers that lack the necessary detail for an underwriter to properly evaluate the exposure. This leads to follow-up questions and delays. If the form is a non-fillable PDF, a tool like Instafill.ai can convert it to a fillable version with expandable text fields to ensure you can provide complete information.

Frequently Asked Questions About ACORD 131


Is it really free for 7 days?
Yes. You pay $0 today. Cancel before Nov 18 and you are never charged. Keep it, and it is $19.99 a month for 5 fills of your ACORD 131.
Can I fill other forms too?
This plan is for your ACORD 131: your own AI agent fills it as often as 5 times a month. To fill other forms and upload your own, choose a Professional plan from your account.
How do I cancel?
From your account, in two clicks, any time. No email, no call.
How does the AI fill out ACORD 131?
You answer a few questions in plain words, or upload a document you already have. The AI reads what you give it and puts each answer into the right field of ACORD 131, on every page, in seconds. It checks the answers against the form's own rules, and you review and change anything before you download, print or sign.
What happens to my information?
It is encrypted in transit and at rest, and it is never used to train AI.
How complex is ACORD 131 to fill out?
ACORD 131 has a Form Complexity Index of 83 out of 100, in the very complex tier: 396 fillable fields across 5 pages. Instafill.ai's AI fills it in under a minute, with every field there for you to review before you download.
What is the purpose of the ACORD 131 form?
The ACORD 131 is a supplementary application used to apply for commercial Umbrella or Excess liability insurance. This type of policy provides additional coverage limits above and beyond your primary liability policies, such as General Liability and Auto Liability.
Who needs to complete the ACORD 131 form?
Any business applying for or renewing an Umbrella or Excess liability policy needs to complete this form. It is attached to the main commercial insurance application, ACORD 125, to provide underwriters with detailed information about underlying risks and coverages.
What information do I need to have ready to fill out this form?
Before starting, gather all your existing liability policy documents. You will need details like policy numbers, carriers, effective dates, coverage limits, and information about your business operations, sales figures, and any liability claims from the past five years.
What is the difference between an 'Umbrella' and an 'Excess' policy on this form?
An Excess policy provides higher limits but follows the exact terms of your underlying policy. An Umbrella policy also provides higher limits but can sometimes offer broader coverage for claims not covered by your primary policies, subject to a self-insured retention (deductible).
What does the 'Underlying Insurance' section require?
This section requires a complete list of all your primary liability policies that will sit underneath the umbrella policy. You must provide the carrier, policy number, effective dates, and limits for each policy, including General Liability, Auto, and Employers Liability.
What is the difference between an 'Occurrence' and 'Claims Made' policy?
An 'Occurrence' policy covers incidents that happen during the policy period, no matter when the claim is filed. A 'Claims Made' policy only covers claims that are filed and reported during the policy period, and you must specify the retroactive date.
What should I do for the 'Previous Experience' section if I have no large claims?
If your business has not had any liability claims exceeding $10,000 in the past five years, you can simply check the box labeled 'NO SUCH CLAIMS'. Otherwise, you must provide details for each significant claim.
My business has foreign operations. How do I note this on the form?
In the 'Product Liability' section, there is a question about foreign operations or products. If you answer 'YES', the form instructs you to attach ACORD 815, the Foreign Liability and Property Section, to provide the necessary details.
What is 'Care, Custody, Control' exposure?
This refers to personal or real property that you do not own but is in your care and for which you are responsible, such as a leased building or customers' property. You must provide details about the property's value and any legal agreements in place.
How do I submit the ACORD 131 form?
The ACORD 131 is not a standalone application; it is a section that must be attached to the ACORD 125, Commercial Insurance Application. Both forms are submitted together to your insurance agent or carrier for underwriting.
Can AI tools help me fill out the ACORD 131?
Yes, services like Instafill.ai use AI to auto-fill form fields accurately and save time. This is especially useful for a detailed application like the ACORD 131, as it can pull information from your existing policy documents.
How can I fill out this form online if I only have a PDF?
You can use a service like Instafill.ai to easily fill out the ACORD 131 online. Simply upload the PDF, and the platform will make it an interactive form that you can complete, sign, and share digitally.
The PDF of the ACORD 131 I have is not fillable. What can I do?
If you have a non-fillable or 'flat' PDF, you can use a tool like Instafill.ai. It can convert the static PDF into an interactive, fillable form that you can easily complete on your computer or mobile device.
Encrypted in transit and at restNever used to train AIDelete your forms any time

Get your ACORD 131 filled out by AI

$0 today. Cancel before Nov 18 and you pay nothing.

Other forms like this one

ACORD forms: ACORD 84, Dwelling Fire Application (2013/09), ACORD 140 (2014/12), Property Section (Attach to ACORD 125), ACORD 36, Agent/Broker of Record Change, ACORD 131, Umbrella / Excess Liability Section, ACORD 125, Commercial Insurance Application and ACORD 143, Transportation Section, ACORD 125, Commercial Insurance Application, ACORD 125, Commercial Insurance Application, Applicant Information Section, ACORD 27, Evidence of Property Insurance, ACORD 24, Certificate of Property Insurance, ACORD 28, Evidence of Commercial Property Insurance, ACORD 141, Commercial Insurance Application - Crime Section, ACORD 140, Property Section, ACORD 80, Homeowner Application, ACORD 82, Watercraft Application, ACORD 85, Mobile Home Application, ACORD 160, Property Loss Notice, ACORD 75, Insurance Binder, ACORD 83, Personal Umbrella Application, ACORD 137 CA, Commercial Auto Application - California, ACORD 81, Personal Inland Marine Application (2012/02)

commercial insurance forms: Habitational Risks Supplement Application Form, Record of Advice and Needs Analysis (Non-Life Insurance — Personal and Commercial Lines), ACORD 125, Commercial Insurance Application and ACORD 143, Transportation Section, ACORD 125, Commercial Insurance Application, ACORD 125, Commercial Insurance Application, Applicant Information Section, Evidence of Commercial Property Insurance, ACORD 127, Business Auto Section, ACORD 137 CA, Commercial Auto Application - California, ACORD 140, Property Section, ACORD 155, Equipment Breakdown Section, ACORD 163, Commercial Auto Driver Information Schedule, ACORD 141, Commercial Insurance Application - Crime Section, ACORD 159, Business Income Worksheet, ACORD 175, Commercial Policy Change Request, ACORD 28, Evidence of Commercial Property Insurance, ACORD 129, Vehicle Schedule (2009/11), ACORD 139, Statement of Values, ACORD 152, Commercial Inland Marine Section, ACORD 185, Restaurant/Tavern Supplement, ACORD 810, Business Income / Extra Expense / Rental Value

7 days free, then $19.99/month · Cancel anytime